

Cumberland Farms has filed for a Nasdaq IPO as CMBY, but it has not set a price. Its F-1/A, filed September 4, 2026, shows $16.3 billion of 2025 revenue, 3,313 sites and $5.8 billion of debt. The price range and share count are still blank.
The company in the filing is bigger than the New England chain. Cumberland Farms Limited is EG Group's carve-out of its entire US business plus its stations in Germany and the Benelux, renamed after its best-known brand. Since the last amendment the IPO has stalled. Reuters reported on October 24 that the listing was delayed after takeover interest, and that Alimentation Couche-Tard had proposed $7.5 billion to $8 billion, citing The Times. This is our analysis of a public filing, not a recommendation to buy or sell anything.
Cumberland Farms IPO: The Snapshot
The registrant is Cumberland Farms Limited, a Cayman Islands company with its principal executive offices in Charlotte, North Carolina, per the F-1/A cover. It has applied to list ordinary shares on the Nasdaq Global Select Market under CMBY. BofA Securities and Goldman Sachs lead the syndicate, followed by Jefferies, Barclays, J.P. Morgan, Wells Fargo, Deutsche Bank, UBS and BNP Paribas. Every share in the filing is offered by the company, and no selling shareholders are named.
| Metric | Value | Source |
|---|---|---|
| Revenue, FY2025 (year to Dec 31, 2025) | $16,343M | F-1/A, summary financial data |
| Revenue, H1 2026 (six months to Jun 30) | $8,968M (H1 2025: $7,944M) | F-1/A, summary financial data |
| Gross profit, FY2025 | $2,675M | F-1/A, results of operations |
| Adjusted EBITDA, FY2025 (non-GAAP) | $693M | F-1/A, key metrics |
| Net loss, FY2025 | $(145)M | F-1/A, summary financial data |
| Sites, Jun 30, 2026 | 3,313 (US 1,535; Europe 1,778) | F-1/A, key metrics and Business |
| Total debt, Jun 30, 2026 | $5,822M (cash $1,014M) | F-1/A, Capitalization |
| Price range / shares offered | Blank in the filing | F-1/A cover |
Source: Cumberland Farms Limited F-1/A, Amendment No. 1, SEC EDGAR, filed September 4, 2026 (the document is dated September 3). Fiscal years end December 31. The -3.9% change is our arithmetic.
Who Is the Issuer? Cumberland Farms vs EG Group
The issuer is not the old Cumberland Farms company, and it is not all of EG Group. Under "Basis of Presentation", the F-1/A says Cumberland Farms Limited is made up of the operations of EG Group Limited's affiliates in the United States, Germany, Belgium, the Netherlands and Luxembourg, plus some UK legal entities. A reorganization between December 2025 and the IPO moved the company from the Netherlands to Luxembourg, then to Delaware, then to the Cayman Islands. It was named LuxBridge International Limited until June 23, 2026, when it became Cumberland Farms Limited. EDGAR still lists the LuxBridge name for the three draft filings.
EG Group Limited will remain the direct parent after the IPO and is expected to hold a majority of the votes, which makes Cumberland Farms a "controlled company" under Nasdaq rules. The F-1/A says the company does not currently plan to use the governance exemptions that status allows. EG Group is in turn controlled by Optima Bidco (Jersey) Limited. Optima Bidco's principal shareholders are Optima Group S.à r.l., owned by funds managed by TDR Capital, and the founders, Mohsin and Zuber Issa. EG's percentage after the IPO is blank in this amendment. The Telegraph reported that TDR holds 50% and each brother 25%. That figure comes from the press, not from the filing.
That answers the "who owns Cumberland Farms" question. The family that built the chain sold it to EG in 2019. The MetroWest Daily News reports that the Haseotes family owned the business until then and that the price was not disclosed. The F-1/A dates completion to October 2019. Investors in CMBY would be buying a minority stake in a TDR- and Issa-controlled forecourt group.
From a Rhode Island Dairy to a 3,313-Site Chain
The F-1/A says Cumberland Farms was founded in 1939 in Cumberland, Rhode Island. The MetroWest Daily News describes it as starting as a dairy farm and moving into retail stores from 1957. The chain was long based in Westborough, Massachusetts. C-Store Dive notes that headquarters moved to Charlotte in 2025, and Charlotte is the address on the filing. Today the Cumberland Farms banner covers 666 sites in the Northeast and Florida. Those are large stores, averaging about 3,500 square feet, across 12 states.
EG Group grew mostly through acquisitions. From 2018 to 2022, the filing says, it bought about 760 convenience sites from Kroger, 570 Cumberland Farms sites, 540 sites from Woolworths in Australia and more than 2,000 Esso sites in Italy and Germany. It has since been selling assets to cut debt, and the proceeds the filing lists are large.
EG Group Divestitures Since 2023 (Proceeds, $M)
More than $4.4B of assets sold to pay down debt before the IPO
Cumberland Farms F-1/A, Prospectus Summary, SEC EDGAR, Sep 2026; bars drawn at the stated floor or approximate figure
Data
| Item | Value |
|---|---|
| Majority of UK business | over $3B |
| Australia (closed Jun 30, 2026) | ~$830M |
| Italy | over $450M |
| France (closed Jul 31, 2026) | ~$135M |
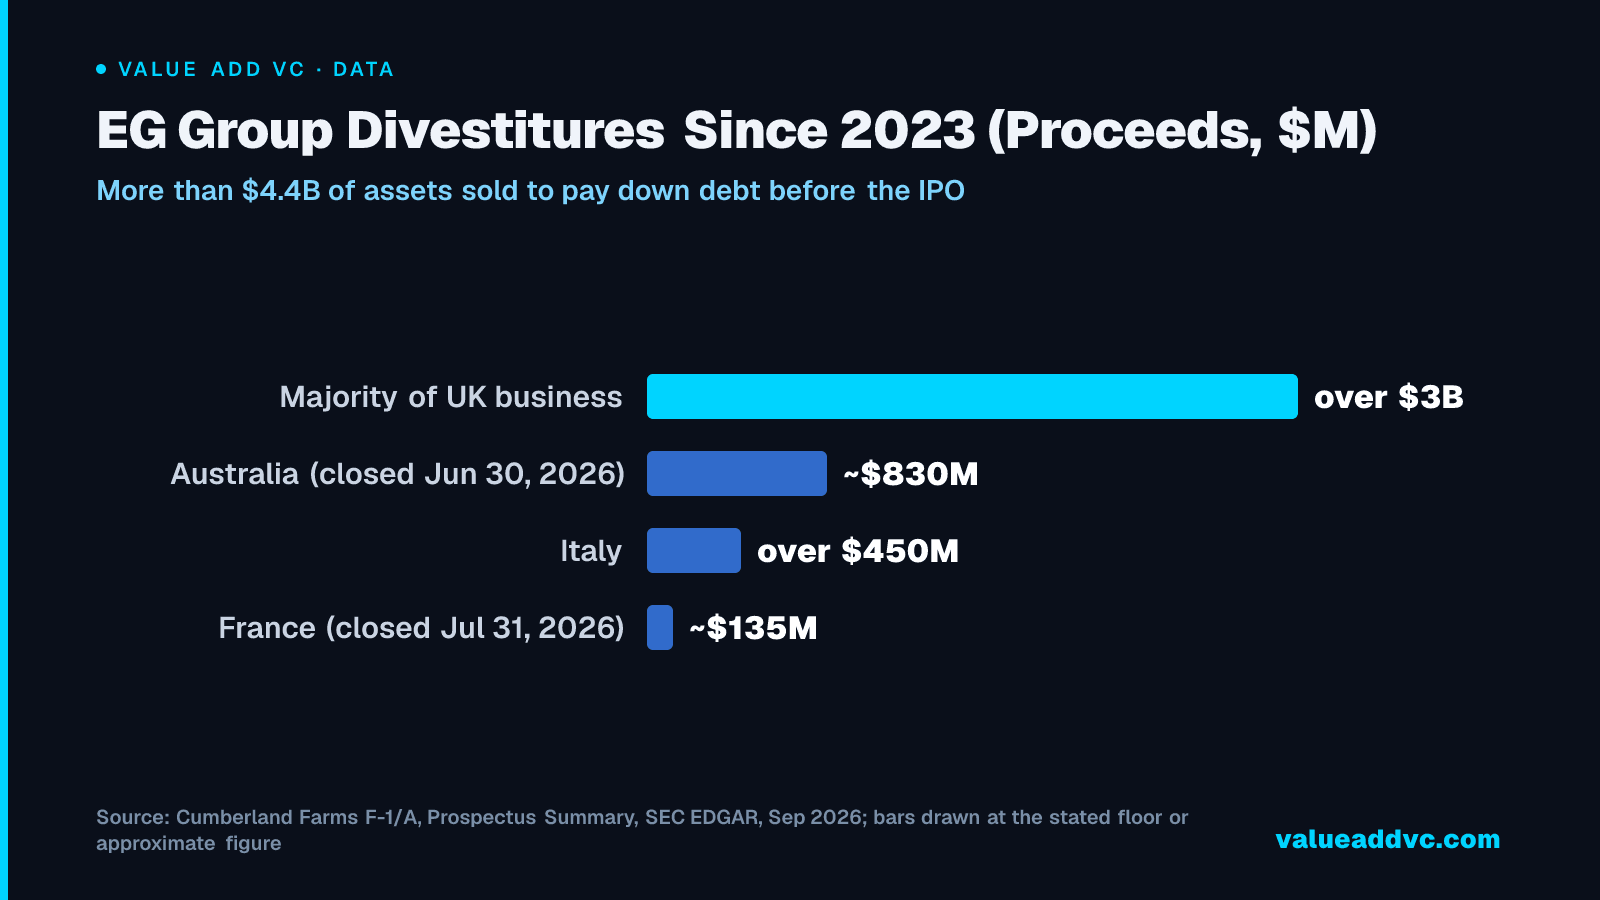
What is left is 1,535 US sites in 24 states, 95% of them company-owned and company-operated, and 1,778 European sites in four countries. Those figures are as of June 30, 2026. The June 1, 2026 purchase of Coen Markets added 57 stores and 20 dealer sites in Ohio, Pennsylvania and West Virginia. The "more than $4.4 billion" in the chart is our sum of the filing's floor figures. The filing also says a further $130 million from the parent's sale of its UK Starbucks business will be contributed to the company.
Cumberland Farms Revenue: What the F-1/A Shows
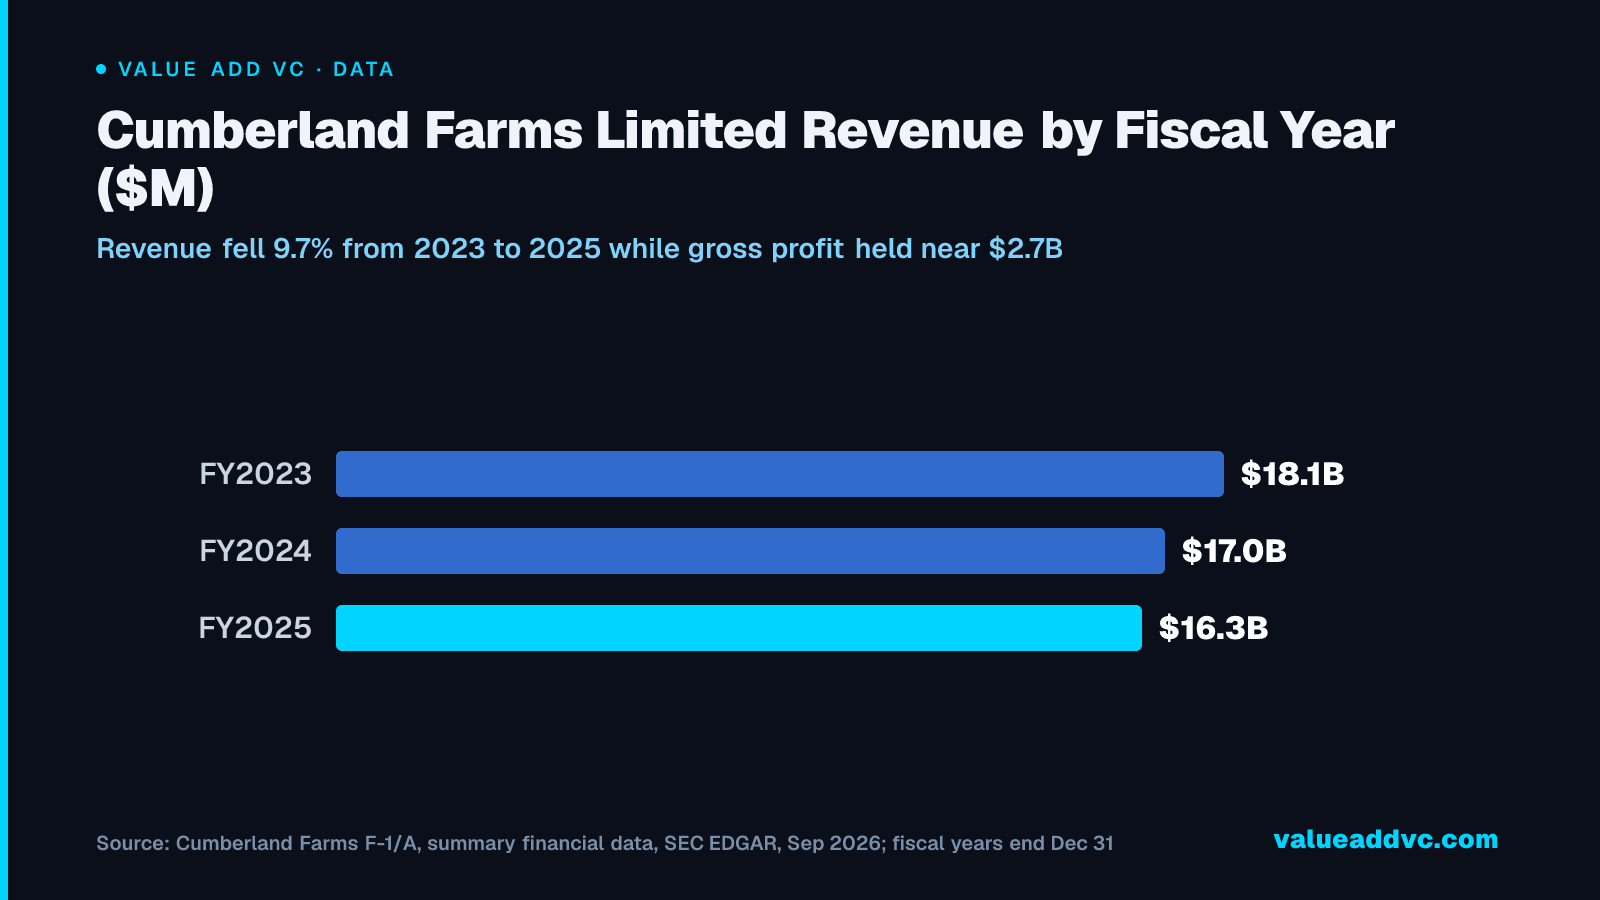
Cumberland Farms revenue fell for two straight years: from $18.105 billion in 2023 to $17.005 billion in 2024 and $16.343 billion in 2025. Revenue at a fuel retailer moves with pump prices and gallons sold, so falling revenue does not mean falling profit. Gross profit was $2.704 billion, $2.746 billion and $2.675 billion over the same three years. In 2025 the United States produced $7.408 billion of revenue and Europe $8.935 billion, per the segment table.
Cumberland Farms Limited Revenue by Fiscal Year ($M)
Revenue fell 9.7% from 2023 to 2025 while gross profit held near $2.7B
Cumberland Farms F-1/A, summary financial data, SEC EDGAR, Sep 2026; fiscal years end Dec 31
Data
| Item | Value |
|---|---|
| FY2023 | $18.1B |
| FY2024 | $17.0B |
| FY2025 | $16.3B |
The 2026 interim numbers turned up. Revenue for the six months to June 30, 2026 was $8.968 billion, against $7.944 billion a year earlier. Second-quarter revenue was $4.980 billion, against $4.216 billion. Adjusted EBITDA, a non-GAAP measure the company reconciles to pre-tax income, rose to $352 million in the half from $281 million. That increase came mostly from fuel margin, not volume, as the next table shows.
| FY2025 ($M) | Revenue | Gross profit | Note |
|---|---|---|---|
| Fuel | $11,867M | $1,208M | 43.8 cents a gallon on 2,761M gallons |
| Grocery & Merchandise | $3,296M | $914M | 27.7% gross margin |
| Foodservice | $646M | $323M | 50.0% gross margin |
| Other | $534M | $230M | Rent, commissions and services |
| Total | $16,343M | $2,675M |
Source: Cumberland Farms F-1/A, Results of Operations and key metrics, year ended December 31, 2025. "Other" description is our summary of the filing's revenue notes.
Fuel vs In-Store: Where the Gross Profit Comes From
Fuel was 72.6% of 2025 revenue on our arithmetic ($11.867 billion of $16.343 billion), but only 45.2% of gross profit ($1.208 billion of $2.675 billion). Inside sales are Grocery & Merchandise plus Foodservice. They brought in $3.942 billion of revenue and $1.237 billion of gross profit, a 31.4% margin, which is 46.2% of the total. The filing calls this a "balanced gross profit mix", and the numbers support the phrase. Foodservice is the high-margin piece: $646 million of revenue at a 50.0% gross margin.
Cumberland Farms FY2025: Share of Revenue vs Share of Gross Profit
Value Add VC arithmetic on the Cumberland Farms F-1/A, year ended Dec 31, 2025
Data
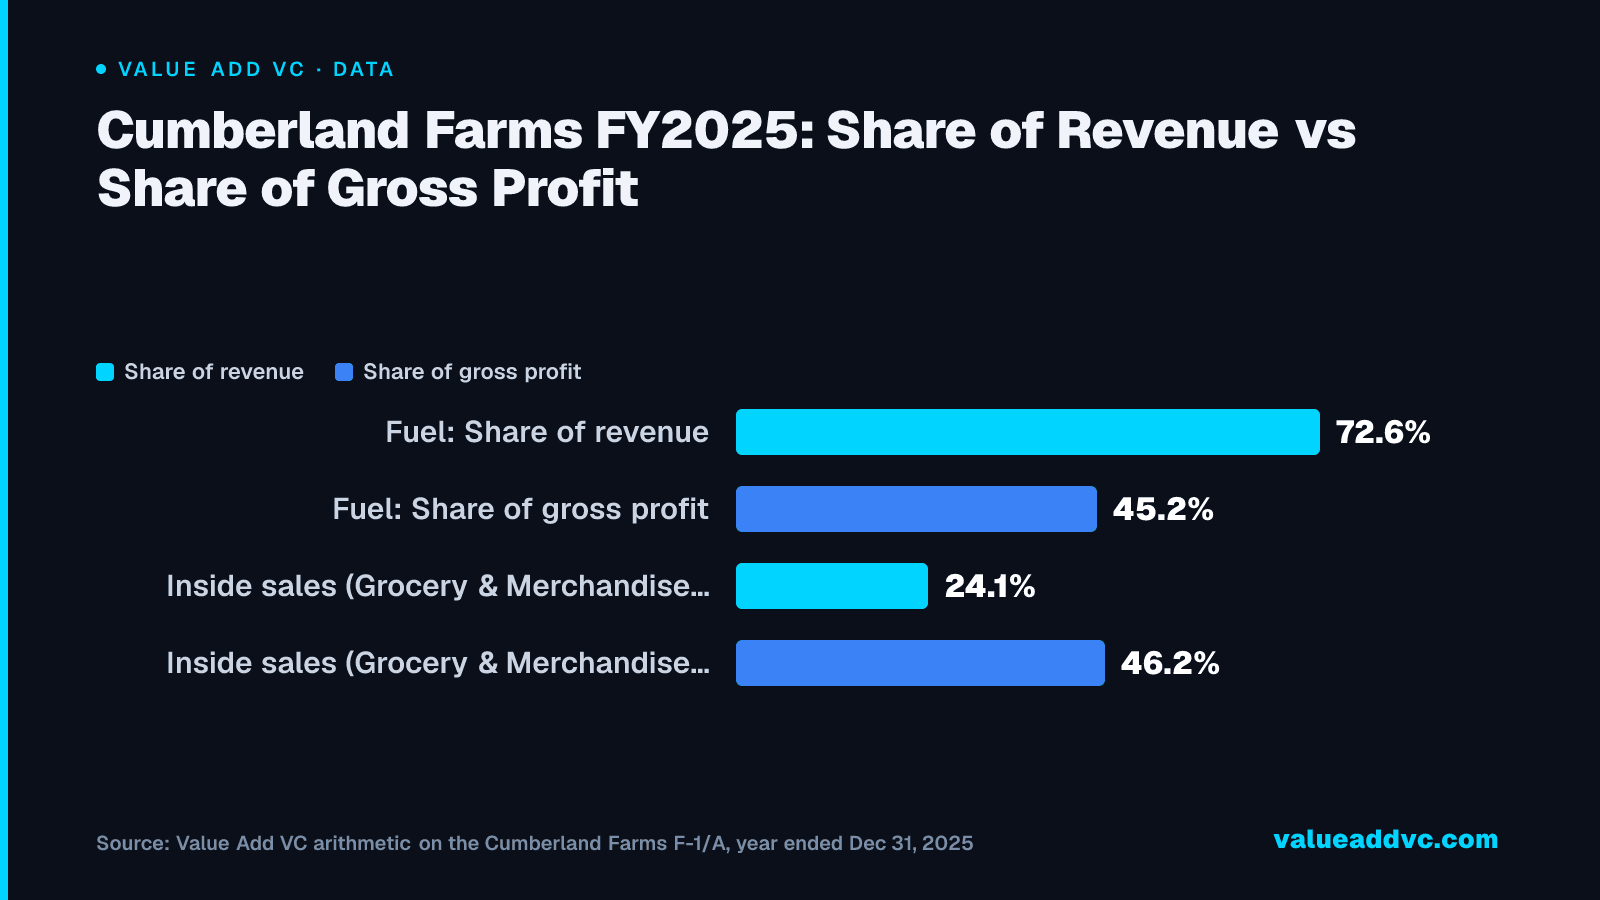
Fuel: $11,867M / $16,343M revenue and $1,208M / $2,675M gross profit. Inside: $3,942M / $16,343M and $1,237M / $2,675M. "Other" makes up the remainder.
Fuel volume is shrinking: 2.940 billion gallons in 2023, 2.837 billion in 2024 and 2.761 billion in 2025. In the six months to June 2026 volume fell again, to 1.307 billion gallons from 1.356 billion. Margin per gallon made up the difference. It jumped to 50.3 cents in the six months to June 2026 from 40.8 cents a year earlier, so fuel gross profit rose to $657 million from $553 million. Fuel margins depend on wholesale price swings, and the risk factors say they can reverse.
| Metric | FY2023 | FY2024 | FY2025 | H1 2026 |
|---|---|---|---|---|
| Sites (period end) | 3,402 | 3,262 | 3,246 | 3,313 |
| Fuel volume (M gallons) | 2,940 | 2,837 | 2,761 | 1,307 |
| Fuel margin (cents/gallon) | 42.9 | 44.1 | 43.8 | 50.3 |
| Fuel gross profit | $1,261M | $1,252M | $1,208M | $657M |
| Inside sales | $4,078M | $3,955M | $3,942M | $1,948M |
| Inside gross profit margin | 30.2% | 32.3% | 31.4% | 31.3% |
| Adjusted EBITDA (non-GAAP) | $682M | $731M | $693M | $352M |
| Interest expense | $853M | $773M | $668M | $287M |
| Pre-tax income (loss), continuing ops | $437M | $(239)M | $(205)M | $(205)M |
Source: Cumberland Farms F-1/A, key operating metrics, summary financial data and segment tables. H1 2026 is the six months ended June 30, 2026 (unaudited). Adjusted EBITDA is non-GAAP. Parentheses are losses.
The US business carries the in-store story. In the first half of 2026 the US segment earned $1.159 billion of Grocery & Merchandise revenue against Europe's $479 million, even though Europe sold more fuel ($4.080 billion against $2.661 billion). Most European convenience space is run with partners such as SPAR, REWE and Cactus. Food comes through brand deals with Burger King, KFC and Starbucks, the filing says.
The Debt: Why This IPO Exists
Debt is the main reason for this IPO. At June 30, 2026 the company had $5.822 billion of total debt, net of accrued interest and issuance costs, against $1.014 billion of cash, per the Capitalization table. Interest expense was $853 million in 2023, $773 million in 2024 and $668 million in 2025. In 2025 that was nearly as large as adjusted EBITDA of $693 million, and it is the main reason the company posted a $205 million pre-tax loss from continuing operations that year.
Cumberland Farms Debt at June 30, 2026 ($M)
Term loans are $4.6B of the $5.8B total
Cumberland Farms F-1/A, Capitalization (actual), SEC EDGAR, Sep 2026; carrying values net of costs
Data
| Item | Value |
|---|---|
| Term Loan Facilities | $4,575M |
| Senior Secured Notes | $709M |
| Floating Rate PIK Notes | $505M |
| Revolving Credit Facility | $33M |
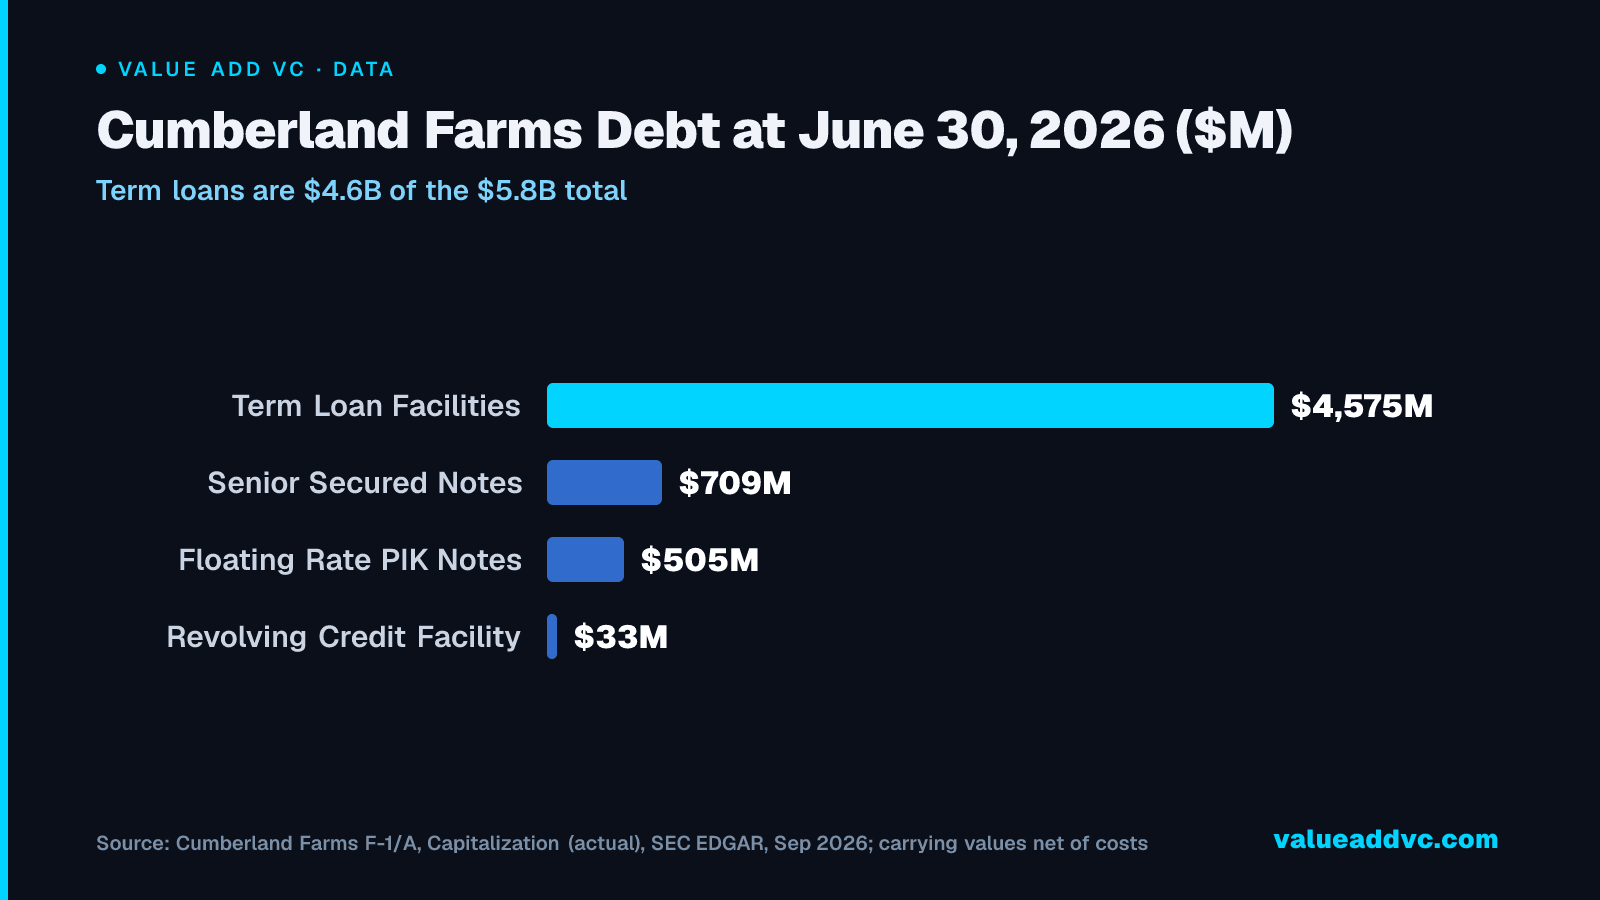
The F-1/A states the principal amounts. The New USD Term Loan had $2.307 billion outstanding at SOFR plus 3.25%. The New EUR Term Loan had $2.350 billion at EURIBOR plus 3.50%. Both mature in February 2031. The Floating Rate PIK Notes had $522 million outstanding at SOFR plus 7.50% and mature in 2028. The "as adjusted" column shows $771 million of Australian sale proceeds going to redeem the Senior Secured Notes in full, and $120 million of the French proceeds repaying part of the term loans.
The new money is also earmarked for debt. Net IPO proceeds, together with the Apollo placement described below, are to repay the term loans and the PIK notes, with anything left over for general corporate purposes. The dollar amounts in that section are blank, so how much leverage the IPO removes depends on a price that has not been set. For the mechanics of borrowing against a business, see our private credit vs venture debt explainer.
The Apollo $500 Million Convertible Preferred
The September amendment added a major new term. Funds managed or sub-advised by Apollo Global Management agreed to buy $500.0 million of Series A Convertible Preferred Shares in a private placement. The shares have a $10,000 stated value each and convert into ordinary shares at 115% of the IPO price. They pay a 6.75% cumulative dividend in cash, or 7.00% if paid in kind (allowed on up to eight payment dates). The rate rises by 1.00% if the shares are still outstanding after eight years.
The IPO and the placement are conditional on each other. Neither closes unless both do. The company can force conversion after the third anniversary and redeem after the eighth, subject to conditions. For IPO buyers this is a senior security that sits ahead of them for dividends and adds shares on conversion. The 115% conversion price means Apollo does best if the stock rises at least 15% above the offer. Our liquidation preference explainer covers how preferred terms like these stack against common stock.
Cumberland Farms Valuation: What Is Filed and What Is Reported
No valuation is in the filing. Without a price range or share count there is no implied market capitalization to calculate, and any "CMBY valuation" is a press figure. The July F-1 fee table used a $100 million maximum aggregate offering price, but that number exists only to calculate the SEC fee. Renaissance Capital's CMBY profile lists an estimated $1.0 billion deal size, with price and shares "n/a".
Two reported numbers bracket the value. Reuters reported that the company targeted about $9 billion for its US IPO. In October, Reuters reported (citing The Times) and The Telegraph reported (citing The Sunday Times) that Couche-Tard had proposed $7.5 billion to $8 billion. Neither company commented to those outlets, and Reuters reported that Cumberland Farms said it remained committed to a US listing. The Telegraph adds that Couche-Tard looked at the group in 2022 at a $16 billion valuation. Neither report says whether the $7.5 billion to $8 billion figure covers equity only or includes debt.
For scale, $8 billion is about 11.5 times 2025 adjusted EBITDA of $693 million (our arithmetic). That is a rough benchmark, not a multiple anyone has filed. If the reported figure is an equity value, the enterprise value would be higher by the net debt. Treat both reported numbers as unconfirmed until a price range appears in an SEC filing.
Cumberland Farms IPO Timeline
The timeline below gives each event with its date and source. The status as of November 13, 2026 is: filed, with no terms set, not priced and not trading.
| Date | Event | Source |
|---|---|---|
| 1939 | Cumberland Farms founded in Cumberland, Rhode Island | F-1/A, Business |
| 2001 | Zuber Issa buys a single site in Bury, England (Euro Garages) | F-1/A, Prospectus Summary |
| 2016 | TDR Capital's EFR combines with Euro Garages to form EG Group | F-1/A, Prospectus Summary |
| Oct 2019 | EG completes its acquisition of Cumberland Farms (about 570 sites) | F-1/A, Business |
| Mar 27, 2026 | Confidential draft registration (DRS) submitted | SEC EDGAR |
| Jun 23, 2026 | Registrant renamed Cumberland Farms Limited (from LuxBridge International) | F-1/A, About this prospectus |
| Jul 2, 2026 | Public F-1 filed; Nasdaq ticker CMBY | SEC EDGAR |
| Sep 4, 2026 | F-1/A filed; adds $500M Apollo convertible preferred; price range still blank | SEC EDGAR |
| Oct 24, 2026 | Reuters: IPO delayed; Couche-Tard proposes $7.5B-$8B, citing The Times | Reuters |
| Nov 13, 2026 | No newer amendment, no price range, not priced | SEC EDGAR filing index |
Sources: SEC EDGAR filing index, CIK 2123232; the F-1/A; Reuters, Oct 24, 2026. DRS/A drafts were also submitted on May 19 and June 15, 2026.
Leadership
Russ Colaco is chief executive officer and a director. He joined as chief financial officer in June 2024 and became CEO in April 2025, per the F-1/A. Mark Segal became CFO in July 2025. The filing says the US loyalty program grew quickly under the current team. Inside sales from loyalty members rose from about $36 million (15% of US segment inside sales) in June 2025 to $83 million (32%) in June 2026. Those are monthly figures, which the company reports itself.
What to Watch
A second F-1/A with a price range. That would be the earliest filed number that lets anyone compute a CMBY market value, and EDGAR will show it the day it lands.
The Couche-Tard approach. A signed sale would most likely end the IPO. A rejected bid could restart the roadshow. Watch for a registration withdrawal (Form RW) as the clearest signal.
Third-quarter 2026 numbers. The September amendment stops at June 30. A refreshed filing would have to add the nine-month figures, which would show whether the 50-cent fuel margin held.
Leverage after the Australian and French disposals. The as-adjusted column already counts the $771 million note redemption and the $120 million term-loan paydown, so any new amendment should show a smaller debt stack.
EG Group's retained stake. The F-1/A leaves EG's post-IPO voting percentage blank, so the free float is still unknown.
Bull Case and Bear Case
What's working
Gross profit is stable at about $2.7 billion a year while revenue falls, so the business earns money on margin rather than volume. Inside sales make up nearly half of gross profit, and foodservice earns about 50 cents of gross profit per dollar of sales. The company ranks #5 among US convenience operators by store count (NACS Top 100, as cited in the filing) and #4 in its European markets (Straits Research, as cited). First-half 2026 adjusted EBITDA was up 25% (our arithmetic: $352 million against $281 million).
What's hard
Gallons are falling every year, and the risk factors discuss electric vehicles and tobacco and vape restrictions in states such as New York, California and Massachusetts. Net income was negative in 2024 ($270 million loss) and 2025 ($145 million loss), and the six months to June 2026 lost $244 million. The 2023 profit of $1.880 billion included $1.550 billion from discontinued operations. After the IPO a controlling shareholder will still hold most of the votes, and a preferred security will sit ahead of common shareholders.
What the headline misses
"Cumberland Farms IPO" sounds like a New England chain going public. The filing is mostly something else. Europe produced more revenue than the United States in every year shown, and only 666 of the 3,313 sites carry the Cumberland Farms name. Buyers would be getting EG Group's US and continental European business under its strongest American brand.
Where This Sits in the 2026 IPO Market
Cumberland Farms is one of the larger consumer filings still waiting to price this year. Our 2026 IPO calendar tracks every major listing and who is still on file, and the 2026 IPO pipeline gives each company's current status. The live IPO tracker updates from EDGAR. For other consumer names that went from filing to listing, read our deep dives on Wella and Blue Lagoon. The IPO process explainer shows where a price range fits in the sequence, and the biggest IPOs of 2026 sets the size bar.
Honest Caveats
Every financial figure here is from the September 4, 2026 F-1/A. The six-month 2026 figures are unaudited, and the company may change any of them in a later amendment.
The $9 billion target and the $7.5 billion to $8 billion Couche-Tard figure are press reports (Reuters, The Times, The Telegraph and The Sunday Times). Neither appears in an SEC filing.
The TDR 50% and Issa 25% each ownership split is The Telegraph's reporting. The F-1/A names the principal shareholders without percentages.
Market-rank claims (#5 in the US, #4 in Europe) are the issuer's citations of NACS and Straits Research and have not been verified independently here.
The Bottom Line
The Cumberland Farms IPO is a debt-reduction listing for EG Group, sold under its best-known American brand. The F-1/A shows a business with $16.3 billion of revenue, $2.7 billion of steady gross profit split almost evenly between the pump and the store, and $5.8 billion of debt that has kept it in the red. It has filed, but it has not set terms or priced. The next real number will be either a price range or a takeover agreement, and the F-1/A cannot tell you which.
Figures are from Cumberland Farms Limited's SEC filings and the reporting linked above, as of November 13, 2026. Follow new listings on the IPO tracker and private rounds on the funding tracker, or download the free Startup Funding Dataset (CSV of sourced rounds and fund closes).
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗