
Big Tech AI Capex 2026: The Numbers by Company
| Company | 2025 Capex | 2026 Capex (Guided) | YoY Change |
|---|---|---|---|
| Amazon | $131.8B* | ~$220B | ~+67% |
| Microsoft | n/a (no calendar-2025 figure) | ~$170B | n/a |
| Alphabet (Google) | $91.4B* | $195–205B | ~+119% |
| Meta | $72.2B | $135–145B | ~+94% |
| Combined | — | ~$730B | — |
* Cash purchases of property and equipment (10-K); excludes finance leases, so not strictly comparable to 2026 guidance. Microsoft reports on a June fiscal year. Meta's 2025 figure includes finance leases. The 2025 bases are mixed, so no combined 2025 total or growth rate is shown.
Sources for 2026 guidance, as of October 29, 2026: Amazon's Q3 2026 release (~$220B of cash capex, reaffirmed), Reuters on Alphabet's Q3 2026 results ($195–205B, held), Microsoft's FY27 Q1 earnings call (~$170B for calendar 2026 including finance leases) and Meta's Q3 2026 release ($135–145B). Earlier context: CNBC on Alphabet's Q2 2026 capex raise and Fortune on Amazon's July raise to $220B. 2025 capex is each company's reported full-year actual (Amazon's FY2025 10-K, Microsoft's calendar-2025 quarterly capex including finance leases from its FY25 Q3, FY25 Q4, FY26 Q1, and FY26 Q2 earnings calls, Alphabet's FY2025 10-K, and Meta's Q4/FY2025 results), not earlier-year guidance. Amazon and Microsoft figures are total company capex. Microsoft's 2026 figure was trimmed to ~$170B on October 28 because third-party capacity deliveries slipped, not because it is building less. 2026 figures are each company's latest full-year guidance from its Q3 2026 release or call, and the same figure set is used on our AI Spending Tracker; quarterly actuals are tracked on the dashboards linked below. Goldman Sachs projects combined capex nearing $1.14 trillion in 2027.
Updated Nov 4, 2026: all four companies have now reported Q3 2026. Amazon and Alphabet held their 2026 guidance, Meta narrowed to $135–145B, and Microsoft trimmed calendar-2026 spend to about $170B on delayed third-party capacity, which leaves the combined total at roughly $730B ($720–740B).
Amazon (~$220B), Alphabet ($195–205B), Meta ($135–145B), and Microsoft (~$170B) are guiding to a combined ~$730B of 2026 capital expenditure, most of it AI infrastructure, a buildout scale with no real precedent in enterprise technology spending — and Goldman Sachs projects the combined number nearing $1.14 trillion in 2027.
This is not defensive spending or R&D hedging. Every dollar is tied to a specific bet: that AI compute will be the scarce resource that determines who wins cloud, enterprise software, and consumer products for the next decade.
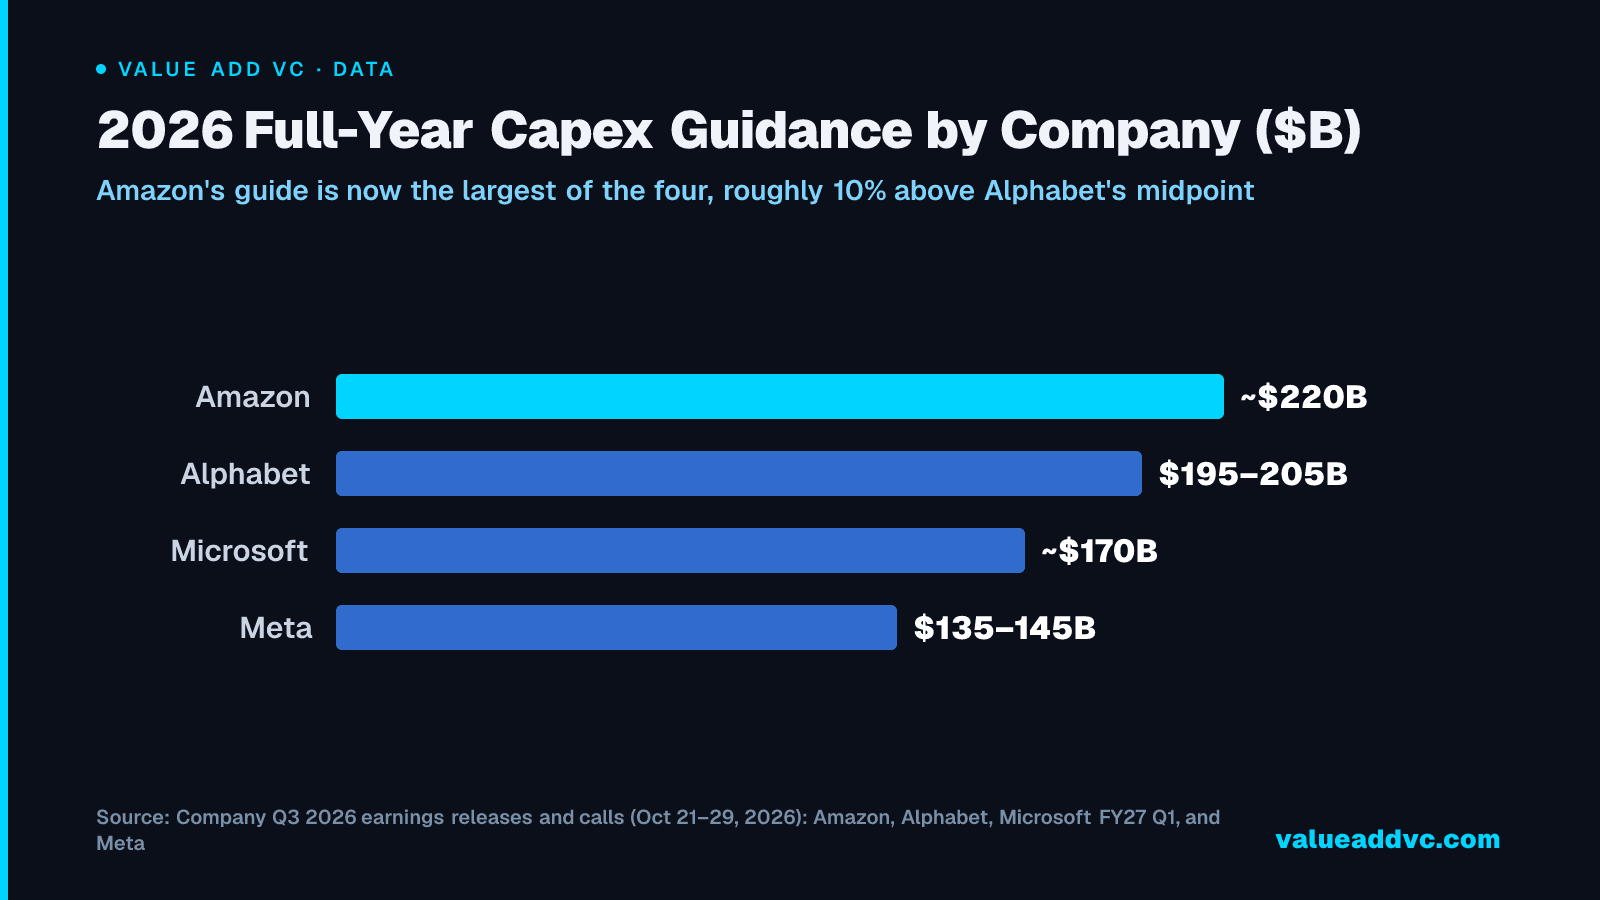
2026 Full-Year Capex Guidance by Company ($B)
Amazon's guide is now the largest of the four, roughly 10% above Alphabet's midpoint
Company Q3 2026 earnings releases and calls (Oct 21–29, 2026): Amazon, Alphabet, Microsoft FY27 Q1, and Meta
Data
| Item | Value |
|---|---|
| Amazon | ~$220B |
| Alphabet | $195–205B |
| Microsoft | ~$170B |
| Meta | $135–145B |
What Each Company Is Actually Buying
Microsoft (~$170B)
- →GPU clusters powering Azure OpenAI Service — running GPT-4, o3, and next-gen models at enterprise scale (see our full Microsoft AI capex breakdown)
- →Calendar-2026 capex of about $170 billion including finance leases, CFO Amy Hood said on the FY27 Q1 earnings call (Oct 28, 2026), after $45.2 billion in the September quarter; roughly three quarters went to short-lived assets, mainly CPUs and GPUs, and Azure revenue grew 48%
- →As of April 2026, Microsoft's AI business had crossed a $37 billion annualized revenue run-rate, up 123% year-over-year — the first update to that figure since the $13 billion mark disclosed in January 2025, per Microsoft's own Q3 FY2026 results
- →Global data center expansion: 100+ new facilities announced across US, Europe, Middle East, and Asia
- →Custom silicon research (MAIA chips) to reduce Nvidia dependency and lower per-token inference cost
- →Copilot infrastructure: every Microsoft 365 user generating AI requests requires dedicated inference capacity
Alphabet ($195–205B)
- →TPU v5 and v6 clusters — Google's custom AI accelerators now power Gemini and Google Cloud AI services (see our Alphabet $205B capex deep dive)
- →Google Cloud revenue more than doubled to $30.7 billion in Q3 2026 (up 103%), after $24.8 billion in Q2, per Alphabet's Q3 2026 release; Q3 capex was $51.4 billion
- →Search AI integration: Google must serve AI Overviews at query scale without margin collapse
- →Waymo compute: autonomous vehicle training requires continuous large-scale simulation workloads
- →DeepMind research infrastructure for AlphaFold successors and scientific AI programs
Meta ($135–145B)
- →MTIA (Meta Training and Inference Accelerator) — proprietary chip to eventually replace Nvidia GPUs for ranking and recommendations (see our Meta $145B capex breakdown)
- →Llama training runs: each Llama generation required clusters of 100,000+ H100s; Llama 5 will require more
- →Meta AI assistant infrastructure: serving 3B+ users across WhatsApp, Instagram, and Facebook
- →Reality Labs compute: VR/AR environments require real-time AI rendering at device edge
Amazon (~$220B)
- →AWS data center expansion to serve Bedrock (enterprise AI), SageMaker, and direct GPU rental (P5 instances)
- →AWS revenue grew 39% to $46.0 billion in Q3 2026, its fastest growth in nearly five years and a $184 billion annualized run rate, per Amazon's Q3 2026 release, after $42.2 billion in Q2
- →Trainium2 and Inferentia chips — Amazon's custom silicon now handles significant internal ML workloads
- →Alexa+ rebuild: Amazon is rebuilding Alexa on a foundation model stack requiring substantial inference capacity
- →Anthropic partnership infrastructure: AWS is Anthropic's primary training cloud, requiring dedicated capacity commitments
Where the Money Actually Goes: Five Spend Categories
Most coverage frames hyperscaler capex as "buying Nvidia GPUs." That is accurate but incomplete. A typical AI infrastructure build breaks down across five categories:
GPU Clusters (40–50% of spend)
Nvidia H100, H200, and Blackwell GB200 NVL systems. At ~$30K–$40K per H100 and $60K–$70K per GB200, even modest cluster sizes cost billions.
Data Center Construction (25–35%)
New builds in Virginia, Texas, Iowa, and internationally. Google is building or expanding in 12 countries. Meta broke ground on a 2GW+ facility in Louisiana. Lead times for purpose-built AI data centers now run 18–24 months.
Networking Infrastructure (10–15%)
InfiniBand and high-speed Ethernet to connect GPU clusters at scale. Nvidia's networking division (formerly Mellanox) is a major beneficiary, alongside Arista Networks and Juniper.
Power & Cooling (10–15%)
A single modern GPU cluster consuming 100MW+ needs purpose-built power delivery and cooling. Companies are signing direct power purchase agreements with utilities and nuclear operators — Microsoft signed a deal to restart Three Mile Island.
Custom Silicon Development (5–10%)
Google's TPUs, Amazon's Trainium2, Meta's MTIA, and Microsoft's MAIA reduce Nvidia dependence over time. These are multi-year bets costing $2–5B per generation but pay off at hyperscaler scale.
Why the Microsoft, Google, Meta, Amazon AI Capex Race Keeps Escalating
Three structural forces prevent any company from pulling back unilaterally:
Training cost scaling
Each frontier model generation requires 10–100x more compute than the last. Skipping a training cycle means falling behind on capabilities that are now core to product differentiation.
Inference demand explosion
Deployed AI products — Copilot, Gemini, Meta AI — generate billions of queries per day. Inference at this scale requires more compute than training. Under-provisioning means slower responses and higher per-query costs.
Custom silicon race
Every company paying Nvidia $30,000–$40,000 per H100 is motivated to develop proprietary chips. But building silicon takes 3–5 years and billions in R&D — so capex now buys strategic independence later.
Nvidia Is the Real Beneficiary — For Now
Nvidia's data center revenue grew from $15B in FY2023 to $115B in FY2025 — largely on the back of hyperscaler capex (see our Nvidia valuation analysis). The most recent print, for fiscal Q2 2027 (the quarter ended July 26, 2026), shows data center revenue of $89.0B — up 117% year-over-year — as Nvidia's own results release (also filed with the SEC as an 8-K exhibit) credits the ramp of Blackwell Ultra systems, with the four major hyperscalers accounting for an estimated 40–50% of total GPU purchases.
But every dollar Microsoft spends on MAIA, Meta spends on MTIA, Google spends on TPUs, and Amazon spends on Trainium is a dollar that will eventually stop flowing to Nvidia. The custom silicon programs are 3–5 year bets, not current-quarter disruptions. For now, Nvidia captures the capex cycle. The question is whether its moat survives the transition to proprietary silicon at scale. It's also worth asking how much of Meta's own top line is actually attributable to AI versus the core ad business it's layered on top of.
Track the real-time data on our Big Tech Earnings Dashboard and AI Spending Tracker.
The Second-Order Effects Nobody Talks About
When four companies simultaneously ramp capex by roughly 50–120% in a single year, the ripple effects extend well beyond the AI industry:
Power Grid Stress
The US electric grid was not designed for 100MW+ data center clusters. Dominion Energy has 30GW of data center capacity in the queue in northern Virginia alone — more than the state's entire current generating capacity. Big tech is now signing deals with <a href='/blog/nuclear-power-and-ai-why-big-tech-is-signing-deals-with-uranium-producers' class='text-[#00d4ff] hover:underline'>nuclear power providers</a> to secure supply.
Real Estate Markets
Data center REITs Equinix and Digital Realty have seen demand outpace supply in every major market. Land adjacent to power substations in rural Virginia, Iowa, and Texas has appreciated 300–500% since 2023. See our deep dive on <a href='/blog/ai-data-center-real-estate-the-geography-of-where-ai-infrastructure-is-being-built' class='text-[#00d4ff] hover:underline'>AI data center real estate</a>.
Construction Labor
Hyperscaler data center builds are competing with semiconductor fab construction (TSMC Arizona, Intel Ohio) and clean energy projects for the same pool of specialized electrical engineers and construction workers.
Inference Cost Compression
As GPU supply scales, inference costs continue to fall — the cost to run GPT-4 class inference dropped approximately 95% between 2023 and 2025. This is deflationary for AI infrastructure startups but highly beneficial for application-layer companies.
AI-infrastructure capital is also reaching raw materials: Mariana Minerals raised a $310 million Series B led by Khosla Ventures at a $1.5 billion valuation to run what it calls the world's first fully autonomous copper mine, in Utah (Mariana Minerals round breakdown).
What This Means for Startups Building on AI
Tailwinds
- ✓ API costs continue falling as hyperscalers over-provision capacity
- ✓ More capable foundation models available at every price point
- ✓ Hyperscalers incentivized to court AI startups as platform anchors
- ✓ Enterprise buyers getting comfortable with AI procurement cycles
Headwinds
- ✕ Hyperscalers building native AI features into core products (vertical integration threat)
- ✕ Commodity AI becoming a checkbox feature, not a moat
- ✕ Enterprise buyers defaulting to hyperscaler AI to simplify procurement
- ✕ Custom silicon reduces third-party GPU availability during training windows
Five Signals That Would Mark the Cycle Peak
The race is self-reinforcing — each company fears falling behind if it blinks while the others accelerate. A plateau is more likely than a crash, and these are the signals to watch:
GPU lead times normalize from 12+ months to under 6 months — indicating supply has caught up to demand
Any of the four companies guides capex down year-over-year for the first time since 2022
Enterprise AI adoption metrics (daily active AI users per Fortune 500) plateau below model provider revenue projections
Nvidia's data center revenue growth decelerates below 20% year-over-year for two consecutive quarters
Power purchase agreement prices in key markets decline, signaling a data center build slowdown
As of November 4, 2026, signal 2 has not fired: none of the four guided 2026 capex below 2025. Microsoft did trim its calendar-2026 figure to about $170 billion on October 28, but it blamed delayed third-party capacity deliveries, not weaker demand, and guided to more than $50 billion for the December quarter. Amazon and Alphabet held their 2026 guidance with Q3 results, Meta narrowed its range upward, and Alphabet said 2027 capex will rise significantly. The signal now worth watching instead is financing, not demand — see below.
What's New Since August 2026: Capex Is Starting to Outrun Cash Flow
The headline capex numbers above were set or reaffirmed in late July 2026 and, apart from Microsoft's trim to about $170 billion, held on the late-October Q3 calls, but the more consequential shift since this post was last checked, on August 20, 2026, is how that spending is being funded. Alphabet's $44.92 billion in Q2 2026 capital expenditure exceeded its $39.07 billion in operating cash flow, pushing quarterly free cash flow to negative $5.86 billion — the first negative quarter the company has disclosed since Google went public in 2004, according to Goldman Sachs' analysis reported by Yahoo Finance in September 2026.
That same Goldman Sachs research, published in September 2026, projects hyperscalers will fund more than a third of their roughly $1.14 trillion in 2027 capital expenditure with investment-grade bond issuance — up from about 26% of capex in 2025 and roughly 33% through the first half of 2026 alone. Separately, The Motley Fool reported on September 6, 2026 that S&P Global's own model puts six major hyperscalers at a combined $1.3 trillion in 2027 capex, with only one of the six projected to still generate positive free cash flow that year.
The third quarter added to that picture. Alphabet's free cash flow was negative again, at $9.1 billion, on $51.4 billion of Q3 capex, per its Q3 2026 release, and Amazon's trailing-twelve-month free cash flow turned into a $42.4 billion outflow, driven by a $94.8 billion year-over-year increase in property and equipment purchases, per Amazon's Q3 2026 release.
This likely means the AI capex race is entering a second phase: the constraint is shifting from "can these companies afford to build" to "how much of the build gets financed with debt rather than cash." That is a meaningfully different risk profile for anyone modeling hyperscaler balance sheets into 2027 — and a reason Alphabet's stock still fell after beating Q2 2026 estimates, per CNBC's coverage of the earnings reaction.
What the Headline Misses: The Bubble Critique From Burry, PIMCO, and Bain
Three independent warnings, from an investor, a bond manager, and a consultancy, converge on the same underlying worry: that the $730B headline overstates how healthy this spending actually is. In a November 2025 analysis reported by CNBC, "Big Short" investor Michael Burry argued that hyperscalers extending the useful life of GPU-heavy servers artificially understates depreciation and inflates earnings. Burry estimated the industry-wide understatement at roughly $176 billion between 2026 and 2028, and singled out Oracle and Meta, projecting their reported profits could be overstated by about 27% and 21%, respectively, by 2028. Nvidia and CoreWeave have pushed back, arguing older GPUs still command strong rental rates years after launch.
Credit markets are flagging a related risk. In a May 2026 credit note, PIMCO estimated that AI capex will absorb about 94% of hyperscaler operating cash flow in 2026–2027, up from just 40% in 2023, and tracked roughly $136 billion of new investment-grade debt issued by hyperscalers in the year to date — consistent with Goldman Sachs' separate projection above that more than a third of 2027 capex gets funded with bonds. PIMCO's own language is blunt: the buildout carries "genuine risks: uncertain monetization, potential overbuild, shortening asset lives, and growing reliance on debt," even as the firm argues it is still more disciplined than the late-1990s telecom bust.
And on monetization specifically, Bain & Company's sixth annual Global Technology Report — covered by Bloomberg — put a number on the gap this spending has to close: AI companies need roughly $2 trillion in annual revenue by 2030 to pay for the compute being built, and Bain projects they will fall about $800 billion short on current trends, because usage is scaling faster than what customers are willing to pay per query. Put together, the counterweight to every guidance raise in this post is the same: more capex either needs more revenue or more debt, and right now it is increasingly funded by the latter.
~$730B in 2026. ~$1.14T in 2027.
The startups that win are not competing with this spending. They are making it more productive.
Explore Related Dashboards
Interactive tools with live data on this topic
Track hyperscaler earnings and AI infrastructure trends on the Big Tech Earnings Dashboard and the AI Chip Wars Dashboard at Value Add VC. See also: Big Tech Earnings Q1 2026 Results. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗