
Mariana Minerals just raised $310 million at a $1.5 billion valuation — up from a reported but unconfirmed $775 million at its July 2025 Series A. The pitch isn't another app. It's a copper mine in the Utah desert, run almost entirely by software and robots.
The round, announced August 3, 2026 and led by Khosla Ventures, is the latest sign that venture capital has stopped treating physical, capital-intensive infrastructure as the boring alternative to software. It's becoming the thesis.
Mariana Minerals Valuation: What the $310M Series B and $1.5B Price Tag Actually Buy
Mariana Minerals is a San Francisco-based, software-first mining company that raised $310 million in Series B funding on August 3, 2026, led by Khosla Ventures at a $1.5 billion valuation, per Fortune. A roughly $775 million valuation at its July 2025 Series A has been reported, but we could not confirm it from a primary source. The round brings Mariana's total capital raised to approximately $400 million, including project capital.
Figures from Mariana Minerals' Series B announcement (PR Newswire, Aug 3, 2026), Fortune, and company disclosures as of August 2026.
Who's Behind the Round
Khosla Ventures led the Series B, per the company's PR Newswire release, with continued backing from Andreessen Horowitz and Breakthrough Energy Ventures — both of which had already backed Mariana's July 2025 Series A alongside Khosla. New participants this round include Greenoaks, BHP Ventures (the mining giant's venture arm), Mitsubishi Corporation, In-Q-Tel (the CIA's venture fund), StepStone Group, Washington Harbour Partners, Greycroft, Pax Ventures, Halo Fund, General Innovation Capital Partners, and Earthshot Ventures. That mix — a mining major's strategic arm, an intelligence-community fund, and traditional growth investors all in the same round — mirrors a pattern showing up across 2026's defense- and infrastructure-tech deals: institutional and strategic capital arriving well before any of these companies would traditionally have gone public or been acquired.
Why a Mining Giant and the CIA's Venture Fund Are in the Same Cap Table
BHP Ventures and In-Q-Tel aren't typical Series B names, and neither is participating for the same reason a growth-equity fund would. BHP — one of the world's largest mining companies — gets a strategic look at whether an AI-first operating model can be bolted onto assets it already owns or is evaluating, without having to build the software itself. In-Q-Tel, which invests on behalf of US intelligence agencies, has a mandate tied directly to reducing American dependence on foreign-controlled critical-minerals supply chains; the IEA's July 2026 Critical Minerals Outlook puts China's share of rare-earth refining at about 85% in 2025, down from 90% in 2023 (as reported by Reuters), and Washington has treated that concentration as a national-security exposure since at least the 2025 round of export-control disputes. Mitsubishi Corporation's involvement points the same direction — a trading house with existing metals offtake relationships betting it can route Mariana's output into contracts it already has in place. None of these three needed to write a venture check to get exposure to copper; they wrote one anyway because Mariana is selling software-driven speed, not just tonnage.
Mariana Minerals' Valuation, Series A to Series B ($B)
Series B: Fortune and PR Newswire, August 2026. The $0.775B Series A valuation is a reported figure we could not confirm from a primary source.
Data
| Item | Value |
|---|---|
| Series A (Jul 2025) | $0.775B |
| Series B (Aug 2026) | $1.5B |
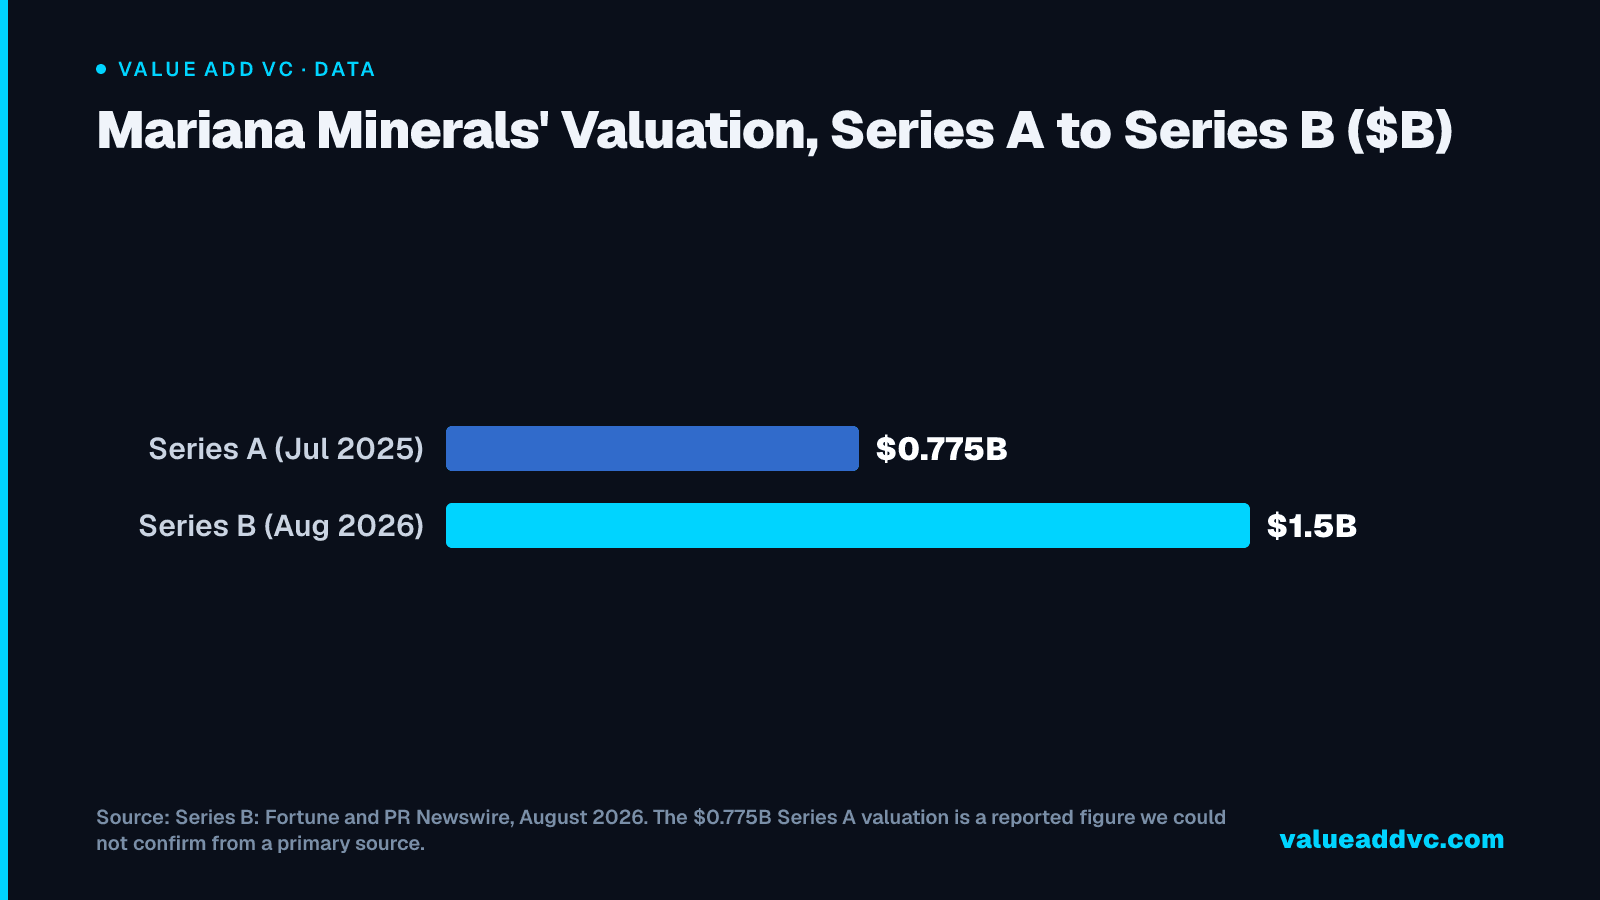
If the reported Series A mark is right, the valuation roughly doubled in 13 months — a step-up rate closer to what late-stage AI labs command than what mining companies have historically seen.
What Mariana Minerals Actually Builds
Mariana engineers, builds, and operates mines and refineries using MarianaOS, a proprietary software stack that fuses three subsystems — MineOS, PlantOS, and CapitalProjectOS — into a single platform spanning site discovery through refined-metal output. The company's argument, echoed in a16z's investment memo, is that the bottleneck in expanding US minerals production isn't geology — it's coordination: most mining operators still run on spreadsheets and static mine plans, making decisions long after the underlying data was current.
The three subsystems split cleanly by phase of a project's life. CapitalProjectOS manages permitting, engineering, and construction sequencing for a new site — the phase that traditionally takes a mining company five to ten years before it produces a single ton of ore. MineOS coordinates extraction once a site is live, scheduling autonomous drills and haul trucks in real time rather than against a static weekly plan. PlantOS runs the refinery side, tuning processing parameters against live ore-grade and throughput data instead of the periodic manual checks legacy refiners rely on. Mariana's argument, and the one Khosla and a16z are underwriting at a $1.5 billion price, is that running all three off one data layer compresses that traditional five-to-ten-year timeline by roughly half.
Its flagship site, Copper One in remote southeastern Utah, was acquired in late 2025 and restarted mining operations under autonomous orchestration — automated drills, driverless robotic haul trucks, and Boston Dynamics Spot robots handling thermal inspection in areas too hazardous for routine human access — within four months, an unusually fast restart timeline for a site legacy operators had written off. Mariana is targeting about 50,000 metric tons of refined copper a year out of Copper One by 2030, per the Salt Lake Tribune. A second site, Lithium One, broke ground in East Texas in Q4 2025 as what the company calls the world's first GWh-scale facility for producing lithium from oil and gas produced water, with commercial production targeted for the first half of 2027, per the company release. Mariana has said it is aiming for 10 commercial-scale projects in 10 years — with each new site meant to train the MarianaOS software on a slightly different geology than the last.
Why Copper, and Why Now
Copper is having its own version of the AI supply-chain crunch that's already hit GPUs and grid power. The International Copper Study Group projected in its October 2025 forecast that the global refined copper market would flip from a 178,000-tonne surplus in 2025 to a 150,000-tonne deficit in 2026, as mine-production growth was forecast at roughly 2.3% while refined output growth falls to under 1%. Mine disruptions in Indonesia, Chile, and Congo have compounded the shift. On the demand side, AI data centers are a growing source of copper demand. Copper prices hit record highs at the start of the year, briefly surpassing $14,500 per tonne in January, per J.P. Morgan.
That backdrop is exactly what Mariana's pitch to investors leans on: a mine that would have taken a legacy operator years to permit and restart, brought back online in four months, aimed directly at the metal an AI buildout that's already soaking up hundreds of billions in hyperscaler capex actually needs more of. For the wider buildout behind that demand, see our look at the $1 trillion AI infrastructure build in data centers, power and cooling.
Global Refined Copper Market Balance: 2025 Surplus to 2026 Deficit (thousand tonnes)
The market swings from a 178,000-tonne surplus to a 150,000-tonne deficit in a single year
International Copper Study Group (icsg.org), October 2025 forecast. ICSG published a newer 2026-2027 forecast on October 14, 2026.
Data
| Item | Market balance (thousand tonnes) |
|---|---|
| 2025 | 178 |
| 2026F | -150 |
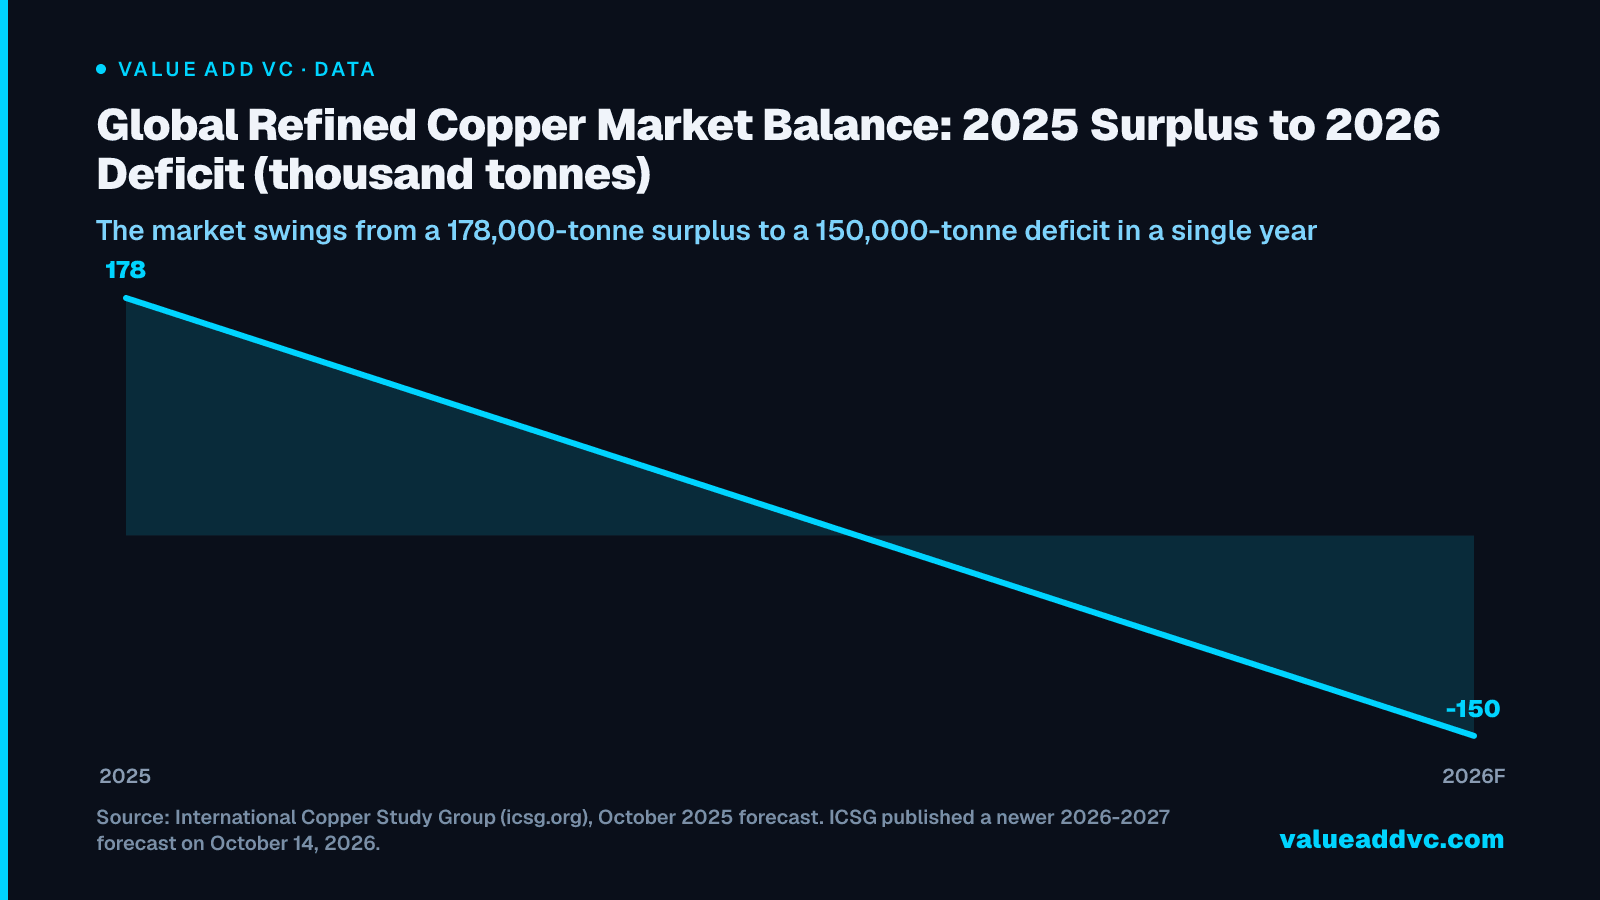
A positive number is a surplus; a negative number is a deficit. The ICSG attributes the swing to mine-production growth slowing to roughly 2.3% in 2026 while refined-output growth falls under 1%, compounded by disruptions in Indonesia, Chile, and Congo.
It's worth being precise about what that deficit number does and doesn't mean for Mariana specifically. A 150,000-tonne global shortfall doesn't guarantee any single new producer a buyer at a premium price — copper is a fungible, globally traded commodity, and Mariana's 50,000-ton Copper One target would only close a third of the projected gap on its own, assuming every ton it produces goes toward the deficit rather than simply replacing output lost elsewhere. What the deficit does support is the price floor: as long as global refined supply keeps lagging demand, a new domestic producer with a four-month restart timeline is unusually well-positioned to sell into that gap rather than compete on cost with mines that have decades of sunk infrastructure.
Mariana in Context: Physical-AI Infrastructure Deals in 2026
| Company | What it builds | Latest valuation | Key backers |
|---|---|---|---|
| Mariana Minerals | AI-run copper and lithium mines/refineries | $1.5B (Aug 2026) | Khosla, a16z, Breakthrough Energy, BHP Ventures |
| Hadrian | Automated factories for aerospace/defense parts | $7.87B (Aug 2026) | JPMorgan SIG, a16z, Founders Fund, Valor |
| Valar Atomics | Small modular nuclear reactors for AI data centers | $6B (Aug 2026, reported) | Sequoia, Atreides, Point72 |
| Firmus Grid | AI data center buildout, Asia-Pacific | $10.5B+ (Aug 2026) | Nvidia, Coatue, Blackstone |
Hadrian: Bloomberg Law. Valar: The Next Web (Valar did not disclose the valuation itself). Firmus: Firmus release, which states a post-money valuation above $10.5 billion. Valuations for private companies reflect last disclosed priced rounds.
The pattern across all four: capital that used to wait for a Series C or a public listing is now showing up at Series B, for companies whose product is a physical asset — a mine, a reactor, a factory, a battery plant — rather than a piece of software. Mariana is the smallest of the group by valuation, but it's arguably the most direct commodity play: it doesn't need AI demand to keep growing in any specific direction, it just needs the world to keep needing copper, which was true before this AI cycle and will be true after it.
What the "AI mining" framing misses
Mariana's automation claims — company projections of roughly 50% lower mining costs and 30% lower refining costs versus legacy operators — come from the company itself, we could not retrieve a primary document stating them, and haven't been independently audited at scale; Copper One has been running under autonomous orchestration for well under a year, which is a short track record to extrapolate a permanent cost advantage from. Mining is also a business where execution risk shows up years after the funding announcement: permitting delays, ore-grade surprises, and community or environmental opposition have killed better-funded projects than this one, and Mariana's 10-projects-in-10-years plan requires repeating its Copper One playbook across sites with different geology, regulators, and local politics every single time.
There's also a simpler read worth sitting with: a $1.5 billion valuation for a company with two project sites and, per the Salt Lake Tribune, about 80 employees at the April 2026 restart is a bet on execution speed that hasn't been tested through a full commodity-price downturn. Copper near its January record above $14,500 a tonne makes Mariana's unit economics look good today; copper back at 2023 levels, when the LME price averaged about $8,478 a tonne, would test whether the AI-driven cost advantage is real or whether it was subsidized by a favorable price environment.
One likely read on the timing: Mariana closed this round while copper is near an all-time high and before any competing "AI-native miner" has a comparable operating site to point to, which is exactly when a founder with a credible operating story gets priced generously. That's not a knock on the business — Caldwell's Tesla background and Copper One's four-month restart are real, verifiable proof points, rarer than most Series B pitch decks offer. But it does mean the $1.5 billion mark reflects a moment in the commodity cycle as much as it reflects Mariana's software specifically, and investors underwriting the next round should expect the multiple to compress if copper prices normalize before Mariana's second and third sites reach full production.
The Bottom Line
Mariana Minerals' $310 million Series B at a $1.5 billion valuation is a small round by 2026's AI-infrastructure standards, but it's a clean data point on where venture capital is willing to underwrite physical, multi-year builds: a mine that restarted under autonomous control in four months, chasing a copper deficit that AI data centers are making structurally worse. Turner Caldwell, who led Tesla's metals and minerals team, has gone on to run his own mine in under two years — and if Copper One hits its 50,000-ton target while the ICSG's projected deficit holds, Mariana will have proven a model other critical-minerals sites can copy. If it doesn't, this becomes a case study in how fast "AI-run" framing can attract capital to a business that still has to survive ordinary mining risk.
Track physical-AI and infrastructure funding rounds at Value Add VC. Reach out at t@nyvp.com or @Trace_Cohen.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗