
$325,000 to $425,000 is what a private equity associate earns in year-one cash compensation at a $10B+ fund in 2025, against $120,000 to $180,000 for a venture capital associate. The pay gap is real and it widens every level up — but money isn't the sole factor that should decide which seat you take.
Both careers sit inside private capital, both use a 2-and-20 fee-and-carry structure, and both get pitched to the same pool of banking analysts and MBA students every recruiting cycle. Past that, they diverge: different hours, different deal pace, different recruiting pipelines, and a very different relationship between what you do day to day and how large the checks eventually get.
PE and VC associate pay: Mergers & Inquisitions and the Gannon/Venture5 2025 VC Salary Survey (700+ respondents, 50+ firms). AUM: NVCA 2025 Yearbook. Holding period: Bain & Company, Global Private Equity Report 2026.
Venture Capital vs Private Equity Career Path: Which One Pays More in 2026?
Private equity pays more in cash at every career stage, with the gap widening from roughly 2x at the associate level to 10x-plus by partner, because buyout deals are typically far larger than venture checks under the same 20% carry structure. Venture's edge is hours and earlier exposure to building, not restructuring, a company.
| Attribute | Venture Capital | Private Equity |
|---|---|---|
| Associate total cash comp (2025) | $120K-$180K | $250K-$425K by fund size |
| Typical recruiting path | Banking, consulting, operators, founders | ~90% from 2-year IB analyst programs |
| Hours per week (baseline) | 50-60, up to 60-70 in peak periods | 60-80, up to 100 during live deals |
| Primary skill tested | Judging people and markets under uncertainty | LBO modeling and operational diligence |
| Typical deal/check size | $500K-$50M+ per round | $50M-$1B+ per buyout |
| Carry structure | 20% of fund profits, ~8% hurdle (typical) | 20% of fund profits, ~8% hurdle (typical) |
| Fund hold period | ~10-year fund life, company exits vary widely | ~7-year average holding period at exit (2025) |
| US industry AUM | $1.25T (NVCA, 2025) | $3.13T (S&P Global, Sept. 2024) |
Comp and recruiting: Gannon/Venture5 2025 VC Salary Survey; Mergers & Inquisitions private equity salary data. AUM: NVCA 2025 Yearbook; S&P Global Market Intelligence. Hold period: Bain & Company, Global Private Equity Report 2026. Deal and check sizes are typical ranges, not fixed figures.
Total Cash Comp by Career Level: VC vs PE
Gannon/Venture5 2025 VC Salary Survey; Mergers & Inquisitions and Wall Street Oasis private equity compensation data, 2025-2026.
Data
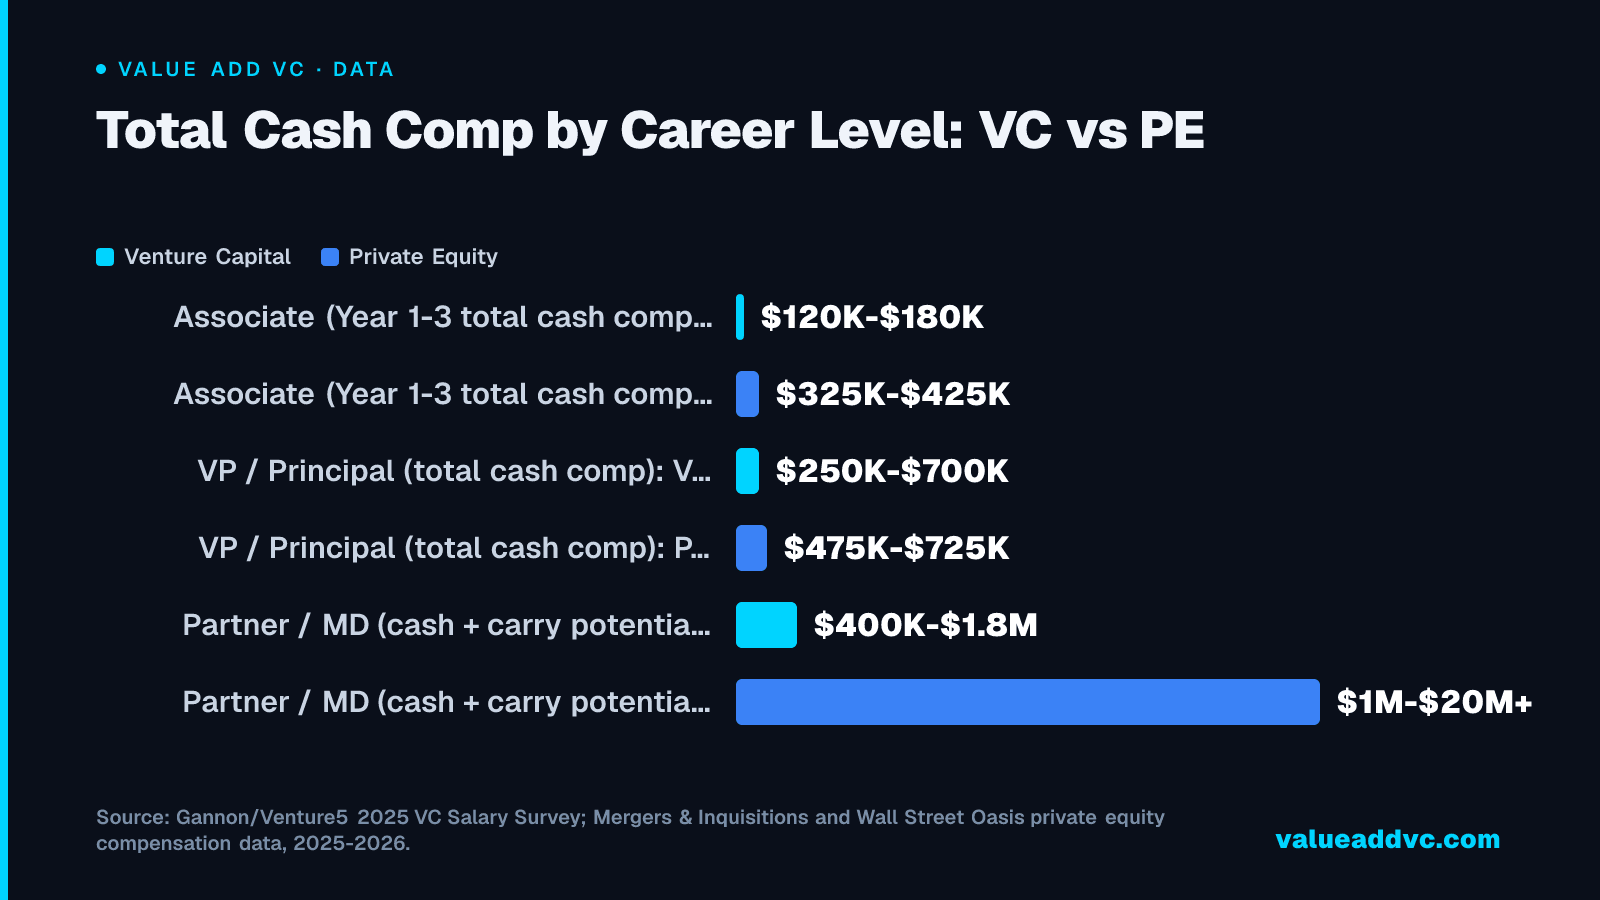
The gap starts around 2x at the associate level and stretches past 10x by partner/MD, because PE carry is earned on buyout deals an order of magnitude larger than most venture checks.
What Private Equity Pays More For
Private equity's cash-comp edge isn't just a bigger bonus — it's a more standardized, higher-stakes recruiting funnel. Most mega-fund and large-fund associates come out of a two-year investment-banking analyst program and get hired through "on-cycle" recruiting that can start within weeks of beginning that banking job, according to compensation and recruiting data compiled by Mergers & Inquisitions. That pipeline is why PE pay compresses less by fund size than VC pay does: a mega-fund ($10B+ AUM) associate earns $325,000-$425,000 in year-one cash, a large fund ($1B-$10B) associate earns $275,000-$375,000, and a middle-market fund ($250M-$1B) associate earns $250,000-$340,000 — a narrower spread than venture's swing from roughly $120,000 at a $75M fund to $200,000-plus at a $500M+ fund.
Clearer promotion ladder
On-cycle recruiting and standardized 2-3 year associate stints make the next rung predictable
Carry on much bigger deals
20% carry on a $500M buyout dwarfs 20% carry on a $20M venture check
Senior comp that compounds fast
MDs/partners can clear $1M-$20M+ once carry vests, per industry comp surveys
A single well-worn entry door
Roughly 90% of associates arrive from a 2-year banking analyst program
What Venture Capital Gives You That PE Doesn't
Venture capital's case isn't cash — it's time and texture. VC associates typically work 50-60 hours a week, rising to 60-70 during fundraising or board-heavy stretches, versus a PE baseline of 60-80 hours that can run to 100 when a deal is live, per hours data compiled by Growth Equity Interview Guide. Venture also doesn't gate entry through one job: the 2025 Gannon/Venture5 survey's 700-plus respondents came from banking, consulting, product and engineering roles, and founder backgrounds, not a single standardized pipeline. And because a VC associate spends the job meeting founders and underwriting early, unproven markets rather than modeling an existing company's cash flows, the skill being built — judgment under real uncertainty — compounds differently than PE's financial-engineering discipline.
Shorter average workweek
50-60 hours baseline vs PE's 60-80, before either side's peak periods
More varied entry paths
Banking, consulting, operating roles, and founders all recruit into VC
Earlier company-building exposure
Board seats and founder relationships start sooner than in a typical PE associate seat
A skill set that transfers to founding
Judging people and early markets maps directly onto raising your own fund later
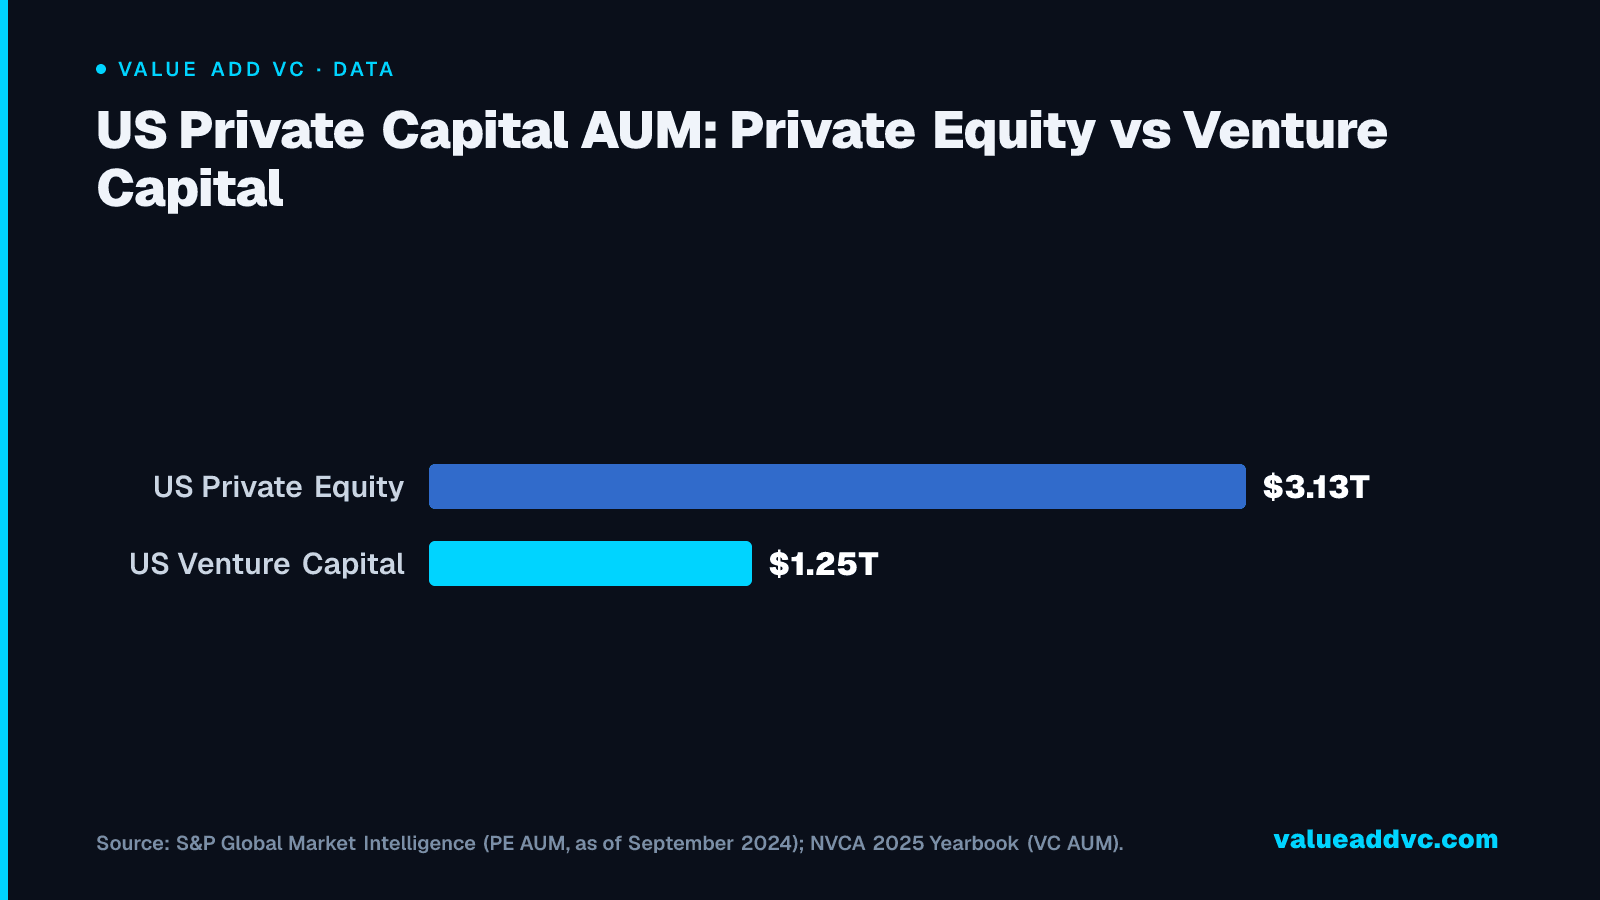
US Private Capital AUM: Private Equity vs Venture Capital
US private equity's asset base, at $3.13 trillion, is roughly 2.5x the size of US venture capital's $1.25 trillion — more capital sitting behind fewer, larger funds at the top of the PE ladder.
S&P Global Market Intelligence (PE AUM, as of September 2024); NVCA 2025 Yearbook (VC AUM).
Data
| Item | Value |
|---|---|
| US Private Equity | $3.13T |
| US Venture Capital | $1.25T |
Recommendation by Situation
There's no universal right answer, but the framework narrows fast once you know what you're optimizing for:
- Coming straight out of a 2-year banking analyst program and want the clearest next step: private equity's on-cycle pipeline is built for exactly this transition.
- Maximizing cash comp in your 20s with the least ambiguity about the path: a mega-fund or large-fund PE seat pays $250,000-$425,000 in year one, well above VC's $120,000-$180,000.
- Coming from an operating, product, or founder background with no banking pedigree: VC recruits far more of these profiles than PE does.
- Want more control over your weekly schedule in your first few years: VC's 50-60 hour baseline beats PE's 60-80, even before either side's busy-season peaks.
- Planning to eventually raise your own venture fund: VC experience builds the founder- and market-judgment skills that transfer directly; PE experience doesn't.
- Planning to eventually run a buy-and-build or search-fund strategy: PE's operational and LBO-modeling discipline transfers far more directly than VC's.
Where I could be wrong
The averages in this post hide enormous variance in both directions. A VC partner at a top-decile fund with meaningful carry points can out-earn most PE principals once a fund has a real winner in it — venture's power-law outcomes mean the top of the distribution looks nothing like the median, more so than in PE's steadier, deal-by-deal carry. The hours comparison is also softer than the headline numbers suggest: a VC associate at a fast-moving Silicon Valley fund during an active fundraise can log PE-level weeks, and PE deal teams between live transactions can run closer to a normal workweek. And the career-path split is less permanent than this post frames it — growth equity sits between the two, and movement between PE and VC later in a career, especially into growth-stage investing, is common enough that an early choice doesn't lock in a lifetime track.
One more complication: venture's own entry funnel narrowed in 2025. The number of active US VC firms fell to 2,984, down from 3,054 the year before — the industry's first-ever year-over-year decline — and first-time fund formation dropped to its lowest level since 2007, down 77.9% from 457 in 2021, according to the NVCA 2025 Yearbook. That means fewer new emerging-manager seats are opening even as larger funds keep hiring, so "venture is more accessible than PE" is less true at the margin than it was a few years ago.
Bottom line: private equity pays more cash at every level, backed by a larger $3.13 trillion US asset base and a standardized banking-to-buyout pipeline; venture capital trades some of that cash for shorter average hours, a wider range of entry paths, and earlier exposure to building rather than restructuring a company. Pick based on which tradeoff you actually want at 25, not which one sounds more prestigious at a dinner party — both paths can lead to the same partner-level outcome from very different starting points.
Compare fund-level return data on the VC Performance Dashboard at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗