
As of October 28, 2026, Lambda is still private and has no public S-1. The Wall Street Journal reported on October 6 that it is raising up to $4 billion at a $14.5 billion pre-money valuation, in what could be its last private round before a planned 2027 IPO. No close has been announced.
Lambda, the Nvidia-backed AI cloud provider, is raising up to $4 billion in a private round led by Coatue Management and Blackstone at a $14.5 billion pre-money valuation, according to TechCrunch, which cited a Wall Street Journal report published October 6, 2026. TechCrunch describes it as what could be Lambda's last private round before a planned 2027 IPO. PYMNTS, also citing the Journal, reports that the November 2025 round valued Lambda at $5.9 billion post-money, based on Forge Global estimates.
Lambda IPO Status: Key Numbers (as of October 28, 2026)
| Date | Event | Valuation / Amount | Source |
|---|---|---|---|
| Nov 18, 2025 | Series E of over $1.5B, led by TWG Global (Lambda did not disclose a valuation) | $5.9B post-money (reported) | Lambda; WSJ citing Forge Global, via PYMNTS |
| Aug 25, 2026 | Bloomberg: talks for up to $3B in pre-IPO financing | $12B or more (reported) | Bloomberg, via The Next Web |
| Sep 2026 | Backlog in a Lambda investor letter reviewed by the WSJ (from $15B in June), much of it a $35B Anthropic commitment | $50B backlog (reported) | TechCrunch |
| Oct 6, 2026 | WSJ: raising up to $4B, led by Coatue and Blackstone; planned 2027 IPO | $14.5B pre-money (reported) | TechCrunch; PYMNTS |
| If fully raised | $14.5B pre-money plus up to $4B of new money | ~$18.5B post-money (our arithmetic) | — |
| Oct 28, 2026 | No public Lambda S-1, S-1/A or draft registration on SEC EDGAR; Lambda, Inc. (CIK 1954966) shows only Form D notices (2022, 2024). No report of the round closing (own check) | — | SEC EDGAR |
A confidential draft registration would not appear on EDGAR until made public. PitchBook data cited by TechCrunch puts the November 2025 post-money at $5.43B rather than $5.9B; Lambda has not disclosed either figure.
Updated Oct 28, 2026
Rechecked October 28, 2026: we found no report that the up-to-$4 billion round has closed, and SEC EDGAR shows no public Lambda S-1. We corrected the lead-investor attribution of the 2026 debt deals (the August term loan B was led by Morgan Stanley; the October fixed-rate loan by J.P. Morgan), added the May 2026 credit facility Lambda references, attributed the $5.9 billion Series E mark to the WSJ's Forge Global estimates, and removed a CoreWeave market-cap figure and peer valuations we could not re-verify.
Lambda IPO Timeline: From GPU Landlord to a Reported $14.5B Pre-IPO Mark
Lambda's planned IPO has already slipped once: per TechCrunch, the company was meant to debut in 2026 but pushed that back amid market uncertainty. Since its February 2025 Series D, Lambda has raised two equity rounds and several large debt financings, and its reported valuation has climbed with each equity round.
| Date | Event | Amount | Valuation |
|---|---|---|---|
| Feb 19, 2025 | Series D (co-led by Andra Capital, SGW) | $480M | ~$2.5B (reported) |
| Nov 18, 2025 | Series E (led by TWG Global) | $1.5B+ | $5.9B (reported) |
| May 2026 | Senior secured credit facility (referenced by Lambda) | $1B | — |
| Aug 27, 2026 | Term loan B closed (Morgan Stanley lead left; Moody's Baa2) | $926M | — |
| Aug 28, 2026 | Reported short-dated debt arranged by JPMorgan to buy chips leased to Microsoft (Bloomberg) | $1B | — |
| Oct 1, 2026 | Fixed-rate delayed-draw term loan (J.P. Morgan) | $1.008B | — |
| Oct 6, 2026 | Reported pre-IPO round (Coatue, Blackstone); not yet closed | Up to $4B | $14.5B (pre-money, reported) |
Sources: Verdict (citing SiliconANGLE for the Series D valuation) and BusinessWire on the February 2025 Series D; Lambda on the November 2025 Series E, with the valuation per the WSJ citing Forge Global (PYMNTS); Lambda on the term loan B and the May 2026 facility; TechCrunch on the August 2026 JPMorgan-arranged debt, citing Bloomberg; Lambda's own announcement of the October 2026 fixed-rate financing; TechCrunch on the October 2026 pre-IPO round. Reported debt deals may overlap; Lambda has not tied the August JPMorgan report to a specific announcement.
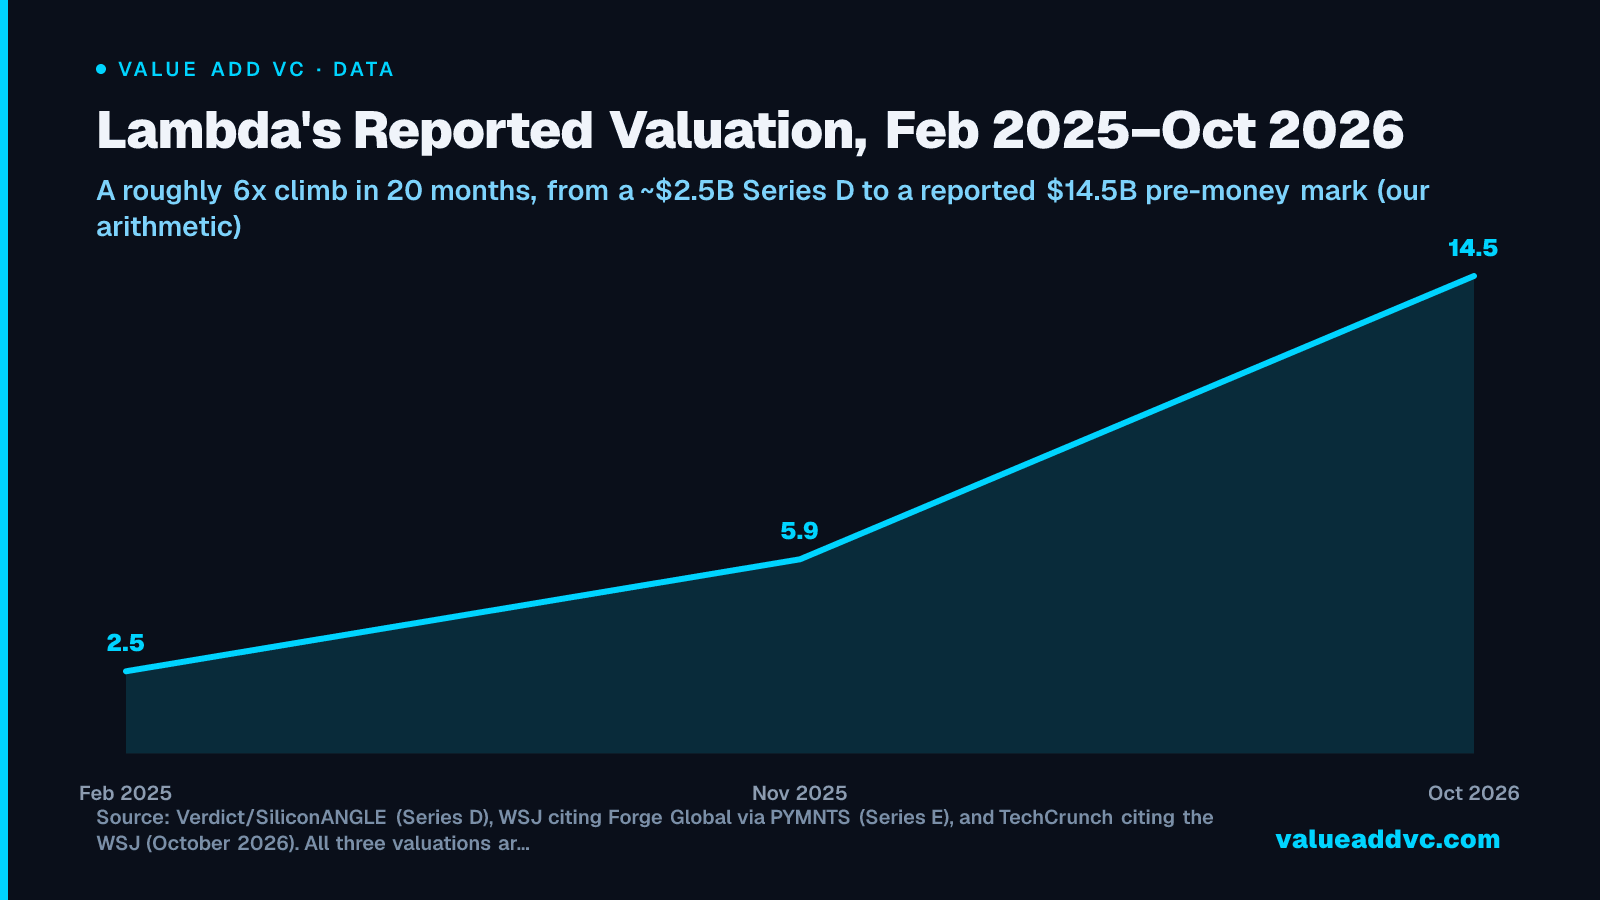
Lambda's Reported Valuation, Feb 2025–Oct 2026
A roughly 6x climb in 20 months, from a ~$2.5B Series D to a reported $14.5B pre-money mark (our arithmetic)
Verdict/SiliconANGLE (Series D), WSJ citing Forge Global via PYMNTS (Series E), and TechCrunch citing the WSJ (October 2026). All three valuations are reported, not disclosed by Lambda.
Data
| Item | Valuation ($B) |
|---|---|
| Feb 2025 | 2.5 |
| Nov 2025 | 5.9 |
| Oct 2026 | 14.5 |
Why Lambda Needs Private Capital Before It Can Go Public
Lambda's business model, buying Nvidia GPUs and leasing the capacity to customers on multiyear contracts, is capital-intensive before it's profitable, which is why the company has stacked debt and equity raises back to back rather than waiting for a single large round. A Lambda investor letter reviewed by the Wall Street Journal shows its backlog grew from $15 billion in June 2026 to $50 billion in September 2026, and TechCrunch reports that much of that increase appears to come from a $35 billion commitment from Anthropic. Bloomberg reported that the $1 billion of JPMorgan-arranged debt in August was to buy Nvidia chips to lease to Microsoft (via TechCrunch); Lambda's October financing release describes the backing as contracted cash flows from two unnamed hyperscale customers.
That backlog growth is the real story behind the valuation jump. A contracted backlog gives lenders and equity investors something concrete to underwrite, which is also why Lambda has been able to raise debt with investment-grade ratings: its August 2026 term loan B carried a Baa2 from Moody's, and its October 2026 fixed-rate financing an A (low) from Morningstar DBRS and a Baa1 from Moody's, according to Lambda.
Why Blackstone and Coatue, Not Just Venture Funds
Blackstone and Coatue Management leading this round is itself a signal about how late-stage AI infrastructure gets financed in 2026. Blackstone is a private-equity firm, not a venture fund, and it has been increasingly active in AI data center deals. Coatue, a crossover fund, has leaned into pre-IPO AI infrastructure bets across its portfolio. Neither firm typically writes a check expecting to wait a decade for a venture-style exit; both are pricing Lambda as a company close enough to a public listing that a 2027 IPO is a real, modelable outcome rather than a distant hope.
That investor mix also explains the debt-heavy capital stack. Private equity and crossover funds are comfortable layering investment-grade-rated debt underneath an equity round when there's a contracted backlog to point to, which is what Lambda did through 2026: a $1 billion credit facility in May, a $926 million term loan B led by Morgan Stanley in August, and a $1.008 billion fixed-rate loan arranged by J.P. Morgan in October, per Lambda. Each was framed as deployment capital tied to GPUs matched to committed customer contracts, not speculative capacity.
What the headline misses
A $14.5 billion pre-money mark for a company that has never disclosed audited revenue or profitability is a bet on contracted backlog translating into cash flow, not a confirmed financial picture. Lambda's 2026 debt financings have gone toward buying GPUs for committed customer deployments, which means the company is scaling capacity ahead of proving it can collect on those leases at the margins investors are pricing in. TechCrunch notes the valuation could be leaning heavily on Anthropic's ability to keep paying.
CoreWeave is the cautionary comp worth watching: its post-IPO stock has swung sharply as public investors re-rate neocloud economics in real time, something private valuations don't have to absorb immediately. If Lambda's 2027 IPO lands in a weaker market for AI infrastructure stocks, the $14.5 billion pre-money mark could look aggressive in hindsight.
What to Watch Before the 2027 Listing
Whether this reported $4 billion round actually closes at a $14.5 billion pre-money valuation, and whether a Lambda S-1 appears on SEC EDGAR with audited revenue and margin figures, are the two concrete signals that would confirm or undercut the IPO timeline. Also worth watching: whether Lambda's GPU-lease contracts with its largest customers carry minimum-commitment clauses that survive a renegotiation if either customer's own AI spending slows. That's the detail separating a durable neocloud from one riding a single customer's capex cycle.
Track private AI infrastructure valuations on the AI Valuations dashboard at Value Add VC.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗