
Updated October 20, 2026: RVII closed at $17.85 on October 19, its lowest close since listing and about 28.6% below its $25 IPO price, and RVI closed at $24.59, about 1.7% below its $25.02 NAV as of June 30, 2026 (Nasdaq.com, Nasdaq.com). RVII has filed no NAV or new holdings since its September 28 10-Q; its first quarter-end holdings list (September 30) has not been published yet. Earlier update, October 1, 2026 (correction): New September 30 closes: RVII $21.55 (was $22.11 on Sept 25, per stockanalysis.com) and RVI $27.84 (stockanalysis.com), about 11% above RVI's $25.02 NAV as of June 30, 2026 (Robinhood). We replaced the March 31 pre-IPO NAV we cited for RVII with the later figures in its final prospectus and its first 10-Q (filed September 28). We also corrected RVI's expense comparison to the 3.13% in its final prospectus (we had said ~2.5%), corrected how we described RVI's legal structure and several RVII company descriptions, and removed claims we could not source: a Databricks August funding round, a YC acceptance rate, a SpaceX listing date, and a closed-end-fund discount statistic.
Robinhood Ventures Fund II — ticker RVII — priced at $25 a share and began trading on the NYSE on August 13, 2026, holding 80 Y Combinator-connected startups behind a 2-and-20 fee structure. It opened its first session at $22.50, a discount to that IPO price (Nasdaq.com), and ten weeks in it is further below it: RVII stock closed at $17.85 on October 19, 2026, about 28.6% under $25 (Nasdaq.com). We've broken down all 80 companies, position by position, on our interactive RVII dashboard. What's still not disclosed matters just as much: RVII has not reported a NAV for any date after its IPO, and its latest published percentage weights are dated July 15 (the final prospectus lists holdings at cost and fair value as of July 31). This page tracks both columns — and it gets updated as details drop.
We've covered Robinhood's first venture fund since it listed in March — the holdings, the NAV math, and above all the premium that peaked at roughly 3x NAV in May and then collapsed, before falling to about 1.7% under its June 30 NAV by the October 19 close. Fund II is a genuinely different product in a similar closed-end wrapper, and the single most useful thing you can do before buying it is understand what happened to Fund I. That story is below, with real prices.
Figures from Robinhood's August 3, 2026 announcement, the final prospectus (424B1, filed August 13, 2026), Robinhood's RVII holdings page (valued as of July 15, 2026), and stockanalysis.com daily closes through September 30, 2026, and Nasdaq.com for the October 19, 2026 close.
What Is Robinhood Ventures Fund II?
RVII is a business development company (BDC), a type of closed-end fund regulated under the Investment Company Act of 1940, per Robinhood's pricing release and its 10-Q. RVI is closed-end too, but it is a registered closed-end fund rather than a BDC, per its annual report. Robinhood announced RVII on August 3, 2026. Its registration statement covered 8 million common shares, and the window for Robinhood Financial customers and advisers on the TradePMR Fusion platform to request IPO shares was scheduled to close August 12, one day before the NYSE debut. The IPO priced at $25/share (announced August 13), raising $200 million in gross proceeds toward a $225.5 million total fund (before sales load and offering expenses), with closing set for August 14.
The mandate is what makes it interesting: instead of buying stakes in large late-stage private companies, RVII invests in a diversified portfolio of early- and growth-stage private companies, focused on current or former Y Combinator participants or companies with a YC-alum founder or co-founder (the prospectus also allows non-YC companies). As of July 15 it held 80. It's closer to buying a slice of YC's pipeline than to buying a stake in any single marquee company — and its prospectus reserves the right to borrow up to 66 2/3% of total assets, which would amplify whatever that basket does in both directions.
Confirmed Facts vs. What's Still Undisclosed
Here is every material fact about RVII, labeled honestly. "Confirmed" means it comes from Robinhood's announcements and holdings page, the fund's SEC filings, or market data; "expected" means an estimate still pending actual reporting; "not disclosed" means exactly that — and we'll fill those rows in as the filings land.
| Detail | What We Know | Status |
|---|---|---|
| Ticker / exchange | RVII on the NYSE | Confirmed |
| First trading day | August 13, 2026 | Confirmed |
| IPO price / first-day open | $25.00/share priced; opened at $22.50 on Aug 13 | Confirmed |
| Latest close | $17.85 on Oct 19, 2026 (-28.6% vs IPO); highest close $25.00 (Sept 4 and Sept 8) | Confirmed |
| Structure | Business development company (closed-end, 1940 Act); RVI is a registered closed-end fund | Confirmed |
| Shares offered / fund size | 8M shares ($200M gross); $225.5M total fund before sales load and offering expenses | Confirmed |
| Over-allotment option | Up to 1.2M extra shares; none issued as of Sept 25, 2026 (9,066,384 shares outstanding, the same count as right after the IPO) | Confirmed |
| Holdings snapshot date | July 15, 2026 (Robinhood holdings page); the first 10-Q, filed Sept 28, covers June 30 | Confirmed |
| Mandate | Current or former YC companies (non-YC allowed); all 80 holdings carry a YC batch label | Confirmed |
| Largest position | Tasklet — 4.50% (only overweight) | Confirmed |
| Standard weight | 1.12% each (78 of 80 companies) | Confirmed |
| Cash & equivalents | 7.39% at July 15 (RVI: 32.28% in a money-market fund at June 30) | Confirmed |
| Top sector | Technology — 64.31% across 55 companies | Confirmed |
| Base management fee | 2.00% of net assets | Confirmed |
| Incentive fee | 20% of realized capital gains, net of realized losses and unrealized depreciation | Confirmed |
| Est. total annual expenses | 4.08% (final prospectus, filed Aug 13); plus 4.50% sales load at IPO | Expected |
| Leverage | May borrow up to 66 2/3% of total assets; fee table shows no borrowing costs | Permitted |
| NAV after the IPO | None reported yet. Starting point about $23.875/share before offering costs (424B1); latest reported: $23.95 at June 30 (10-Q, split-adjusted) and $23.32 at Aug 11 (424B1, before the 0.977 reclassification) | Not disclosed |
| Distributions | Not expected on a regular quarterly basis (10-Q, filed Sept 28, 2026) | Confirmed |
Sources: Robinhood's August 3, 2026 announcement (GlobeNewswire), Robinhood's August 13 pricing release, the final prospectus (424B1) (fees, leverage, the $23.32 NAV at August 11 and the 0.977 reclassification), RVII's first 10-Q (filed September 28, 2026: the $23.95 split-adjusted NAV at June 30, IPO costs, 9,066,384 shares at September 25, distribution outlook), Robinhood's RVII holdings page (weights and sector totals valued as of July 15, 2026; Robinhood's RVII fund page shows the same sector split scaled to sum to 100%, e.g. 64.5% technology), Nasdaq.com historical quotes (August 13 open and close), stockanalysis.com daily closes through September 30, 2026, RVI's annual report (N-CSR), and our own filing analysis on the RVII dashboard. Rows marked "not disclosed" will be updated as filings publish.
What RVII Holds: 80 Companies, Near-Equal Weights, All YC
We went through the disclosed portfolio company by company — the full interactive breakdown of all 80 names lives on our RVII dashboard. The weights below are from Robinhood's RVII holdings page, valued as of July 15, 2026. RVII's first 10-Q, filed September 28, covers the quarter ended June 30; RVII's final prospectus also lists each holding's cost and fair value as of July 31, 2026, so July 15 is only the latest date for which Robinhood publishes percentage weights. Every one of the 80 companies carries a YC batch label (W26 or X26) on that page, and the weighting is almost mechanical: 78 of the 80 sit at 1.12% each. The only overweight is Tasklet, at 4.50%. Robinhood lists it as held through Shortwave Communications, and the prospectus shows a $1,000,000 SAFE in Shortwave Communications ("AI agents that own work end to end") against $250,000 for most names. The only underweight is Luel at 0.45%, a $100,000 SAFE. These July 15 weights predate the IPO: Robinhood's RVII holdings page says capital raised in the IPO will be held in cash and equivalents and invested over time, and the 10-Q shows about $191 million of net IPO proceeds against roughly $22 million of net assets at June 30, so today's cash share is far above the figure below. Cash and equivalents were 7.39% on July 15, compared with the 32.28% RVI held in a money-market fund in its June 30 N-PORT.
By sector, it is mostly a technology fund: 64.31% of the portfolio across 55 companies. Industrials are second at 8.96% across 8 companies, including Tenet Industries (described in the prospectus as low-cost, mass-producible defense systems) and Apollo Atomics (ultra-compact nuclear reactors). Then come financial services (7.84%), healthcare (6.72%, including CellType's agentic drug discovery), consumer cyclical, energy, and communication services. The near-equal weighting is the tell: outside Tasklet and Luel, every company got the same 1.12% slot. Robinhood calls RVII an actively managed portfolio, but as of July 15 it looks more like an equal-weight basket of recent YC companies than a conviction list.
64.31%
Technology
55 companies
8.96%
Industrials
8 companies
7.84%
Financial Services
7 companies
6.72%
Healthcare
6 companies
7.39%
Cash
RVI: 32.28% money-market (Jun 30)
2.24%
Consumer Cyclical
2 companies
1.12%
Energy
1 company
1.12%
Communication Services
1 company
How RVII Differs From RVI
Same $25 IPO price, nearly opposite bet. RVI concentrated its book in a handful of late-stage names — Databricks, OpenAI, Mercor and Revolut lead its June 30, 2026 N-PORT (filed August 21, still its most recent), while its SpaceX stake, bought in SpaceX's IPO, was just 1.25% of net assets. Those weights are three months old: OpenAI's $852B valuation from its March 2026 round, for example, reportedly held flat in an August employee tender. RVII spreads capital across 80 companies at the earliest stages, which changes almost every property of the investment:
Concentration → Diversification
Databricks (12.71%) and OpenAI (11.00%) were each more than a tenth of RVI's net assets at June 30, so a repricing of either moves its NAV. In RVII the largest position is 4.50% and 78 of 80 sit at 1.12% (July 15), so no single startup dominates.
Late-stage → Early-stage
Robinhood describes RVI's holdings as generally mature, later-stage companies. Almost all of RVII's positions are SAFEs in young companies, and its 10-Q warns that a SAFE's value "may not change for an extended period of time, for example, until a conversion is triggered."
3.13% → 4.08% est. expenses
Both charge a 2.00% base fee. RVII's final prospectus estimates 1.97% of other expenses, including a 0.80% repayment to Robinhood, against 1.10% in RVI's, including a 0.68% repayment to its adviser. RVII also charges a 20% incentive fee on realized capital gains, which is not in that estimate; RVI's prospectus says it pays no incentive fee.
Named late-stage companies → YC basket
RVI gives listed exposure to named late-stage companies such as OpenAI and Databricks, and its price peaked at a $73.71 close on May 13, about 3x its March 31 NAV. RVII gives exposure to a basket of current YC-batch companies, and it has not closed above its $25 IPO price.
Sources: RVI's June 30 N-PORT and final prospectus (3.13% estimated total annual expenses, no incentive fee), Robinhood's RVI page and RVII page (stage descriptions), RVII's final prospectus and 10-Q.
RVII's expense estimate moved during the IPO process: the August 3 amended registration statement cited 4.18% in total annual expenses, and the final prospectus filed August 13 lowered that to 4.08%, the figure this page uses. Our Pulse deep-dive on the RVII IPO was published when the fund was announced.
The RVI Lesson: A 3x-NAV Peak, Round-Tripped by July
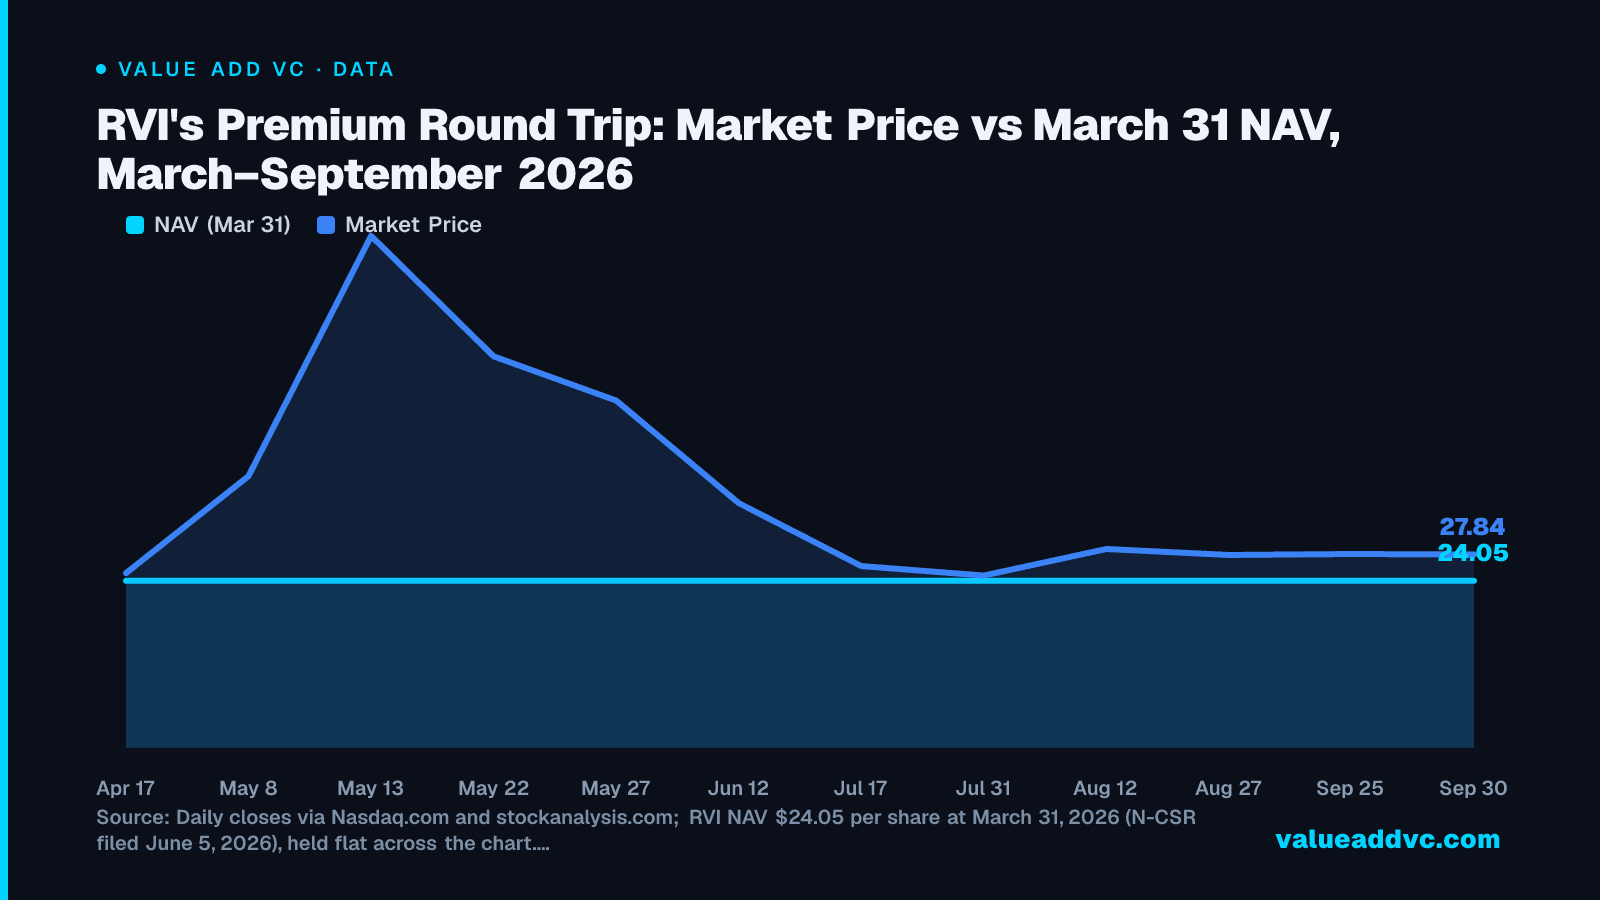
If you read one section on this page before buying RVII, make it this one. RVI priced its IPO at $25.00 and began trading March 6, 2026, closing its first session at $21.00 (Nasdaq.com). It then ran far above NAV: RVI closed as high as $73.71 on May 13, roughly 3x its $24.05 NAV at March 31 (per the N-CSR). Buyers at the top were paying about $3 for every $1.00 of net asset value.
Then the premium unwound week after week: RVI closed at $35.25 on June 12, $26.18 on July 17 and $24.81 on July 31, back below its $25 IPO price (stockanalysis.com). By July 31, anyone who bought at the May 13 close was down about 66%, even though RVI's NAV per share had risen from $24.05 at March 31 to $25.02 at June 30 (Robinhood). Along the way, RVI took a $6.75M allocation in SpaceX's IPO, 1.25% of net assets at June 30. RVI rose 10.2% on August 3, the day Robinhood announced RVII, and closed at $28.64 on August 12. On September 30 it closed at $27.84, about 11% above its $25.02 NAV as of June 30, 2026, but by October 19 it had fallen to $24.59, about 1.7% below that NAV — the dates are months apart, since RVI has not reported a NAV as of September 30. The ~200% premium over the March 31 NAV at the May peak is gone. RVII's October 19 close of $17.85 was about 25% below the roughly $23.875 per share, before offering costs, that its prospectus set as its starting NAV.
RVI's Premium Round Trip: Market Price vs March 31 NAV, March–September 2026
RVI peaked at a $73.71 close on May 13, about 3x its March 31 NAV of $24.05, fell to $24.81 by July 31, and closed at $27.84 on September 30, about 11% above the $25.02 NAV it reports as of June 30 (not plotted). RVII, by contrast, has not closed above its $25 IPO price.
Daily closes via Nasdaq.com and stockanalysis.com; RVI NAV $24.05 per share at March 31, 2026 (N-CSR filed June 5, 2026), held flat across the chart. RVI's $25.02 NAV as of June 30, 2026 (Robinhood) is not plotted.
Data
| Item | NAV (Mar 31) | Market Price |
|---|---|---|
| Mar 6 | 24.05 | 21 |
| Apr 17 | 24.05 | 25.15 |
| May 8 | 24.05 | 39.13 |
| May 13 | 24.05 | 73.71 |
| May 22 | 24.05 | 56.37 |
| May 27 | 24.05 | 50.01 |
| Jun 12 | 24.05 | 35.25 |
| Jul 17 | 24.05 | 26.18 |
| Jul 31 | 24.05 | 24.81 |
| Aug 12 | 24.05 | 28.64 |
| Aug 27 | 24.05 | 27.77 |
| Sep 25 | 24.05 | 27.92 |
| Sep 30 | 24.05 | 27.84 |
The mechanism is structural, not a fluke. Closed-end fund shares cannot be redeemed with the fund; they trade on an exchange at a market price that can sit above NAV (a premium) or below it (a discount), as Robinhood's own RVII disclosures put it. We documented RVI's version of this in real time across the premium explainer, the premium/discount history, and the discount-history tracker. RVII has the same closed-end feature from day one.
Should You Wait for RVII or Buy RVI?
Honest answer: they're different enough that "which one" is the wrong frame — the real question is what exposure you actually want, and at what price relative to NAV.
RVI makes more sense if you:
- Want exposure to named late-stage companies — RVI publishes a schedule of investments, so you can read exactly what it holds
- Prefer the lower expense estimate: 3.13% in RVI's final prospectus, with no incentive fee, vs 4.08% plus a 20% incentive fee on realized capital gains for RVII
- Can buy much closer to NAV than at the May peak. RVI closed at $24.59 on October 19 (Nasdaq.com) against its $25.02 NAV as of June 30 (Robinhood) — about a 1.7% discount, versus roughly 200% over the March 31 NAV at the May 13 peak
RVII makes more sense if you:
- Want early-stage venture exposure: all 80 of RVII's holdings carry a YC batch label (W26 or X26)
- Believe in YC's aggregate pipeline more than in any single company
- Accept a heavier fee load, permitted leverage of up to 66 2/3% of total assets, and SAFE marks that may not change until a conversion is triggered
- Are comfortable buying a fund that has not closed above its IPO price since listing, with no post-IPO NAV reported yet
And one rule applies to both: the premium you pay at entry matters more than the portfolio. RVI showed that NAV per share can rise ($24.05 at March 31 to $25.02 at June 30) while buyers at the May peak lose about two-thirds of their money by July 31 as the premium compresses. If RVII ever trades at a hot premium, the RVI chart above is what the other side of that trade looks like. Our five-question premium framework was written for RVI, but every question transfers directly to RVII — as does the step-by-step buying mechanics guide and the closed-end fund tax treatment.
The Complete RVI & RVII Coverage Library
We've tracked the Robinhood Ventures funds since Fund I listed. Everything below is kept current:
RVII is the broader, earlier, more expensive sequel to a fund whose defining event was a premium that spiked to roughly 3x NAV in May and had turned into a roughly 1.7% discount by October 19.
The confirmed facts fit in one table. The missing one — a NAV for any date after the IPO — is what will show how deep RVII's discount really is. We'll update this page when it lands.
This is a living page — last updated October 1, 2026, seven weeks into RVII's NYSE trading. Track Fund I's NAV and premium on the Robinhood RVI Fund dashboard, and follow ongoing coverage on Value Add Pulse. Originally covered in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗