
As of October 28, 2026, Iambic Therapeutics trades on the Nasdaq Global Select Market as IAM and closed at $14.78, a $700.6 million market cap per Yahoo Finance, below its IPO price. It priced that IPO at $16.00 a share on October 14, selling 9,375,000 shares for $150 million, which implied about $758 million on its post-offering share count, according to the company's pricing announcement and final prospectus. IAM began trading October 15, closed as high as $23.81 on October 16, and has closed below its $16 IPO price every session since October 21, per Yahoo Finance.
Iambic IPO: Key Numbers (as of October 28, 2026)
| Date | Event | Amount / Valuation / Revenue | Source |
|---|---|---|---|
| Sep 21, 2026 | Files for a US IPO; deal originally reported at about $100M | ~$100M (reported target) | Reuters via The Star |
| Oct 8, 2026 | Amended S-1 sets terms: 9.375M shares at $15-$17 | ~$150M (midpoint) | SEC EDGAR |
| Oct 14, 2026 | Prices IPO at $16.00; 9,375,000 shares; 30-day option for 1,406,250 more | $150M gross | Company release; SEC 424B4 |
| Oct 14, 2026 | Implied value at $16 on 47,400,796 shares outstanding after the offering | ~$758M (implied) | SEC 424B4 |
| Oct 15, 2026 | IAM debuts on Nasdaq; opens $16.15, closes $18.91 (+18.2%) | $18.91 close | Yahoo Finance |
| Oct 16, 2026 | Highest close so far (+48.8% vs IPO) | $23.81 close | Yahoo Finance |
| Oct 16, 2026 | Restated charter filed in connection with IPO completion (Form 8-K) | Closed | SEC 8-K |
| Oct 27, 2026 | Lowest close so far | $14.00 close | Yahoo Finance |
| Oct 28, 2026 | Closing price (4:00 PM ET) and market cap, per Yahoo Finance | $14.78 / $700.6M | Yahoo Finance |
| Oct 28, 2026 | EDGAR check: latest filings are the 424B4 (Oct 15), 8-K (Oct 16) and Form 4s (Oct 19); no 10-Q yet | No 10-Q filed | SEC EDGAR |
| ~Apr 12, 2027 | Insider lockup ends: 180 days after the Oct 14, 2026 prospectus (our arithmetic) | 180 days | SEC 424B4 |
The implied value is Value Add VC arithmetic on the prospectus share count, not a company figure. The lockup end date is our arithmetic from the prospectus date; underwriters can release shares early. We found no announcement of the underwriters exercising their option as of October 28, 2026. ARK and Duquesne's up-to-$60 million indication of interest was non-binding.
Source: SEC EDGAR final prospectus (424B4), dated October 14, 2026.
Iambic Therapeutics IPO: From Terms to Pricing
Iambic Therapeutics filed an amended S-1 on October 8, 2026 setting terms for its Nasdaq IPO: 9.375 million shares priced at $15.00 to $17.00 apiece, with underwriters holding a 30-day option to buy up to 1.406 million additional shares. At the midpoint, that implies a $150 million raise and a roughly $758 million market cap.
J.P. Morgan, Jefferies, BofA Securities, and Citigroup are joint book-runners on the deal, which listed on the Nasdaq Global Select Market under the ticker IAM. It priced on October 14 at $16.00, inside that range, and began trading on Nasdaq under IAM on October 15.
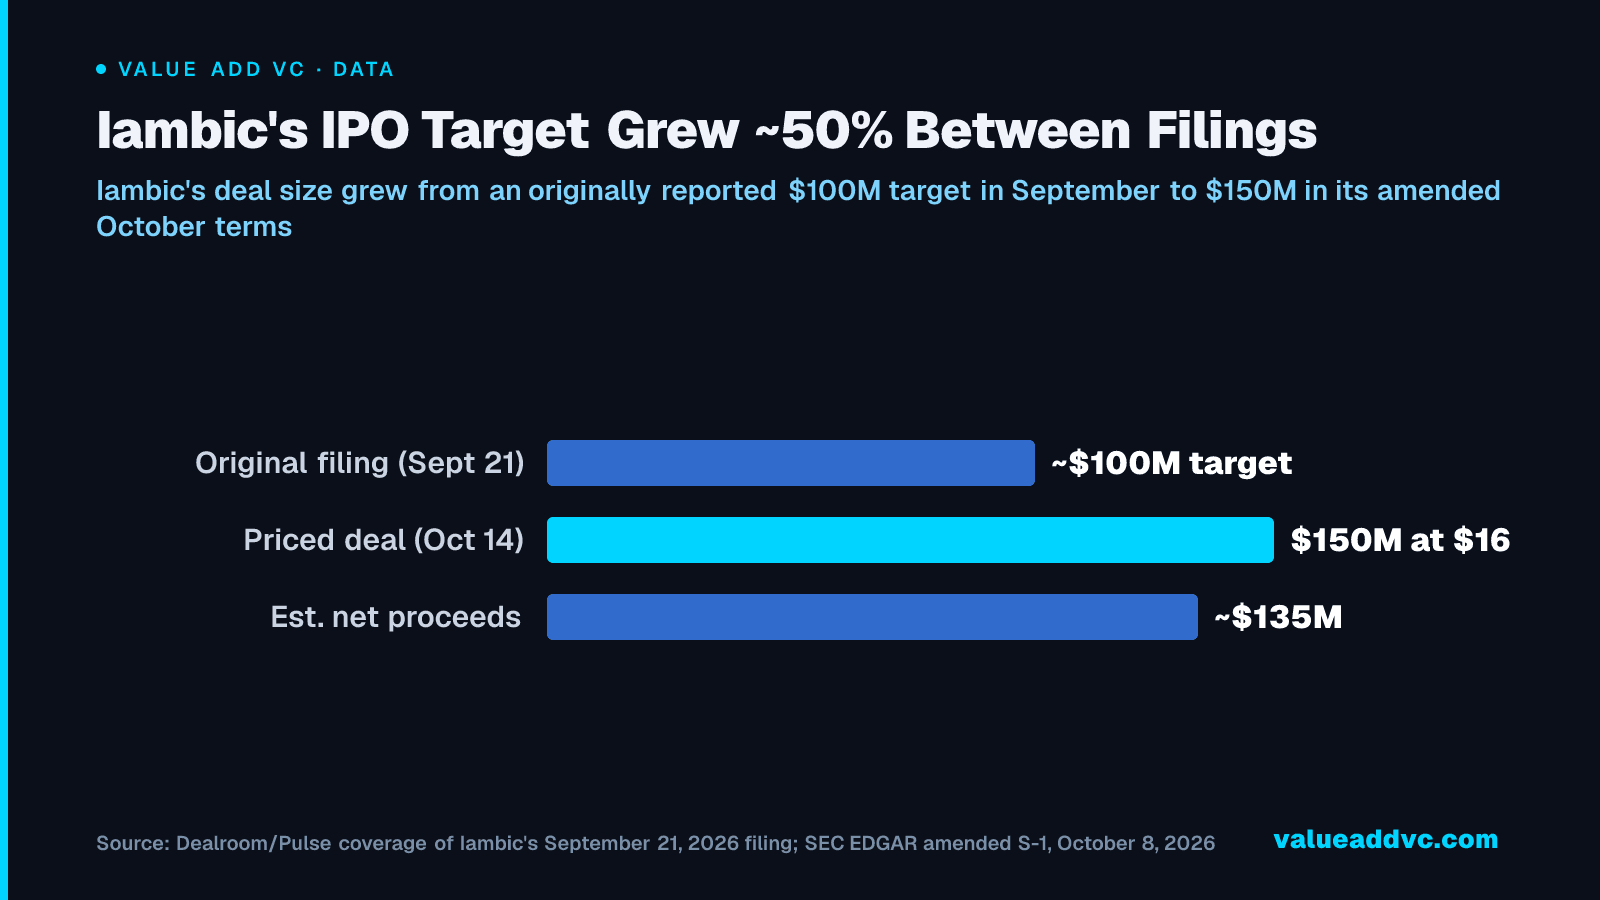
Iambic's IPO Target Grew ~50% Between Filings
Iambic's deal size grew from an originally reported $100M target in September to $150M in its amended October terms
Dealroom/Pulse coverage of Iambic's September 21, 2026 filing; SEC EDGAR amended S-1, October 8, 2026
Data
| Item | Value |
|---|---|
| Original filing (Sept 21) | ~$100M target |
| Priced deal (Oct 14) | $150M at $16 |
| Est. net proceeds | ~$135M |
Who's Anchoring the Deal
ARK Investment Management and Duquesne Family Office have both indicated non-binding interest in buying up to $60 million of shares combined at the IPO price — a notable anchor commitment for a biotech that is still well short of profitability. Those indications weren't binding orders, but they gave the deal a visible demand floor before the roadshow.
Iambic reported a $77.3 million net loss in 2025 against just $9.4 million in collaboration revenue, underscoring how heavily the company has leaned on pharma partnerships — including ties to Nvidia and Qatar-linked backers noted in its original September filing — rather than product revenue to fund its pipeline. The company plans to use the roughly $135 million in expected net proceeds (about $155.9 million if underwriters exercise their option in full) to advance its lead candidate and earlier-stage programs.
What Iambic Is Actually Building
Iambic was founded in 2019 as Entos and is based in San Diego, California. It has raised roughly $461.8 million since founding from backers including Nvidia, Qatar's sovereign wealth fund (QIA), Catalio, Nexus Ventures, and Coatue Management, and holds pharma partnerships with Takeda, Lundbeck, Revolution Medicines, Jazz Pharmaceuticals, Bayer, and — announced the same day as its original September filing — AbbVie, according to Reuters' reporting on the September 21, 2026 filing, carried by The Star.
Iambic's lead candidate, IAM1363, is an oral HER2 inhibitor currently in an ongoing Phase 1/1b basket trial for patients with HER2-altered solid tumors, with a registrational trial that could start as early as 2027. Two earlier-stage candidates sit behind it: IAM217, a KIF18A allosteric inhibitor whose IND was submitted to the FDA on September 30, 2026, and IAM-C1, a CDK2/4 dual inhibitor with an IND expected in Q4 2026 — both pending regulatory clearance before Phase 1/2 trials can begin.
Iambic markets itself as an AI-native drug-discovery company, positioning its computational platform against both traditional biotech R&D and a growing cluster of AI-first drug companies that have raised large private rounds over the past two years. The table below compares Iambic's IPO terms to recent peers in that category.
| Company | Focus | Valuation | Date | Status |
|---|---|---|---|---|
| ADARx Pharmaceuticals | RNA therapeutics | $1.81B | Sept 2026 | Priced IPO (ADRX) |
| Chai Discovery | AI drug design platform | $3.8B | 2026 | Private, Series C |
| Iambic Therapeutics | AI-native small-molecule drug discovery | ~$758M | Oct 2026 | Priced IPO (IAM) at $16 |
Sources: SEC EDGAR, and our own reporting on ADARx and Chai Discovery, checked October 21, 2026.
What the headline misses
The deal priced, but early trading shows how fragile the number is. IAM closed 48.8% above its $16 IPO price on its second day, then gave all of that back within four sessions and kept falling, closing at $14.78 on October 28, about 7.6% below the IPO price (our arithmetic), per Yahoo Finance. The roughly $758 million value is our arithmetic on prospectus share counts, and ARK and Duquesne's combined $60 million of indicated interest was explicitly non-binding; the final prospectus does not say how much they bought.
The business itself carries real pre-revenue risk. A $77.3 million net loss against $9.4 million in collaboration revenue means Iambic is years away from its own product revenue, and its lead candidate IAM1363 is still in an early basket trial — a registrational trial isn't expected to start before 2027 at the soonest. Investors here are pricing a drug-discovery pipeline, not an approved therapy.
Context also matters for the deal's reception: this quarter's broader biotech IPO pipeline has produced far more S-1 filings than actual pricings, meaning Iambic is debuting into a market that has been more willing to file than to buy. Iambic priced in the upper half of its range rather than above it, and the stock's slide below the IPO price within a week is the market's first verdict on AI-native biotech appetite. A day later, City Therapeutics set its own terms for a $175 million IPO, giving investors a same-week comp from a different bank syndicate and a different RNAi-based modality.
Is the Deal Size Increase a Good Sign?
Going from a placeholder ~$100 million target in September to a $150 million deal priced at $16 in October, with two large institutional names attached as non-binding anchors, was a meaningfully stronger outcome than Iambic looked set for three weeks earlier. That's real progress, not just paperwork — amended S-1s with firm price ranges and named anchor investors typically come after banks have already tested demand with institutional investors.
Whether that translates into a durable public-market valuation is a separate question that IAM's first two weeks of trading, which ended below the IPO price, have only started to answer. A $758 million implied cap on a company with a single Phase 1/1b asset and no near-term path to revenue is a bet on Iambic's AI-discovery platform generalizing to a broader pipeline — the same bet every AI-native biotech is asking public investors to make, just with less dilution risk than Iambic's earlier private backers took on.
The bottom line:
Iambic Therapeutics raised $150M at $16 a share, about a $758M implied value and ~50% more than its original ask — but IAM was back below its IPO price within a week, and the $77.3M net loss behind it is a reminder this is a pre-revenue drug-discovery bet.
Track the original filing in our Pulse coverage of Iambic's amended terms, see how other AI drug-discovery startups are raising in our look at the category, and read more analysis at Value Add VC.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗