
This post covers the May 2026 Series E. For Sierra's full valuation history, every round and how it makes money, see Sierra AI valuation 2026: history and business model →
Sierra AI is valued at $15.8B after a $950M Series E in May 2026 — up from a $1B valuation at launch just 27 months earlier — on roughly $200M in annualized revenue at the time, which Sierra says has since passed $400M, from enterprises paying per resolved customer-service interaction rather than per seat.
Bret Taylor still chairs OpenAI's board alongside running Sierra — and his own company just became one of the fastest-compounding valuations in enterprise software history. The pace matters more than the headline number: four rounds, four step-changes in valuation, in barely over two years, on a bet that AI agents replace the seat-based software model entirely.
What Changed: Updated October 30, 2026
The valuation and the Series E terms below are unchanged. What moved is the revenue base underneath them. In a company blog post dated October 30, 2026, Sierra said:
- ARR passed $400M. Sierra says it hit $400M+ in ARR that week, adding over $150M in ARR in Q3 alone. It reports six months to double from $100M to $200M and five months to double from $200M to $400M.
- Fortune 50 reach. Sierra says it now works with almost 50% of the Fortune 50.
- An open standard. Sierra says it is developing an open standard called Poppy with over 50 enterprises including Meta, Instinct, Rocket, Shopify, Stripe, and Walmart.
These are company-reported figures from Sierra's own blog, not audited numbers or independent reporting. The $15.8B valuation is the May 2026 Series E mark, set when ARR was roughly $200M.
Sierra AI Valuation 2026: From $1B to $15.8B in 27 Months
Sierra's valuation is $15.8B as of May 2026, set by a $950M Series E led by Tiger Global and GV, with Benchmark, Sequoia Capital, and Greenoaks Capital also participating. That is up from $10B eight months earlier and from $1B when Bret Taylor and Clay Bavor launched the company in February 2024.
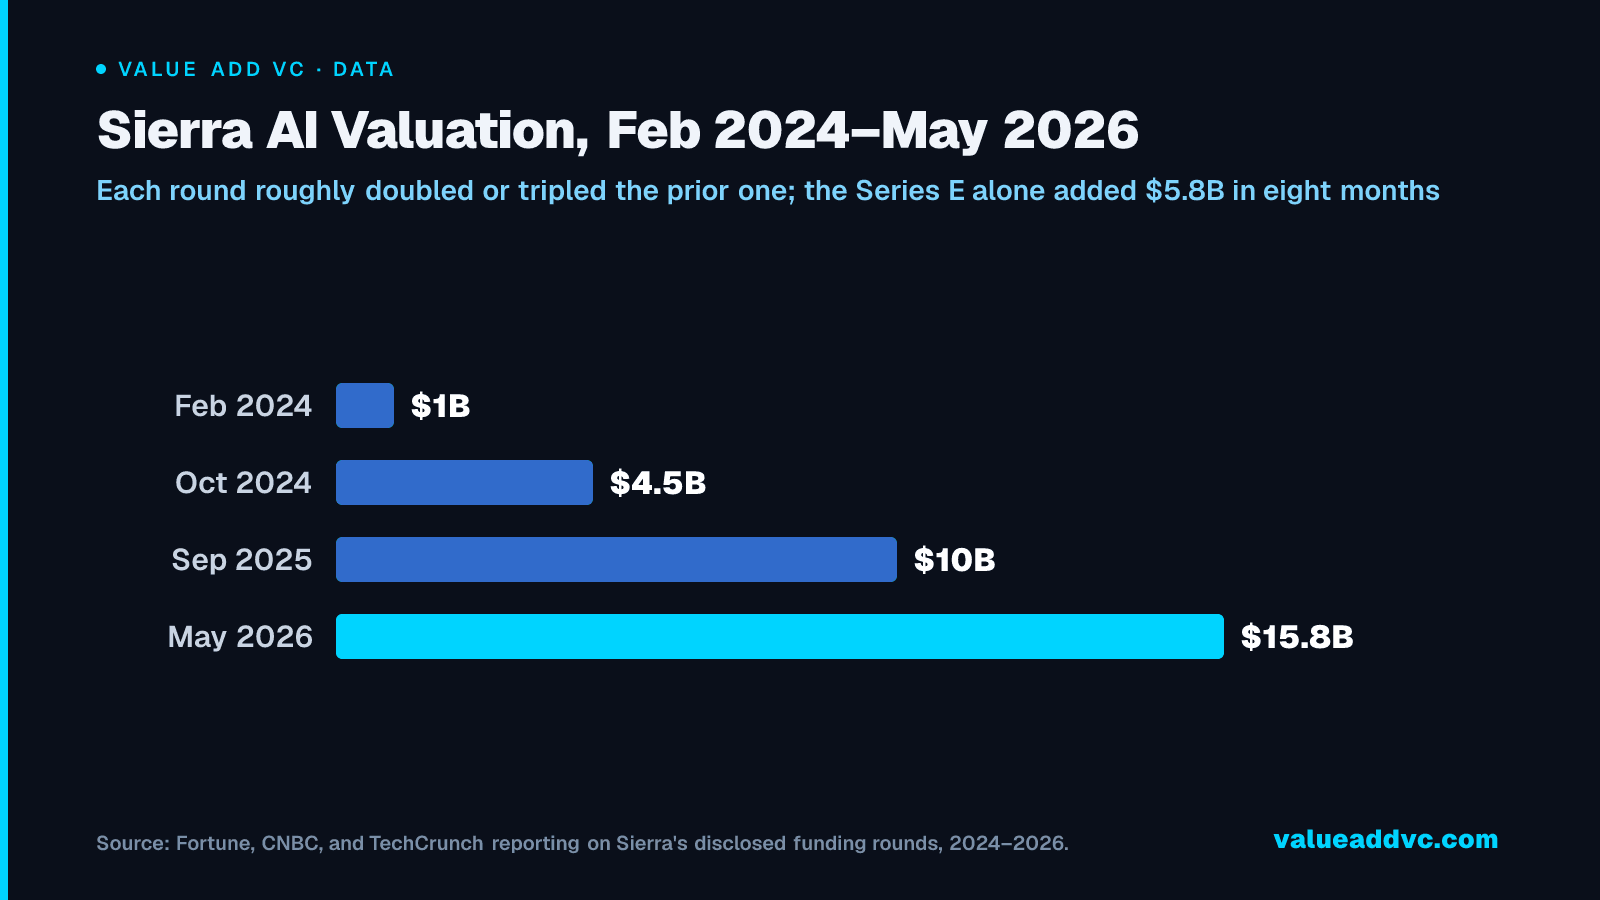
The step-change pattern is the story. Fortune reported the February 2024 launch: a $110M round from Sequoia and Benchmark at close to a $1B valuation, before Sierra had a paying customer. By October 2024, CNBC reported a $175M round led by Greenoaks Capital at $4.5B. Less than a year after that, in September 2025, the valuation reached $10B on a $350M round. Compare Sierra against every other AI company repricing this fast on the AI Valuations dashboard.
Sierra AI Valuation, Feb 2024–May 2026
Each round roughly doubled or tripled the prior one; the Series E alone added $5.8B in eight months
Fortune, CNBC, and TechCrunch reporting on Sierra's disclosed funding rounds, 2024–2026.
Data
| Item | Value |
|---|---|
| Feb 2024 | $1B |
| Oct 2024 | $4.5B |
| Sep 2025 | $10B |
| May 2026 | $15.8B |
The Revenue Behind the Number: $400M+ ARR on Outcome-Based Pricing
Sierra crossed $100M in annualized recurring revenue in November 2025, about 21 months after launch — a pace TechCrunch called out as among the fastest for enterprise software. By the May 2026 raise, reporting around the round put run-rate near $200M, which made $15.8B close to 79x revenue. On October 30, 2026, Sierra said in a company blog post that it had hit $400M+ in ARR, adding over $150M in Q3 alone; it took six months to double from $100M to $200M and five months to double from $200M to $400M. Against that figure the $15.8B mark works out to under 40x, though the valuation itself dates from May and the ARR is company-reported.
The mechanism behind that revenue is unusual: Sierra doesn't sell seats or API credits. It charges roughly $1.50 for every customer interaction its AI agent actually resolves, an outcome-based model Taylor has argued repeatedly is the correct pricing unit once software does the work itself rather than assisting a human who does. We break down the full mechanics — pricing tiers, margin structure, and what "resolved" means contractually — in how Sierra AI makes money. Disclosed customers span ADT, Sonos, WeightWatchers, and Casper — physical-product and subscription businesses with high support-ticket volume, which is exactly where outcome-based pricing has the clearest ROI story to sell into a procurement committee. In the same post Sierra says it now works with almost 50% of the Fortune 50, and that it is developing an open standard called Poppy with over 50 enterprises including Meta, Instinct, Rocket, Shopify, Stripe, and Walmart.
Sierra vs Decagon, Agentforce, and Intercom Fin on Price
Every credible competitor in enterprise AI customer agents has converged on some version of outcome- or resolution-based pricing, which makes the per-interaction rate one of the few apples-to-apples numbers across the category.
Enterprise AI Agent Pricing: Cost per Resolved Interaction
Vendor pricing pages and reported enterprise contract terms, 2026
Data
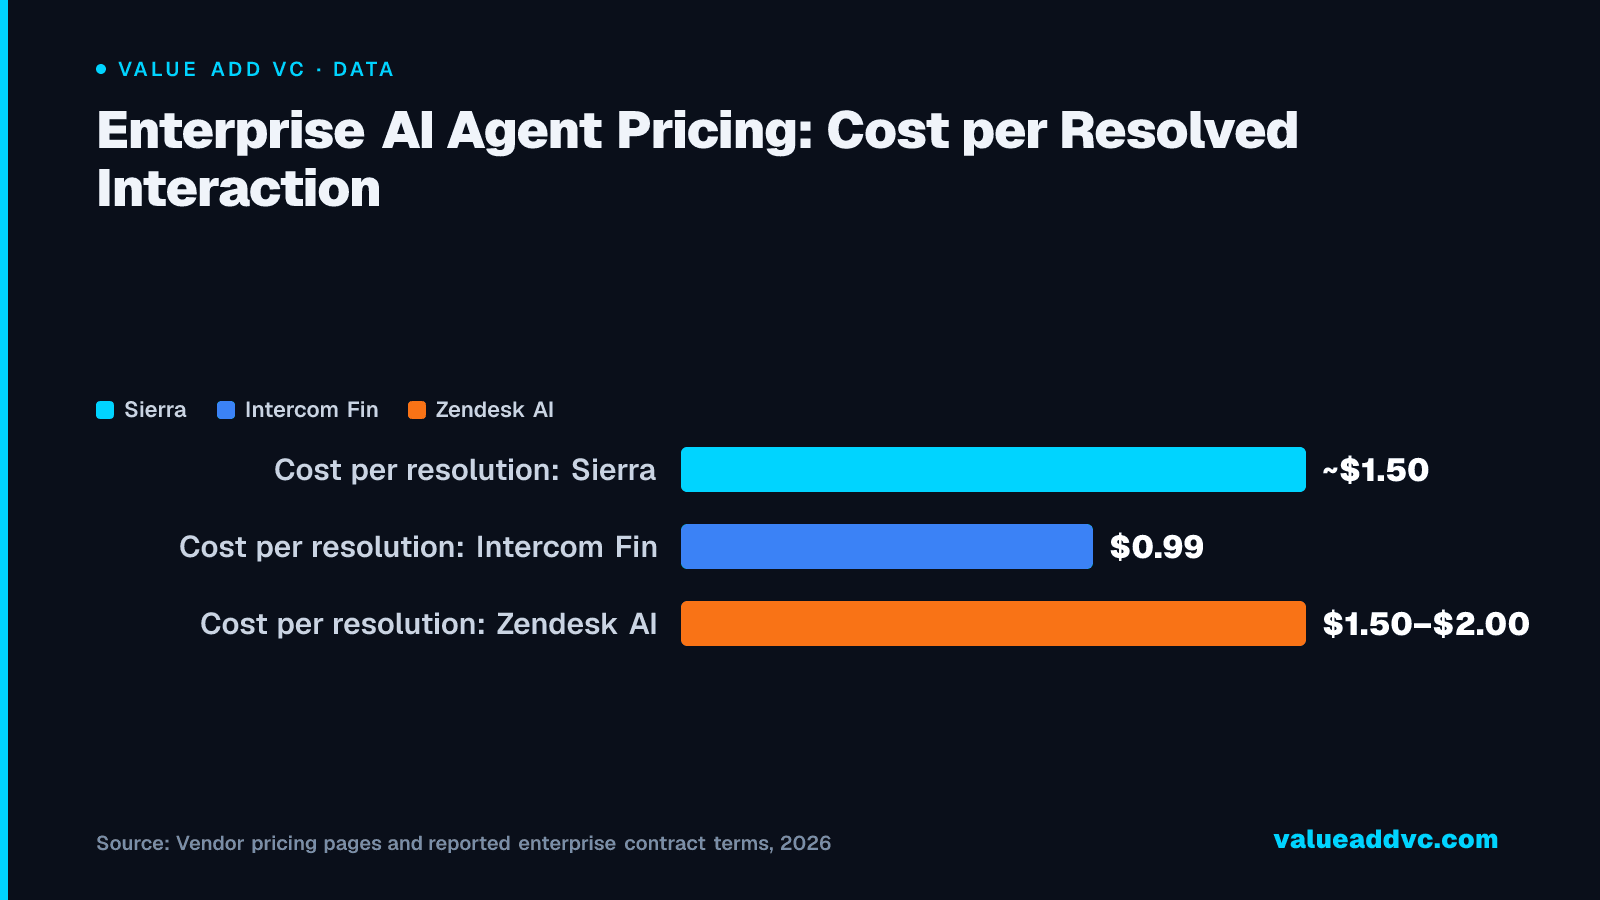
Decagon and Salesforce Agentforce price custom enterprise contracts rather than publish a flat per-resolution rate, so they are not shown on this chart.
Decagon is the closest AI-native challenger by growth trajectory, and Salesforce Agentforce and Zendesk AI are the incumbent-platform answers — Sierra's pitch against both is that it's vendor-neutral rather than bundled into a CRM or helpdesk you may not already run. Salesforce closed its acquisition of Intercom's Fin on September 10, 2026, folding a direct competitor into the same incumbent camp Sierra is positioned against.
The Bull Case: Pricing Software Like Labor, Not Seats
If Sierra is right that AI agents should be priced on completed work rather than logins, it has built the pricing model the rest of the category will eventually copy — and being first with the enterprise logos and the renewal data to prove the model works is a real moat. Outcome-based pricing also aligns Sierra's revenue directly with the value it delivers: as its agents resolve a larger share of a customer's support volume, revenue scales with them, without a separate sales motion to expand seats.
Where I Could Be Wrong
A 79x-revenue multiple at the time of the Series E (under 40x on October's company-reported $400M+ ARR) prices in years of continued hypergrowth, and outcome-based pricing has a structural ceiling problem: once an enterprise's AI agent resolves nearly all of its support volume, that customer's spend flattens — there's no more "seats to add." That's the opposite of traditional SaaS expansion revenue, and it means Sierra needs a constant stream of new logo growth rather than compounding existing accounts as heavily. The other risk is competitive: Salesforce folding Fin into Agentforce and Zendesk running its own resolution-priced agent both show the incumbents can copy the pricing model without needing Sierra's valuation multiple to make the economics work for them.
Explore Related Dashboards
Interactive tools with live data on this topic
Track Sierra and the rest of the enterprise AI agent category on the AI Valuations Dashboard at Value Add VC.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗