
Moonshot AI just raised $3.5 billion at a $35 billion valuation — roughly 117 times its $300 million ARR run rate. That's the number everyone's tweeting about. It's not the number that matters.
Revenue multiples quoted out of context often make a headline number do more work than it should. A 117x multiple sounds like peak-bubble math, full stop. But when a company's revenue is tripling every few months and it just had to pause new subscriptions because it physically ran out of GPU capacity, the trailing multiple is measuring the wrong thing.
Figures from Bloomberg, CNBC, and company disclosures on Moonshot AI's July 2026 round, cross-referenced against Value Add VC's OpenAI and Anthropic valuation tracking, 2026.
What is Moonshot AI's valuation in 2026?
Moonshot AI, the Beijing-based maker of the Kimi model family, closed a $3.5 billion round in late July 2026 at a $35 billion valuation — far above its original $1-2 billion fundraising target. Lead investors included China's National AI Industry Investment Fund (also a DeepSeek backer), alongside Alibaba and Tencent. In July, Moonshot was reported to be lining up a follow-on round at a $50 billion pre-money valuation ahead of a planned Hong Kong IPO. As of October 6, 2026, Moonshot AI has closed that final private round at a valuation of about $50 billion, Bloomberg reported, citing people familiar with the matter; the round size was not disclosed.
The consensus take: 117x ARR is obviously a bubble
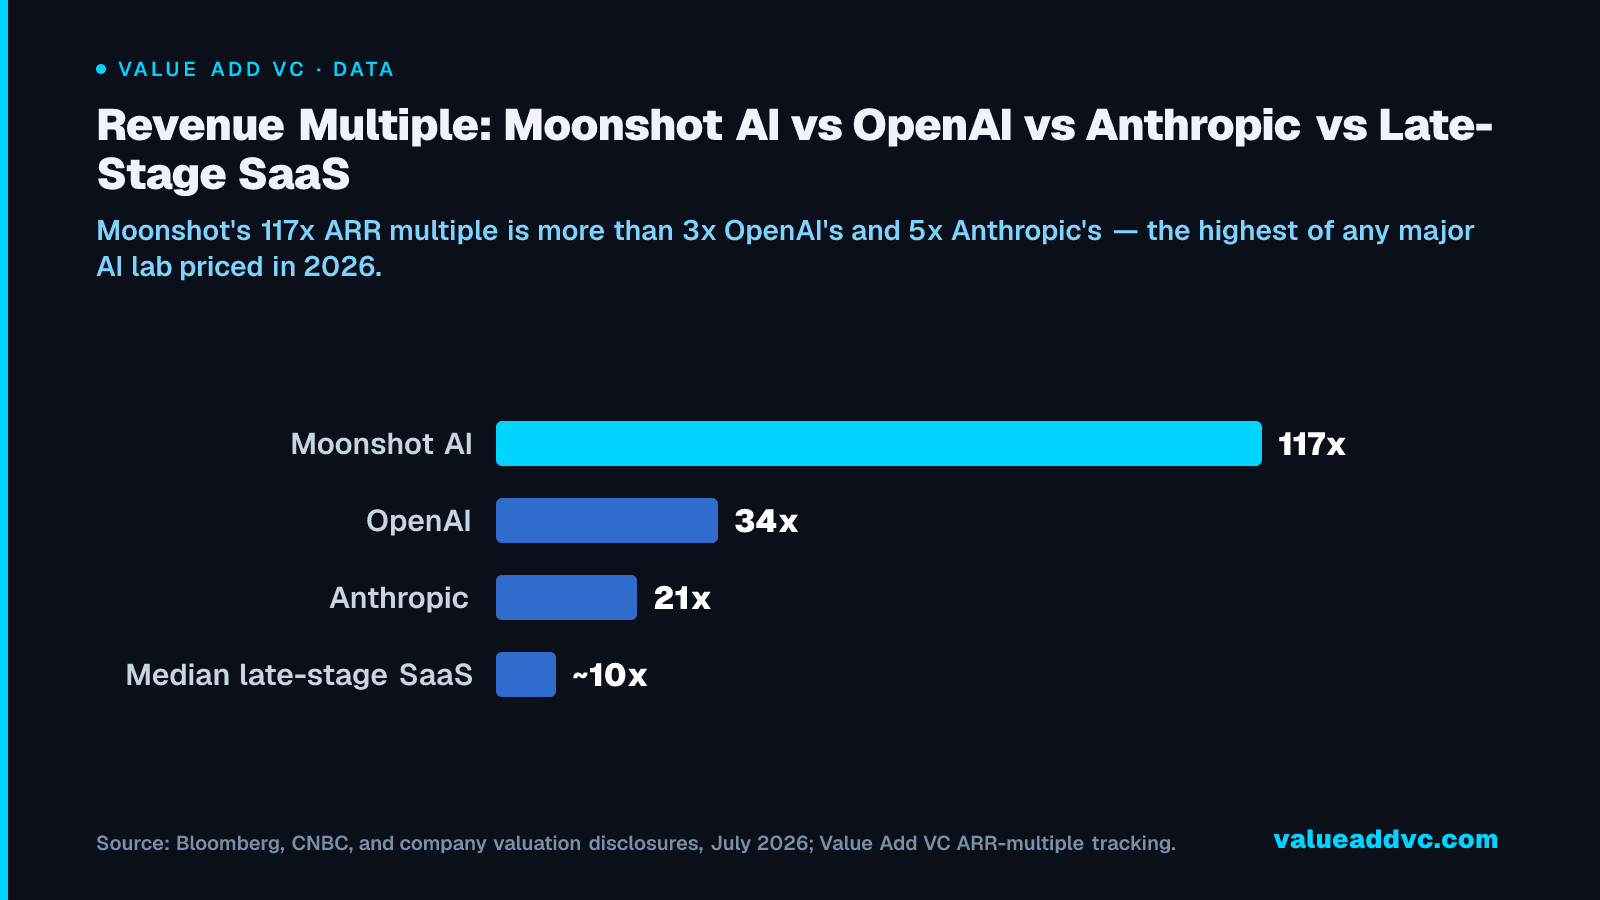
Here's the easy argument, and it's not wrong on its face. Moonshot's ARR was about $300 million as of June 2026. Divide that into a $35 billion valuation and you get roughly 117x trailing revenue — more than three times OpenAI's ~34x (on an $852 billion valuation against ~$25 billion ARR) and more than five times Anthropic's ~21x (on $965 billion against over $47 billion ARR). Late-stage SaaS companies, for comparison, typically trade at single-digit to low-teens multiples once growth slows below 40% annually.
By that framing, Moonshot looks like the most aggressively priced AI lab on the planet, Chinese or American. That's the story most coverage of this round has run with, which is understandable — 117x is a genuinely wild number to put next to a company two years removed from its founding.
Revenue Multiple: Moonshot AI vs OpenAI vs Anthropic vs Late-Stage SaaS
Moonshot's 117x ARR multiple is more than 3x OpenAI's and 5x Anthropic's — the highest of any major AI lab priced in 2026.
Bloomberg, CNBC, and company valuation disclosures, July 2026; Value Add VC ARR-multiple tracking.
Data
| Item | Value |
|---|---|
| Moonshot AI | 117x |
| OpenAI | 34x |
| Anthropic | 21x |
| Median late-stage SaaS | ~10x |
Here's where the consensus falls short
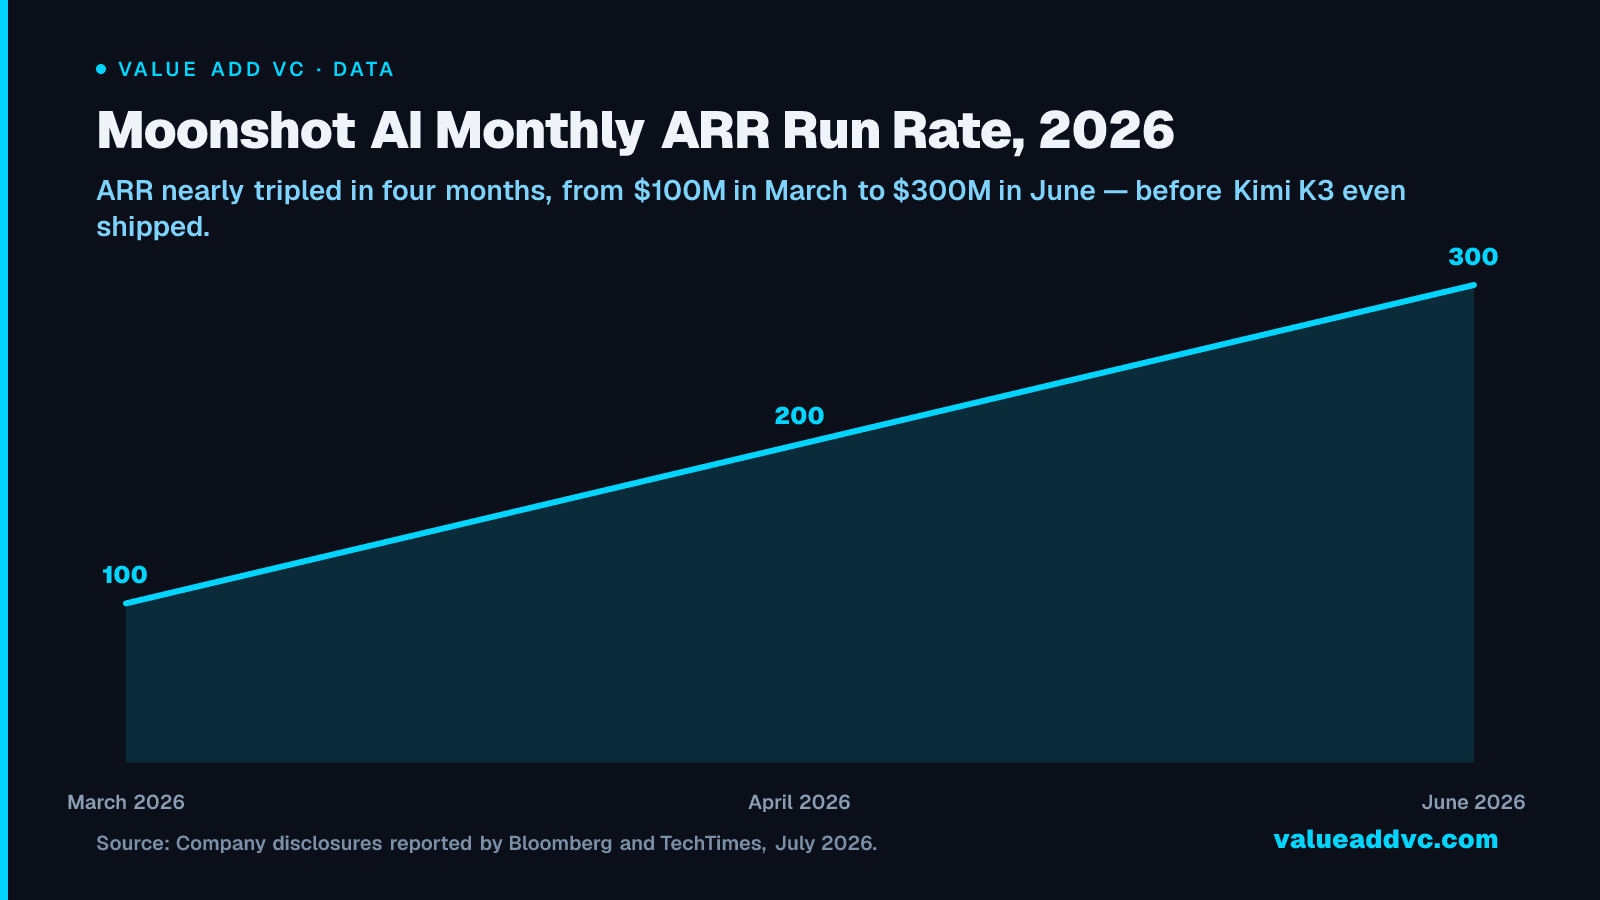
A trailing multiple assumes the trailing number is a reasonable proxy for what's coming next. For Moonshot, it isn't. ARR went from roughly $100 million in March 2026 to $200 million in April and $300 million in June — a near-tripling in four months, with API licensing driving more than 70% of that revenue. Then Kimi K3 launched: a 2.8-trillion-parameter mixture-of-experts model that reportedly drove a sixfold jump in daily sales almost overnight. Moonshot had to pause new subscriptions because it ran out of GPU capacity to serve the demand.
Read that again: the company turned away paying customers. That's not what a demand problem looks like. It's what a supply problem looks like, and the supply problem here has a specific, well-documented cause — US export controls have cut off Chinese labs from Nvidia's most advanced accelerators, forcing Moonshot, DeepSeek, and Zhipu AI to run on constrained H800/A800-class chips or in-house silicon instead of scaling freely on whatever hardware demand requires.
My contrarian read: the 117x multiple isn't mispricing Moonshot's demand curve. If anything, a trailing-revenue multiple understates it, because the company is capping its own top line by choice rather than running out of customers to sell to.
Moonshot AI Monthly ARR Run Rate, 2026
ARR nearly tripled in four months, from $100M in March to $300M in June — before Kimi K3 even shipped.
Company disclosures reported by Bloomberg and TechTimes, July 2026.
Data
| Item | ARR ($M) |
|---|---|
| March 2026 | 100 |
| April 2026 | 200 |
| June 2026 | 300 |
The real risk in Moonshot AI's valuation isn't the multiple — it's the chip ceiling
Flip the bubble argument around and there's a more uncomfortable version of it for Moonshot's investors. If the constraint on revenue is compute, not customers, then the $35 billion price tag is a bet that Moonshot (and its state-linked backers) can secure enough chip supply — through domestic silicon, stockpiled inventory, or looser enforcement — to actually convert that paused demand into revenue over the next 12-18 months. That's a geopolitical and supply-chain bet layered on top of a normal AI-growth bet, and it's one Anthropic and OpenAI simply don't have to make in the same way with comparatively open access to Nvidia's roadmap.
Combined, DeepSeek, Zhipu AI, MiniMax, and Moonshot had already crossed roughly $140 billion in combined valuation earlier in 2026, and Zhipu and MiniMax both went public on the Hong Kong exchange in January at $56 billion and $37 billion market caps, respectively. Moonshot's $50 billion pre-money target for its next round would put it ahead of both. Track how AI multiples are moving across labs on our AI Valuations Dashboard.
Bottom line: A 117x ARR multiple is a fair headline, but it's the wrong lens for a company that just turned away customers for lack of GPUs. The real question for anyone underwriting Moonshot AI's $35 billion price tag isn't whether the demand is real — the tripling ARR and the sixfold sales spike answer that. It's whether Moonshot and its state backers can out-execute US export controls on chip supply fast enough to convert that queue of paying customers into revenue before the next funding mark comes due.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗