AI Revenue Wars · 2022–2026 · read from SEC filings
Who is making money from AI? Tech's new dollars landed in the pipes, not the apps.
We read 1,583 numbers from the SEC filings of 94 companies and segments. In the last year, chips and cloud added $196.9B of revenue. Six whole software markets combined added $24.7B.
Quick answer
The companies selling the infrastructure. In the 12 months to Q2 2026, NVIDIA's data-center business brought in $277.8B, up +90% on the year and more than Google Search ($243.3B). AI chips and cloud added $196.9B of new revenue in a year; six application-software markets combined added $24.7B. The money behind it: Amazon, Microsoft, Alphabet, Meta and Oracle spent $691.0B on capex over the last 12 months. Every figure comes from the companies' own SEC filings.
| Figure | Value | Period | Type | Source |
|---|---|---|---|---|
| NVIDIA Data Center revenue (growth vs a year earlier) | $277.8B (+90%) | 12 months to Q2 2026 | Filed with the SEC | 10-Q, NVIDIA Data Center (2026-08-26) |
| Google Search & other revenue | $243.3B (+17%) | 12 months to Q2 2026 | Filed with the SEC | 10-Q, Google Search & other (2026-07-23) |
| Meta advertising revenue | $222.6B (+27%) | 12 months to Q2 2026 | Filed with the SEC | 10-Q, Meta advertising (2026-07-30) |
| Microsoft Cloud revenue | $214.4B (+27%) | 12 months to Q2 2026 | Filed with the SEC | 10-K, Microsoft Cloud (2026-07-29) |
| AWS revenue | $148.4B (+28%) | 12 months to Q2 2026 | Filed with the SEC | 10-Q, AWS (2026-07-31) |
| Google Cloud revenue | $77.6B (+58%) | 12 months to Q2 2026 | Filed with the SEC | 10-Q, Google Cloud (2026-07-23) |
| Big Tech capex (Amazon, Microsoft, Alphabet, Meta, Oracle) | $691.0B | 12 months to Q3 2026 | Computed from filings | 10-Q, Amazon (2026-10-30) · 10-Q, Microsoft (2026-10-28) · 10-Q, Alphabet (2026-10-29) · 10-Q, Meta (2026-10-22) · 10-Q, Oracle (2026-09-11) |
| NVIDIA data-center revenue from hyperscale customers | $48.7B (55% of Data Center) | Q2 2026, one quarter | Filed with the SEC | 10-Q, NVIDIA Data Center: Hyperscale (2026-08-26) |
| New revenue added by AI chips and cloud | $196.9B | Q2 2025 → Q2 2026 | Computed from filings | Company 10-Q/10-K filings (see Sources) |
| New revenue added by six application & data software markets | $24.7B | Q2 2025 → Q2 2026 | Computed from filings | Company 10-Q/10-K filings (see Sources) |
| Oracle capex per $1 of revenue | $1.05 | 12 months to Q3 2026 | Computed from filings | 10-Q, Oracle (2026-09-11) |
| Anthropic revenue, first half of the year | $16.3B (vs $1.2B a year earlier) | Six months to 2026-06-30 | Filed with the SEC | S-1, Anthropic (2026-10-26) |
| QQQ (Nasdaq-100) total return since ChatGPT launched | +184% | Dec 2022 → 2026-09 | Market data | Yahoo Finance · OpenAI, Nov 30 2022 |
Where the new money went
Who is making the most money from AI?
The pipes, not the apps. Every new dollar of revenue by company: the last 12 months (to Q2 2026) minus the 12 months before. Bigger box = more new dollars. Filed revenue only.
Source: SEC 10-K/10-Q filings (XBRL), segment lines where disclosed
The one causal chain we can see
How much is Big Tech spending on AI, and who gets the money?
Big Tech's capex is NVIDIA's revenue. Amazon, Microsoft, Alphabet, Meta and Oracle spend cash on data centers and chips; NVIDIA sells them the GPUs. Since fiscal 2027 NVIDIA reports how much of its data-center revenue comes from those hyperscalers, a direct disclosure of the link.
Quarterly capex (stacked bars) vs NVIDIA Data Center revenue (black line)
Green dots: the part NVIDIA itself attributes to hyperscale customers
Source: Cash-flow statements (purchases of property & equipment); NVIDIA revenue by market platform
Which moves first?
Correlation of quarter-over-quarter changes at different lags (22 quarters)
Strongest at NVIDIA leading by 1 quarter (r = 0.87). That fits payment timing: NVIDIA books revenue when it ships, while capex is counted when the cash is paid. Both series trend up, so treat this as timing, not proof.
Source: Computed from the series above
Capex as a share of revenue
Trailing 12 months: how much of each company's revenue goes back into infrastructure
Source: Capex ÷ filed revenue, same company
The great crossover
Is AI hurting software companies?
Software used to grow faster. Not anymore. Median year-over-year growth: 10 cloud and AI-infrastructure businesses vs 21 application and data software companies, plus the seven ad platforms.
Source: SEC filings; growth as each company reported it
Stocks vs revenue
Did the stock market price in AI before the revenue showed up?
Bars: one-year total return of QQQ (Nasdaq-100) and SPY (S&P 500) at each quarter end. Lines: how fast revenue actually grew. Dashed markers: dated events, each linked to its source.
Source: Yahoo Finance (dividend-adjusted monthly closes); SEC filings; event sources below
The leaderboard
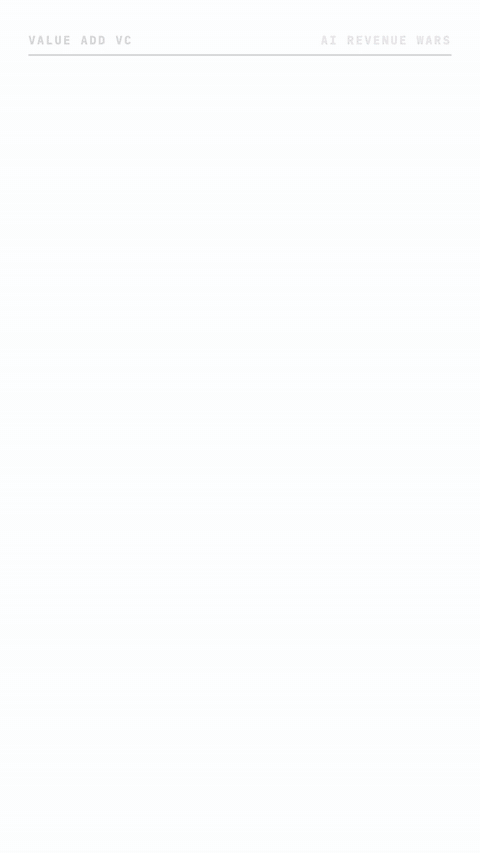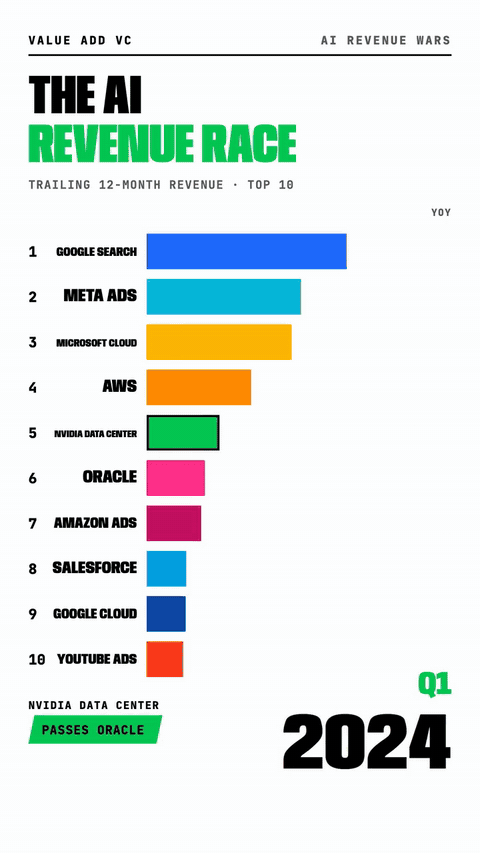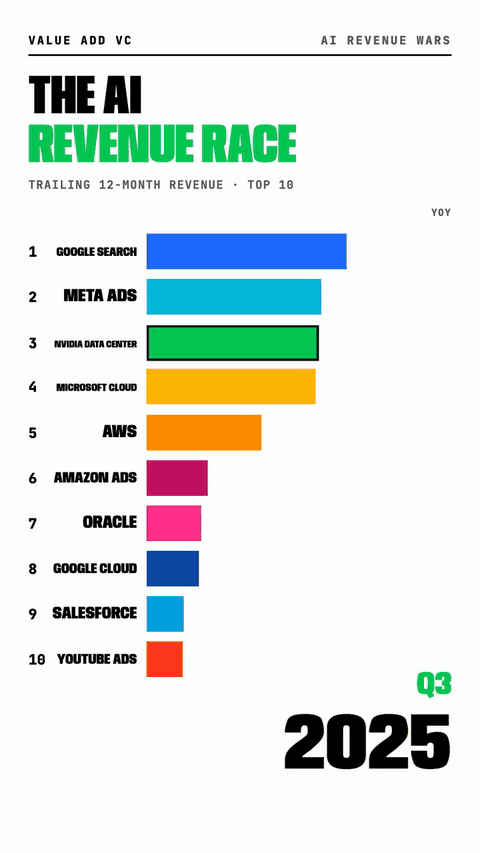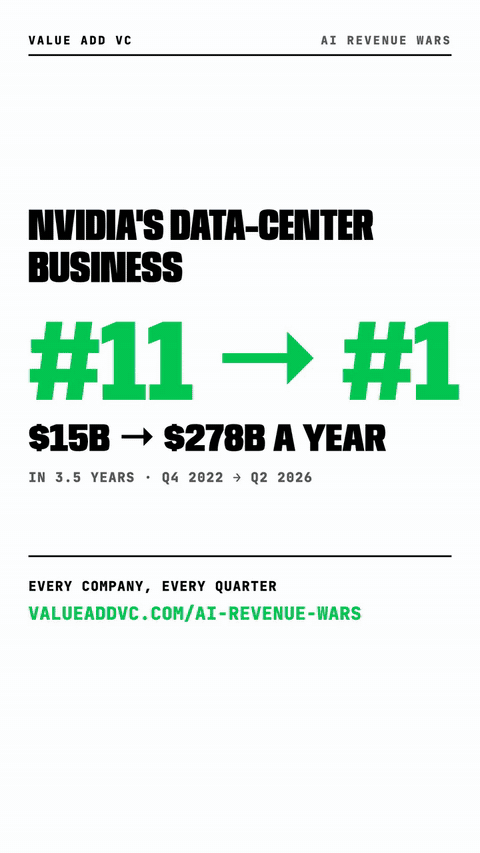
Which tech businesses make the most revenue? The race, quarter by quarter
Revenue over the last 12 months, for the biggest businesses we track. Segments replace their parent company where it reports them.
The private AI labs
How much revenue do OpenAI and Anthropic make?
Neither files with the SEC, so all we have are their own statements and media reports: annualized run-rates and ARR at a point in time, not revenue for a period. They are listed with their sources and never added to the filed numbers above.
| Company | Figure | What it measures | As of | Type | Source |
|---|---|---|---|---|---|
| Anthropic | $65.0B | Annualized run-rate Based on unnamed people familiar with the company. | 2026-07-31 | Reported by media | Bloomberg (via i3investor reprint) (2026-08-18) |
| OpenAI | $50.0B | Annualized run-rate Approximate figure. Checked against an excerpt of the source, not the full page. Net figure; the Financial Times reported it while correcting a higher, grossed-up estimate. | 2026-09-30 | Reported by media | Invezz (Financial Times) (2026-10-08) |
| Databricks | $7.0B | Annualized run-rate The source says “more than” this figure. | 2026-08-13 | Company-stated | Databricks (2026-08-13) |
| Cursor (Anysphere) | $4.0B | Annualized run-rate | 2026-06-08 | Reported by media | TradingKey reporting Forbes and Bloomberg (2026-06-08) |
| Canva | $4.0B | ARR | 2025-12-31 | Company-stated | TechCrunch (2026-02-18) |
| Zendesk | $2.0B | ARR Approximate figure. | 2025-12-02 | Company-stated | The AI Economy (2025-12-02) |
| Modal | $1.0B | Annualized run-rate | 2026-09-30 | Reported by media | Oossa (2026-10-14) |
| Cognition | $1.0B | Annualized run-rate | 2026-09-25 | Company-stated | Unite.AI reporting Cognition announcement (2026-09-25) |
| Fireworks AI | $1.0B | Annualized run-rate | 2026-07-15 | Company-stated | Fireworks (company blog) (2026-07-15) |
| Vercel | $600M | Annualized run-rate Based on unnamed people familiar with the company. | 2026-10-01 | Reported by media | Dealroom (2026-10-01) |
| Lovable | $600M | Annualized run-rate | 2026-09-24 | Company-stated | TechCrunch (2026-09-24) |
| Lambda | $520M | Revenue, TTM Oct 2024-Sep 2025 The source says “more than” this figure. | 2025-09-30 | Reported by media | Forge (2026-01-08) |
| Intercom | $400M | ARR | 2026-03-02 | Company-stated | Fin, formerly Intercom, CEO blog (2026-03-02) |
| Grafana Labs | $400M | ARR | 2025-09-30 | Company-stated | Grafana Labs (2025-09-30) |
| Glean | $300M | ARR | 2026-05-28 | Company-stated | Business Wire (Glean press release) (2026-05-28) |
| Fivetran | $300M | ARR | 2024-10-11 | Company-stated | Business in the News (2024-10-11) |
| Perplexity | $250M | Annualized run-rate | 2026-08-24 | Reported by media | The Business Perspective (2026-08-24) |
| ClickHouse | $250M | Annualized run-rate | 2026-05-27 | Company-stated | TechCrunch (2026-05-27) |
| Cohere | $240M | ARR Approximate figure. | 2025-12-31 | Company-stated | Tekedia (CNBC memo) (2026-02-14) |
| Sierra | $200M | ARR | 2026-05-31 | Reported by media | New Market Pitch (2026-10) |
| Chronosphere | $160M | ARR The source says “more than” this figure. | 2025-09-30 | Company-stated | Palo Alto Networks / SEC Form 8-K (2025-11-19) |
| Replit | $150M | Annualized run-rate | 2025-09-10 | Company-stated | TechCrunch (2025-09-10) |
| xAI | $107M | Revenue, Q3 2025 Checked against an excerpt of the source, not the full page. | 2025-09-30 | Reported by media | Okara (Bloomberg) (2026-01-10) |
| Decagon | $100M | Annualized run-rate | 2026-10-13 | Company-stated | PYMNTS (2026-10-13) |
| Clay | $100M | ARR | 2025-12-08 | Company-stated | Clay (2025-12-08) |
| Gamma | $100M | ARR | 2025-11-10 | Company-stated | Gamma (2025-11-10) |
| Sentry | $100M | ARR | 2024-05-15 | Company-stated | Sentry Blog (2024-05-15) |
| Webflow | $100M | ARR | 2022-03-16 | Company-stated | Silversmith Capital Partners (2022-03-16) |
| Framer | $50M | ARR | 2025-08-28 | Company-stated | TechCrunch (2025-08-28) |
| Bolt (StackBlitz) | $40M | ARR | 2025-03-03 | Company-stated | Growth Unhinged (2025-07-09) |
| Supabase | $20M | ARR | 2024-12-31 | Company-stated | Tech Startups (2025-10-03) |
| Company | Figure | What it measures | As of | Type | Source |
|---|---|---|---|---|---|
| Microsoft | $37.0B | AI business annual revenue run-rate Earnings-call figure; a run-rate, not recognized revenue. The source says “more than” this figure. | 2026-03-31 | Company-stated | Microsoft (2026-04-29) |
| AWS | $25.0B | AWS AI business annual revenue run-rate Amazon does not report AI revenue as a separate line; this is a run-rate from results coverage. The source says “more than” this figure. | 2026-06-30 | Reported by media | Zacks (summary of Amazon's Q2 2026 results) (2026-07-30) |
| Oracle | $7.4B | Oracle Cloud Infrastructure (IaaS) revenue, one quarter Quarterly revenue for fiscal Q1 2027, up 121% year over year. | 2026-08-31 | Reported by media | Oracle release (republished by Finviz) (2026-09-10) |
| Salesforce | $3.9B | Agentforce + Data 360 ARR ARR, not recognized revenue. Data 360 includes about $1.1B of Informatica Cloud ARR from an acquisition. | 2026-07-31 | Company-stated | Salesforce (2026-08-26) |
| Salesforce | $1.5B | Agentforce ARR The definition widened this quarter (now includes Slackbot and Headless 360), so the growth rate includes that change. | 2026-07-31 | Company-stated | Salesforce (2026-08-26) |
| Salesforce | $1.4B | Agentforce + Data 360 ARR ARR for a product group. Not comparable with Salesforce's recognized revenue. | 2025-10-31 | Company-stated | Salesforce Investor Relations |
| Adobe | $650M | AI-first ARR The dollar figure comes from earnings-call coverage; the release gives the growth rate. The source says “more than” this figure. | 2026-08-28 | Company-stated | Adobe (8-K exhibit copy) (2026-09-10) |
Every company's full history of figures is on its own page; product lines such as Claude Code or Databricks' AI products are listed there too, labelled as product figures.
Scale vs speed
Which tech companies are big and still growing fast?
Each bubble is a company or segment. Further right = more revenue (log scale). Higher = faster growth. Bigger = more dollars added. Tap a market to isolate it, or press play to watch 2022 → now.
Source: SEC filings
Breadth
How many tech companies are speeding up?
Each quarter: companies whose growth rate rose (green) or fell (red) by more than half a point vs the quarter before. Black line: share speeding up.
Source: SEC filings
Correlation
Which tech companies grow together, and which move opposite?
How closely each pair's growth rates rose and fell together, Q1 2022–Q2 2026.
Source: Computed from filed growth rates
- What the data shows
- Growth rates cluster: software with software, ads with ads, cloud with cloud.
- What it suggests
- Shared cycles (interest rates, budget cuts, then the AI build-out) moved whole groups at once. See section 04 for when each happened.
- What remains unknown
- Correlation isn't causation, and trending series overstate links. Nothing here shows one company's growth causing another's.
The whole picture
How fast is every tech company growing, quarter by quarter?
Year-over-year revenue growth by calendar quarter, grouped by market. Read across a row to see a company speed up or slow down.
Source: SEC filings; growth as each company reported it
Head-to-head
AWS vs Microsoft vs Google Cloud: who is winning?
Pick a fight: rivals in the same market, on the same axes. Pick a preset matchup or build your own (up to five).
What the record shows
Is AI taking budget from software incumbents?
Displacement needs evidence, not just a chart. Growth rates can't show a customer moving budget from one vendor to another, so this section lists only what customers, companies and surveys have said on the record, and whether they said AI was the reason.
| Market | From → to | What was said | Because of AI? | Type | Source |
|---|---|---|---|---|---|
| Customer support | Legacy support systems (phone menus, ticketing tools, CRM-based agents) → Decagon | “53% replaced legacy systems (IVRs, ticketing tools, CRM-based agents)” Decagon's own figure for its new customers; it does not name which vendors were replaced. | Yes | Vendor claim | Decagon (2026-01-30) |
| Customer support | Human support agents (outsourced) → Klarna's AI assistant | “it performed the work of 700 customer service agents and handled 2.3 million interactions in its first month of operation” Work equivalent to 700 agents, not 700 people laid off; Klarna later rehired some support staff. | Yes | Customer statement | Klarna (2024-02-27) |
| CRM & sales data | Salesforce (CRM) and Workday (HR) → Klarna's own consolidated stack | “We have a number of large internal initiatives that combine AI, standardization, and simplification to enable us to shut down several software-as-a-service providers” Klarna later clarified it consolidated onto an internal stack plus other software, rather than replacing these tools with an AI model. | Partly | Customer statement | Klarna (2024-09-12) |
| CRM & sales data | Seat-based ZoomInfo licenses → Data delivered through APIs and AI agents | “customers are stepping away from seat licenses, opting for data delivered via APIs, Claude, and similar AI-driven setups” Reported from the earnings call, not the filing; ZoomInfo cut its 2026 revenue guidance in the same quarter. | Yes | Company disclosure | ZoomInfo CEO, Q1 2026 earnings call (2026-05-12) |
| Developer tools | GitHub Copilot → Cursor | “Most of the team runs Cursor as the primary IDE tool.” One small team, and a partial switch: two developers kept Copilot. | Yes | Customer statement | A small software team (Innovatrix Infotech) (2026-07-13) |
| Developer tools | Buying software products → Building them in-house with AI | “32% have decided against buying at least one software product because they could build it in-house” Self-reported survey answer, via a summary of the report; it doesn't say which products were skipped. | Yes | Survey | McKinsey State of AI 2026 (1,719 respondents) (2026-06) |
| All markets | External contractors and consultants → AI spending | “When the gap is funded by reallocating within IT, external labor is cut first: 60.9% of the 297 reallocating organizations reduce external contractors and consultants.” Money moving from services to AI, not from one software vendor to another. | Yes | Survey | Futurum Group CIO survey (1,636 respondents) (2026-09-10) |
| Website building | Webflow → Framer | “So we've bit the bullet and moved our entire marketing site from Webflow to Framer.” The stated reason is real-time collaboration, not AI. | No | Customer statement | Superthread (3-person team) (2025-07-11) |
| Design | Adobe Creative Cloud → Canva | “When I finally decided to part ways with Adobe, I was determined to find tools that were easier to use and hopefully cheaper.” One person, undated page; the reasons given are price and ease of use, not AI. | No | Customer statement | A solo business owner |
| Observability | Datadog → Self-hosted open-source tools (Prometheus, Grafana) | “Replaced $6,000/month Datadog with $5/month VM + open-source stack.” One small deployment; the switch was about cost, not AI. | No | Customer statement | A developer running 40 hosts (2026-10-19) |
What this shows
- Named examples exist in support (Klarna), coding (Copilot to Cursor) and sales data (ZoomInfo seat compression), but they are individual cases and vendor claims, not market-wide measurements.
- Surveys point the same way: companies say they build instead of buy, and fund AI by cutting contractors first.
- Several well-known switches (Webflow to Framer, Adobe to Canva, Datadog to open source) were about price or collaboration, not AI.
Still unknown
- How much money has actually moved: none of the filings or surveys we found puts a market-wide dollar figure on displacement.
- We found no named customer that has publicly moved from a hyperscaler to an AI cloud; the GPU clouds' growth so far appears to be new spending.
- How much of the private AI labs' revenue goes straight back into cloud compute.
Explore
Which tech companies are growing fastest right now?
Pick a quarter and a market, then sort by growth, acceleration or dollars added. Every row links to its SEC filing. Export to CSV.
More: markets · revenue flows · landscape · earnings timeline · all 928 sources · findings report · methodology
The takeaway Every number on this page is computed from filings at build time. When a company files a new quarter, the page updates on the next data refresh.
Methodology & sources
Where do these numbers come from?
Every figure carries its source, its date and what kind of figure it is: filed with the SEC, computed from filings, company-stated, reported by media, or an estimate.
How the numbers are made
- Public companies: revenue and capex are read from each company's own 10-Q and 10-K filings with the SEC (XBRL), including business segments such as AWS, Google Cloud and NVIDIA Data Center.
- As first reported: each quarter keeps the value first filed; growth is the company's own comparison in the same filing. When a company restates history (for example after selling a business), figures that would mix the two versions are left out.
- Fourth quarters are usually derived as full-year revenue minus the first nine months, and marked as derived.
- Private companies report ARR or annualized run-rates, not revenue filed with the SEC. They are shown with their source and label and never added to filed revenue.
- Correlation is not causation. The only causal link stated is one a company discloses itself (NVIDIA's revenue from hyperscale customers).
Sources
- 803 SEC filings (10-Q and 10-K, via SEC EDGAR), each linked from the figures it supports.
- Company statements and media reports for private companies, labelled company-stated, reported by media or estimate.
- Yahoo Finance for QQQ and SPY dividend-adjusted prices.
- Dated events from the Federal Reserve, OpenAI and NVIDIA, each linked.
All 928 sources · Findings report · Earnings timeline
Data last refreshed 2026-10-30; latest filing 2026-10-30. Factual market research, not investment advice.