
In 2026, the traditional IPO is winning on capital: $114.2 billion raised across 65 U.S. IPOs in the first half of the year dwarfs the $20.9 billion SPACs raised across 118 deals, and SpaceX's record $85.7 billion IPO in June 2026 priced its underwriting fee at just 0.7% — lower than any SPAC's all-in cost.
Three years after the SPAC bubble burst — 2021 saw 613 SPAC IPOs raising $162B, a number that collapsed to under 100 deals a year by 2024 — founders again have a real choice about how to go public. SPAC deal count has climbed back in 2026, but the dollars tell a different story: as of the first half of the year, traditional IPOs pulled in more than five times the capital SPACs did. The headline fee is still the least important number in the decision.
SPAC vs IPO vs Direct Listing 2026: The Side-by-Side Comparison
A SPAC, a traditional IPO, and a direct listing are three distinct ways to go public. In H1 2026, traditional IPOs raised $114.2 billion across 65 deals, SPACs raised $20.9 billion across 118 deals, and direct listings raised almost no new capital. Here's how the three compare on what actually decides the outcome.
| Attribute | Traditional IPO | SPAC (de-SPAC) | Direct Listing |
|---|---|---|---|
| Underwriting / banker fee | ~7% typical; mega-deals compress fast (SpaceX paid 0.7%) | ~5.5% all-in (2% upfront + 3.5% deferred) | $0 underwriting ($20M-$40M advisory for a large co.) |
| H1 2026 U.S. deal count / capital raised | 65 deals / $114.2B | 118 deals / $20.9B | A handful of listings; little to no capital raised |
| Share of U.S. IPO deal volume, Q2 2026 | ~46% | ~54% (down from 69% in Q1 2026) | Under 1% |
| Hidden cost / dilution | IPO pop (avg 15-20% first-day) | 20% sponsor promote + warrants | None structurally |
| Time to public | 6-9 months | 3-6 months once a target is found | 4-6 months |
| Lockup period | 180 days typical | ~180 days (often negotiated shorter) | Often none — insiders can sell day one |
| Raises new (primary) capital? | Yes | Yes, if redemptions stay low | Usually no (a primary variant exists, adoption thin) |
| Named 2026 example | SpaceX (SPCX) — $85.7B raised, June 2026 | Horizon Quantum / dMY Squared (HQ) — $503M valuation, March 2026 | Virtuix Holdings (VTIX) — ~$221M valuation, January 2026 |
Sources: FTI Consulting, IPO & SPAC Market Update Q2 2026; SEC EDGAR company filings; company press releases; as of September 2026.
SPAC vs IPO vs Direct Listing: The Numbers That Matter
FTI Consulting IPO & SPAC Market Update, Q2 2026; SEC EDGAR; company filings, as of September 2026
Data
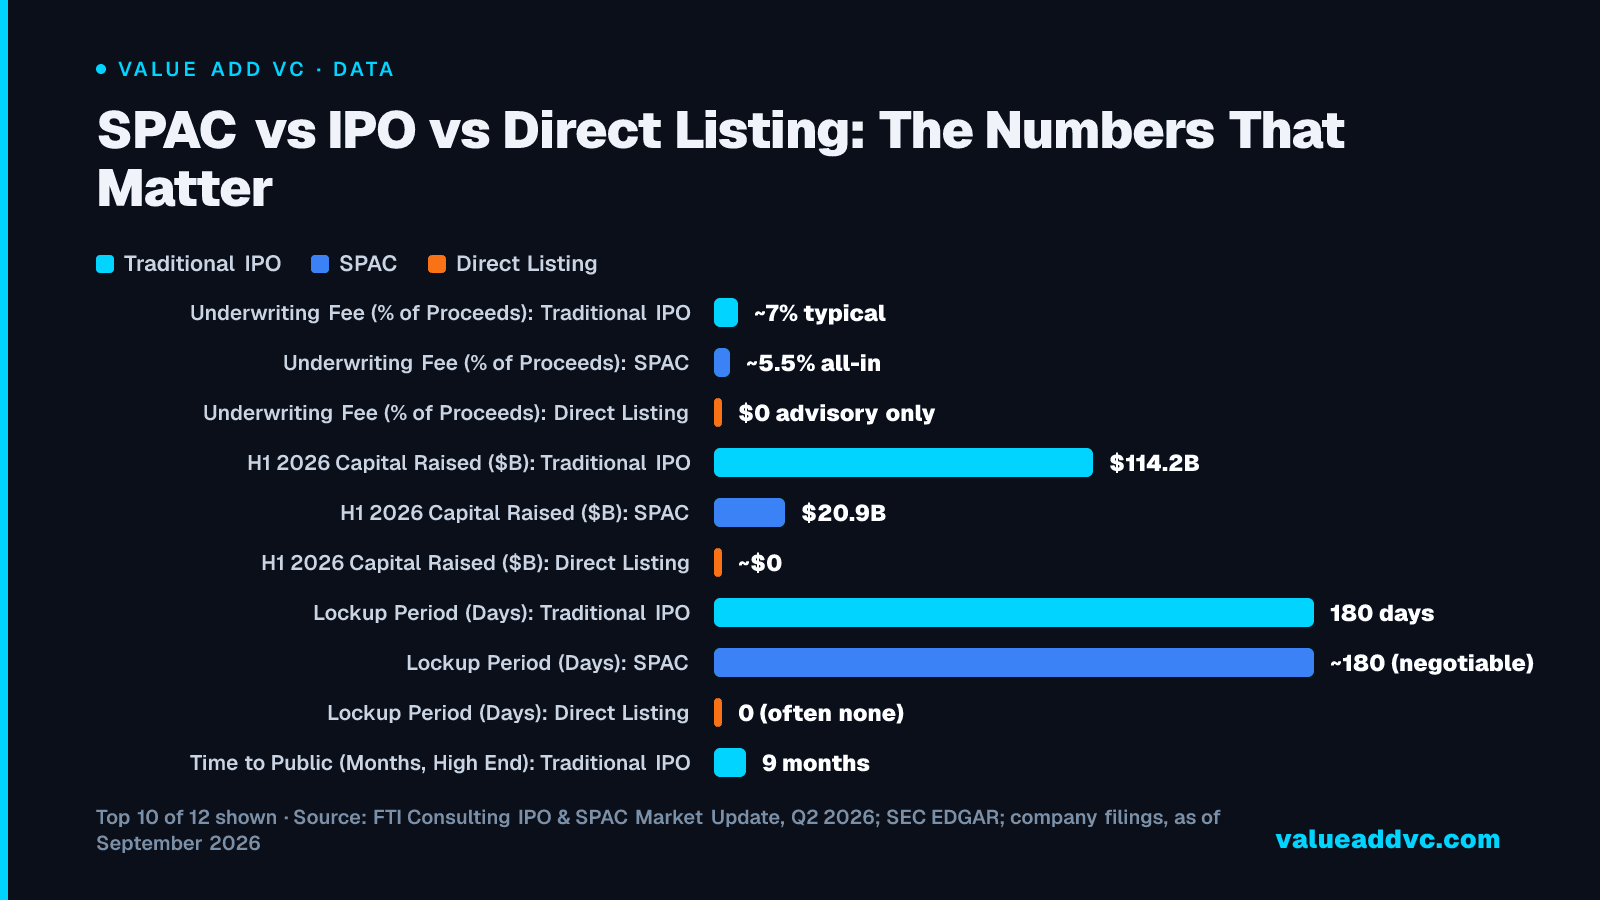
Traditional IPOs raised more than five times what SPACs did in H1 2026 — but at scale, even the highest-fee path can undercut a SPAC's headline rate.
The Traditional IPO: Expensive on Paper, Cheap at Scale
The traditional IPO still charges the most explicit fee of the three paths for a typical company — roughly 7% of gross proceeds, a spread that has barely moved in three decades according to Jay Ritter's IPO underwriting data at the University of Florida. But that headline number breaks down completely at the top of the market. SpaceX's initial public offering closed on Nasdaq on June 15, 2026, with gross proceeds of $85.7 billion after underwriters exercised their full over-allotment option — reportedly the largest IPO in history, and one where the Hawthorne, California-based company negotiated its underwriting fee down to just 0.7%, or about $646M split among Goldman Sachs, Morgan Stanley, and the rest of the syndicate.
That fee compression is a scale story, not a market-wide one: most 2026 IPO class members still paid closer to the standard spread. Klarna (listed September 2025) and Chime (listed June 2025 at an $11.6 billion valuation, less than half its $25 billion private-market peak from 2021) went public the year before, and Cerebras raised $5.55B at a $56.43B valuation in its May 2026 Nasdaq debut — none of them got SpaceX's terms. For a company that needs $100M-$500M and wants a syndicate that builds an institutional order book and supports the stock in the aftermarket, the underwritten IPO remains the only path that reliably delivers both. Track the live IPO class on the Tech IPO dashboard.
The SPAC in 2026: Volume Is Back, Dollars Aren't
SPACs are genuinely more active in 2026 than at any point since the 2021 peak: 118 SPAC IPOs raised $20.9 billion in the first half of the year, up from 66 deals and $11.8 billion over the same stretch of 2025, with 359 SPACs still outstanding and hunting for targets as of August 2026. In Q1 2026, SPAC formations briefly made up 69% of all U.S. IPO deal count before falling to 54% in Q2 as traditional issuance recovered. But deal count isn't dollars — SPACs raised barely a fifth of what traditional IPOs did over the same six months, and the structure still hides two costs that the headline 5.5% banker fee doesn't capture.
The 20% sponsor promote
Sponsors get roughly 20% of the post-merger equity for a nominal investment — pure dilution to your shareholders before any new money arrives.
Redemption risk
De-SPAC redemption rates topped 80% in 2022-2023, so a $300M shell often delivered under $60M in actual cash to the target.
Warrant overhang
Public and founder warrants create a dilutive ceiling on the stock that pressures the price for years post-merger.
Post-2024 SEC disclosure rules
Tighter disclosure requirements narrowed the forward-projection advantage that was much of the original SPAC pitch.
Where the SPAC genuinely wins: Singapore-based Horizon Quantum Computing, a pre-revenue quantum-software developer that a traditional bookbuild would have struggled to price, completed its merger with dMY Squared Technology Group at a $503 million valuation and began trading on Nasdaq under ticker "HQ" on March 20, 2026, raising roughly $120M. That's the SPAC's real lane in 2026: pre-revenue or hard-to-underwrite companies with a committed sponsor and a locked PIPE, not a cheaper alternative to a mainstream IPO.
The Direct Listing: Cheapest Fees, Still No Cash
A direct listing is the cheapest path on fees and the most honest on price discovery. Spotify (2018), Slack (2019), Coinbase (2021), and, in 2026, Austin, Texas-based VR treadmill maker Virtuix Holdings all proved the model works for the right company: float existing shares directly on the exchange, let a market auction set the open, and skip the underwriting spread entirely. Virtuix began trading on Nasdaq under ticker "VTIX" on January 27, 2026, in a listing valued at roughly $221 million based on its prior volume-weighted share price, according to Renaissance Capital's IPO tracking — and it raised zero new primary shares in the listing itself, instead pairing the debut with a separate $11M PIPE and a $50M equity line of credit.
That Virtuix structure is the tell: even in 2026, the exchanges' primary-capital direct-listing rules exist on paper, but adoption remains thin because companies that need cash still prefer the price certainty of a bookbuild or the negotiated terms of a SPAC. Direct listings work for a narrow band of companies — already known well enough, or willing to pair the listing with a side financing, that they don't need underwriters to generate demand. Compare exit outcomes against fund returns on the VC Performance dashboard.
What the Headline Misses
The $114.2B-vs-$20.9B gap between traditional IPOs and SPACs in H1 2026 looks decisive, but a huge share of that traditional-IPO total is one deal: SpaceX's $85.7B raise alone is close to three-quarters of all traditional IPO capital for the half. Strip that single mega-deal out and the two paths' dollar totals move a lot closer together, even as SPAC deal count still trails on capital delivered per deal.
The SPAC redemption and quality risks that sank the 2021 class haven't disappeared either — they're just less visible while deal count is climbing. And the fee-percentage story cuts both ways: SpaceX's 0.7% is a scale artifact, not a preview of what a $150M growth company will pay next year. Most companies still choosing a traditional IPO in 2026 are paying close to the standard 7% spread, not SpaceX's rate.
SPAC vs IPO vs Direct Listing: How to Choose in 2026
Choose a traditional IPO if
- ✓ You need $100M+ in fresh primary capital
- ✓ You want a committed institutional book and aftermarket support
- ✓ Your story underwrites cleanly without forward projections
- ✓ You can absorb the ~7% fee and 180-day lockup
Choose a SPAC if
- ✓ You're pre-revenue or hard to underwrite via a bookbuild
- ✓ You have a committed sponsor and a locked-in PIPE
- ✓ You want to close faster once a target/shell is matched
- ✓ You accept the 20% promote and redemption risk
Choose a direct listing if
- ✓ You need little or no new capital right now
- ✓ Your brand already generates retail demand
- ✓ You want existing holders free to sell with no lockup
- ✓ You'd rather pair a side PIPE than pay an underwriting spread
In concrete terms: a well-capitalized company with a clean growth story and a $100M+ capital need should run a traditional IPO. A pre-revenue or hard-to-underwrite company that already has a sponsor and a locked PIPE lined up should consider a SPAC, but should model the 20% promote and redemption risk before signing. A brand-name company with an insider-heavy cap table and no real capital need should run a direct listing, ideally paired with a modest PIPE if it wants any new cash at all.
The 7% IPO fee is the one you see. The 20% SPAC promote, the zero-dollar direct listing, and SpaceX's 0.7% outlier are the ones that actually decide the outcome.
In 2026, the traditional IPO still wins on dollars raised for almost everyone who actually needs the money.
Track the 2026 IPO class on the Tech IPO Tracker at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗