
Entrata filed a public S-1 on May 28, 2026, disclosing $509.3 million in fiscal 2025 revenue and $51 million in real GAAP net income — a rare thing among this year's private-equity-backed software IPO candidates: a company that is genuinely, not just adjusted-EBITDA, profitable.
The Lehi, Utah-based multifamily property management software company is targeting a NYSE listing under ticker ENT, with Goldman Sachs, J.P. Morgan, and Barclays running the deal. As of October 22, 2026, Entrata has filed two amendments since its original S-1, the latest an S-1/A dated September 1, 2026 — but still has not set a price range, share count, or trading date. Here is what the filing actually discloses, how Entrata's growth and margins compare to its closest public comp, and what it could realistically be worth.
Entrata IPO Key Numbers (as of October 22, 2026)
| Date | Event | Figure | Source |
|---|---|---|---|
| May 28, 2026 | Public S-1 filed (NYSE: ENT); no price range | — | SEC EDGAR |
| Sep 1, 2026 | S-1/A Amendment No. 2, financials through June 30, 2026 | — | SEC EDGAR |
| H1 2026 | Revenue, +23% from $238.8M in H1 2025 | $294.6M | S-1/A; Utah Money Watch |
| H1 2026 | Net income (vs $11.9M in H1 2025) | $44.9M | S-1/A; Utah Money Watch |
| Q2 2026 | Revenue +24%; net income $21.6M vs a $2.0M loss in Q2 2025 | $151.1M | S-1/A; Utah Money Watch |
| FY2025 | Revenue (+24%) and net income | $509.3M / $51M | S-1 |
| Oct 22, 2026 | No filing after the Sep 1 S-1/A; price range, share count, proceeds and trading date still blank | Not priced | SEC EDGAR filing index (own check) |
The $4.3 billion Blackstone mark (May 2025) is a private valuation, not an IPO price. Entrata has not disclosed an implied IPO valuation.
What Entrata Actually Does
Entrata sells a unified operating system for multifamily property owners and operators — leasing, resident payments, renewals, maintenance, resident experience, and AI-supported workflows in a single platform, embedded with payments rather than bolted on. Founded in 2003 and based in Lehi, Utah, the company's S-1 filing with the SEC discloses that its software runs roughly 2.5 million rental units, about 10% of the entire US multifamily market, and that 4 of the National Multifamily Housing Council's top-10 operators are Entrata customers.
Silver Lake has held majority control of Entrata since 2022. In May 2025, Blackstone led a $200 million minority investment that valued the company at $4.3 billion, according to Entrata's own announcement of the round — the reference point every IPO valuation conversation about the company starts from.
Inside the S-1: Real Revenue Growth, Real Profit
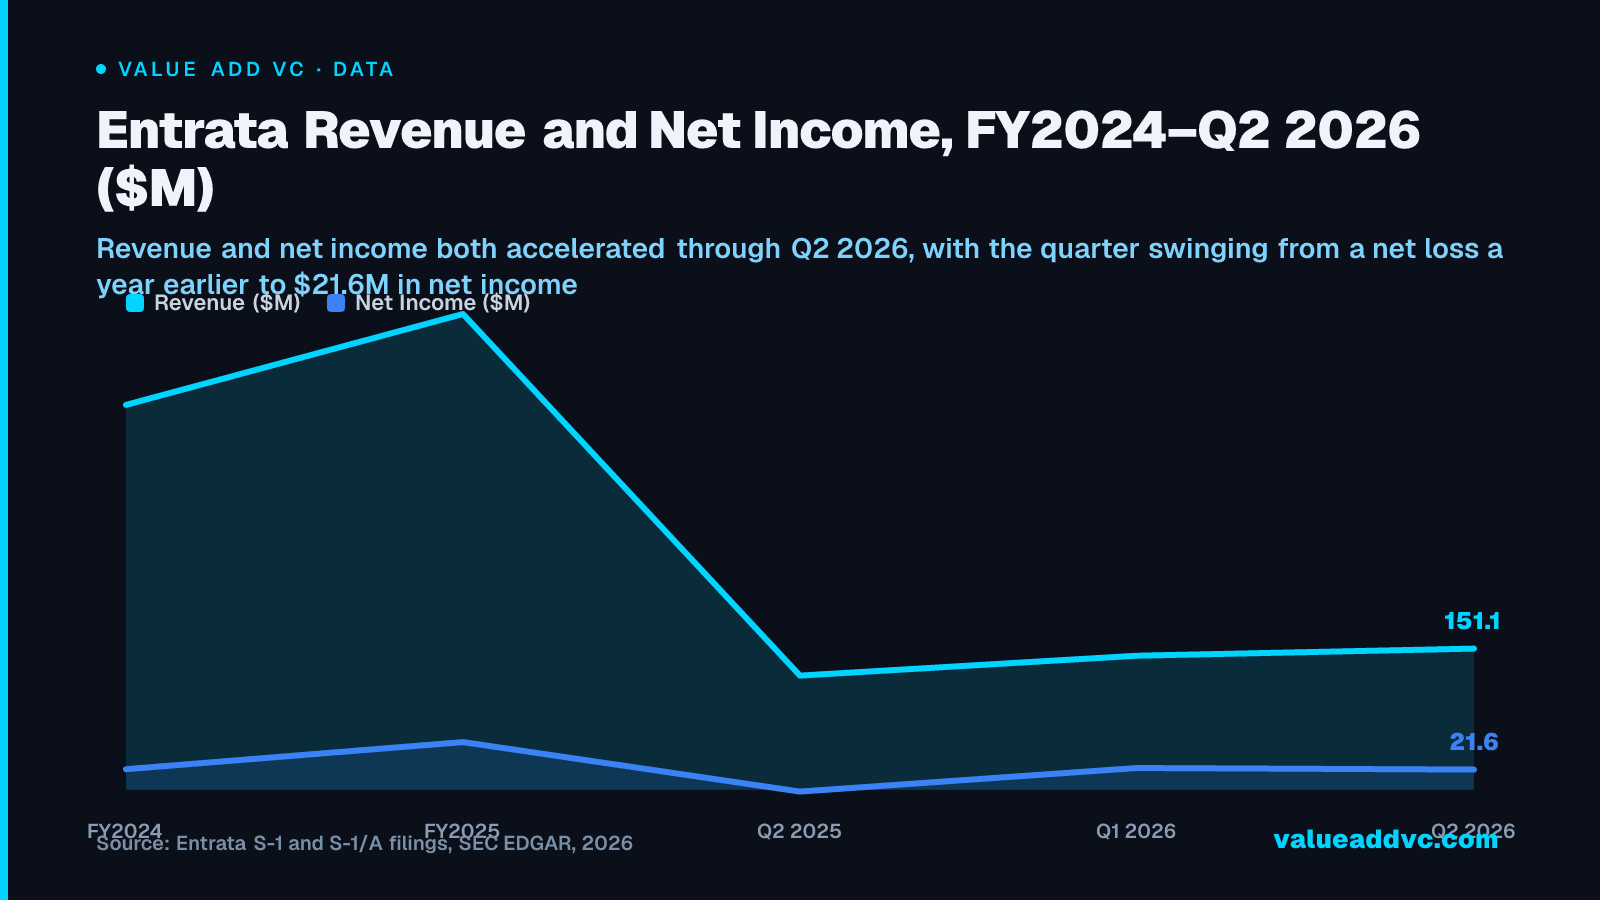
What stands out in Entrata's filing is that the profitability is not a non-GAAP adjustment. Per reporting on the filing, fiscal 2025 revenue was $509.3 million, up from $412.0 million in fiscal 2024 — about 24% growth — with GAAP net income of $51 million, up from $22 million the year before. The momentum continued into 2026: for the three months ended March 31, 2026, Entrata reported $143.5 million in revenue and $23.3 million in net income, versus $116.6 million in revenue and $13.9 million in net income for the same quarter of 2025, roughly 23% revenue growth and a 67% jump in quarterly net income.
Entrata's annual recurring revenue sits at approximately $574–575 million, per SaaStr's analysis of the S-1, also growing 23% year over year — consistent growth across both the ARR and GAAP revenue lines is a cleaner story than several other 2026 PE-backed software candidates, where SaaStr's own analysis notes growth has been decelerating heading into their IPOs.
Entrata's third filing, an S-1/A dated September 1, 2026, shows the trend holding into the second quarter: six-month 2026 revenue of $294.6 million, up 23.4% from $238.8 million in the same period of 2025, and six-month net income of $44.9 million, up from $11.9 million. The second quarter alone swung from a $2.0 million net loss in Q2 2025 to $21.6 million in net income on $151.1 million of revenue in Q2 2026 — the clearest sign yet that the profitability isn't a one-quarter anomaly.
Entrata Revenue and Net Income, FY2024–Q2 2026 ($M)
Revenue and net income both accelerated through Q2 2026, with the quarter swinging from a net loss a year earlier to $21.6M in net income
Entrata S-1 and S-1/A filings, SEC EDGAR, 2026
Data
| Item | Revenue ($M) | Net Income ($M) |
|---|---|---|
| FY2024 | 412 | 22 |
| FY2025 | 509.3 | 51 |
| Q2 2025 | 122.2 | -2 |
| Q1 2026 | 143.5 | 23.3 |
| Q2 2026 | 151.1 | 21.6 |
What Entrata Could Be Worth
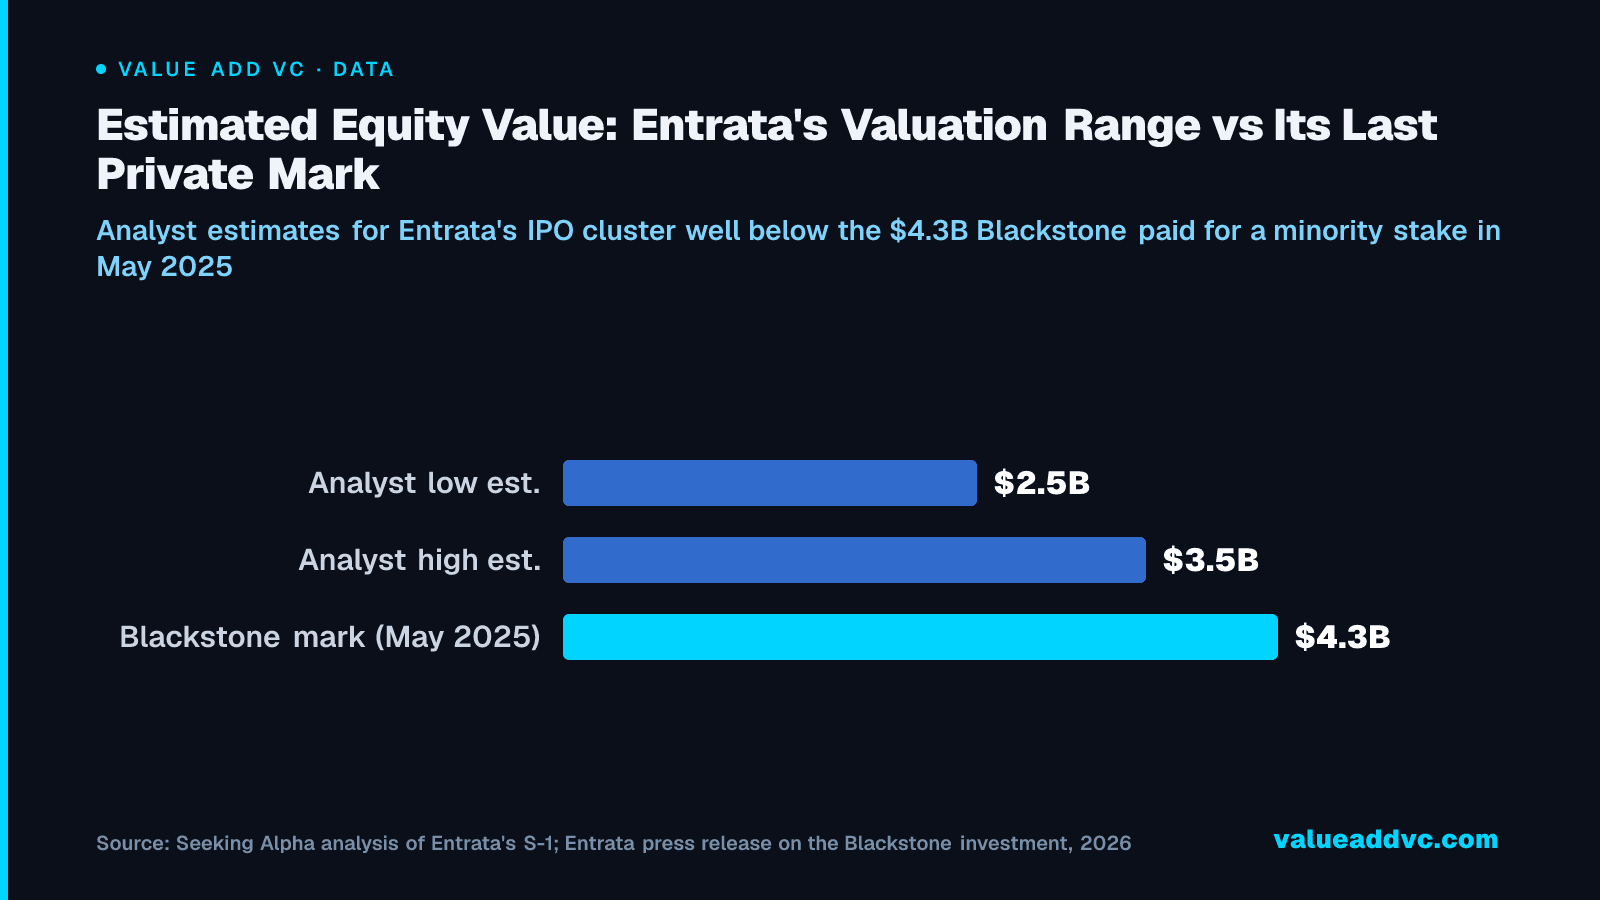
The $4.3 billion figure from Blackstone's 2025 investment is a private mark, not a promised IPO price, and the gap between the two matters here. Per Seeking Alpha's coverage of the offering, analysts estimate Entrata could land in a $2.5–3.5 billion equity value range at IPO, or roughly 4.5x to 5.5x trailing revenue — below the multiple its closest public comp currently trades at.
| Metric | Entrata (IPO pending) | AppFolio (NASDAQ: APPF) |
|---|---|---|
| Status | Private, S-1 filed May 28, 2026 | Public since 2015 |
| Trailing revenue | $509.3M (FY2025) | ~$1.04B (TTM, through Jun 2026) |
| Revenue growth | ~24% YoY (FY25), 23% (Q1 2026) | ~20.7% YoY (TTM) |
| Profitability | $51M GAAP net income (FY25) | 25.5–27.5% non-GAAP operating margin (2026 guide) |
| Market value | Est. $2.5–3.5B at IPO (analyst est.) | $7.23B market cap (Aug 2026) |
| Price-to-revenue multiple | ~4.5–5.5x (est.) | ~6.95x (TTM) |
| Primary market | Multifamily (2.5M units, ~10% of US market) | Multifamily, single-family, student, affordable housing |
Sources: Entrata S-1/S-1A filings via SEC EDGAR; Seeking Alpha analysis of the Entrata offering; AppFolio TTM revenue and market cap via StockAnalysis.com and MacroTrends, data through August 2026. Entrata figures are pre-IPO estimates, not a confirmed offering price.
Estimated Equity Value: Entrata's Valuation Range vs Its Last Private Mark
Analyst estimates for Entrata's IPO cluster well below the $4.3B Blackstone paid for a minority stake in May 2025
Seeking Alpha analysis of Entrata's S-1; Entrata press release on the Blackstone investment, 2026
Data
| Item | Value |
|---|---|
| Analyst low est. | $2.5B |
| Analyst high est. | $3.5B |
| Blackstone mark (May 2025) | $4.3B |
Where We Could Be Wrong
The $2.5–3.5 billion range cited above is an analyst estimate built before the deal priced, not a number Entrata or its underwriters have confirmed — S-1 and S-1/A filings routinely omit share count and price range until much closer to the roadshow, and Entrata's own filings still do. It's also possible the market prices Entrata closer to, or above, the $4.3 billion Blackstone mark: real GAAP profitability at a company's scale is genuinely rare among 2026's software IPO class, and a profitable, 23%-growth vertical SaaS business could justify a premium to the discount implied by the analyst estimate here, especially if it's well received the way Oura's September 2026 filing was. Conversely, if public appetite shifts toward profitability over growth, Entrata could land at the low end or below — a pattern we saw with other infrastructure suppliers in late September 2026. The AppFolio comparison also has limits — AppFolio serves a broader property-management footprint (single-family, student, affordable housing) beyond Entrata's multifamily focus, so the two aren't a perfect apples-to-apples multiple comparison, just the closest public one available.
What This Means for the 2026 IPO Window
Entrata lands in a busy year for 2026's IPO pipeline, but its profile is unusual within it: a 23-year-old, cash-generative company rather than a recent unicorn burning cash toward an eventual break-even. That makes it a useful test case for how public markets price real profitability versus the growth-at-all-costs multiples still common among AI-era startups. A pricing meaningfully above the $2.5–3.5 billion analyst range would be a signal that public investors are willing to pay up for vertical SaaS profitability again; a pricing near or below it would suggest the market is still discounting PE-controlled software companies relative to venture-backed ones, regardless of margin quality.
For founders and investors in the proptech space specifically, Entrata's numbers are also a data point worth filing away: a company with a 23% growth rate and double-digit net margins, serving a single vertical at meaningful market share, can still get discounted below a faster-growing but less profitable public comp on a revenue multiple basis — a reminder that growth rate alone doesn't set the multiple once profitability is real and comparable. Compare Entrata's multiples to other SaaS companies using our SaaS valuations dashboard, and track Entrata's IPO progress on the tech IPO tracker.
$51 million in real net income, on $509 million of revenue.
Entrata is the rare 2026 IPO candidate that doesn't need an adjusted-EBITDA slide to make its profitability case.
Track the 2026 listing calendar on our tech IPO calendar at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗