

Datadog reported $1.20 billion of revenue in its latest quarter, up 35% year over year, then guided the next quarter roughly flat. It disclosed in August 2026 that its largest customer had started using the platform less. Together, those facts are the story of Datadog in 2026.
Updated Nov 4, 2026: Datadog's third-quarter release reported $1,197 million of revenue, up 35%, above its own $1.135 billion to $1.145 billion guide, and raised 2026 guidance to $4.515 billion to $4.525 billion. But its fourth-quarter guide of $1.19 billion to $1.20 billion is roughly flat with Q3, and the stock closed down 14.4% at $188.72 that day. The figures below now run through September 30, 2026 where the release covers them.
This profile is built on Datadog's SEC filings and earnings releases. Where a figure comes from media reporting instead of a filing, including the August 2026 report about Palo Alto Networks, it is labeled that way.
Datadog in 2026: Company Snapshot
Datadog (NASDAQ: DDOG) is a New York-based observability and security software company that reported $1.20 billion of revenue for the quarter ended September 30, 2026, up 35% year over year, with about 4,860 customers paying $100,000 or more a year (about 33,400 customers in total at June 30, the latest count filed). It guides to $4.515 billion to $4.525 billion of 2026 revenue and generated $251 million of free cash flow in the quarter.
Sources: Datadog Q3 2026 earnings release, Q2 2026 earnings release, Q2 2026 Form 10-Q and Investing.com (market cap as of August 26, 2026).
Incorporated
June 2010; Nevada corporation since April 2026
Headquarters
New York, NY
Co-Founders
Olivier Pomel (CEO), Alexis Lê-Quôc (CTO)
Employees
~8,100 in 35 countries (Dec 31, 2025)
IPO
September 2019 at $27.00 per share
FY2025 Revenue
$3.43B (+28%)
What Datadog Actually Does
Datadog sells observability: software that watches other software. Its platform combines “metrics, traces, logs, user sessions, security signals, and other data from a single agent and over 1,000 integrations,” per its fiscal 2025 annual report, so engineers can see when an application slows down, trace the cause and fix it.
It started in infrastructure monitoring and added a product line almost every year: APM in 2017, Log Management in 2018, Cloud SIEM in 2020, LLM Observability in 2024, and OnCall and the Bits AI SRE agent in 2025, according to the same filing. It now sells more than 20 products to about 32,700 customers (at the end of 2025) in over 160 countries, and 29% of 2025 revenue came from outside North America.
How Datadog Makes Money
Datadog sells metered subscriptions. Customers commit to an amount of usage on monthly, annual or multi-year terms, and above that commitment “they are charged for their incremental usage,” with a different unit of measure for each product, the 10-K explains. We compare that hybrid model across public software in our piece on the shift to usage-based pricing.
List prices are public: Infrastructure Monitoring Pro starts at $15 per host per month billed annually ($18 on demand), Enterprise at $23, APM at $31 per host and log ingestion at $0.10 per GB, per Datadog's pricing page. Every product is a separate meter, which is what makes the land-and-expand model work.
At the end of 2025, about 84% of customers used two or more products, 33% used six or more and 18% used eight or more. Existing customers drove about 75% of 2025's revenue increase, and trailing 12-month dollar-based net retention was about 120%. Our net revenue retention explainer covers why that metric moves valuations.
Funding History: From IPO to $5.2B of Cash and Securities
Through its IPO year, Datadog financed itself “primarily through sales of subscriptions and the net proceeds we have received from sales of equity securities,” per its fiscal 2019 annual report. We have not sourced the pre-IPO venture rounds to a filing, so they are omitted here.
| Event | Date | Detail |
|---|---|---|
| IPO | Sep 2019 | 27.6M shares at $27.00 (incl. 3.6M option shares); $705.9M net proceeds |
| 2029 convertible notes | Dec 12, 2024 | $1.0B principal |
| Cash and marketable securities | Sep 30, 2026 | $5.2B |
Sources: Datadog FY2019 10-K, FY2025 10-K and Q3 2026 release.
Operations now fund the company: $1,050 million of operating cash flow and $915 million of free cash flow in 2025, a 27% margin, per the fourth-quarter release.
Product Portfolio
Pomel framed 2026 around “Observability, Security, Software Delivery, Service Management, and Product Analytics” in the February 2026 release. Highlights, from the 10-K and 2025-2026 releases:
Observability
Infrastructure, APM, Logs
The original core: hosts, containers, traces and log search.
GPU Monitoring, Data Observability
GPU fleet health and cost (GA Q1 2026); data-quality monitoring (GA Q4 2025).
Security
Cloud SIEM
Threat detection since 2020, now with the Bits AI Security Analyst agent.
AI Guard
Protects AI agents from prompt injection and poisoning (DASH 2026).
Software Delivery and Service Management
OnCall and Incident Management
Paging and incident workflows; OnCall launched in 2025.
Feature Flags
Generally available as of Q4 2025.
Product Analytics and AI Agents
Product Analytics, Experiments
Behavior analytics plus in-platform A/B testing (Experiments launched Q1 2026).
Bits AI, MCP Server
AI agents and assistants, plus governed data access for AI coding tools (Bits AI SRE GA Q4 2025; MCP Server GA Q1 2026).
Datadog says it shipped over 400 new features and capabilities in 2025, and its Q2 2026 release counts more than 100 new capabilities launched at DASH in June 2026. Gartner named it a Leader in the Magic Quadrant for Observability Platforms for a sixth consecutive year.
The Acquisition Playbook: Small Tuck-Ins, From Quickwit to Adaptive ML
Datadog buys small teams to fill product gaps. These are the five deals since January 2025 we could source to its own announcements; it disclosed terms for none.
| Company | Announced | What it does (per Datadog) |
|---|---|---|
| Quickwit | Jan 9, 2025 | Open source, cloud-native search engine for logs |
| Metaplane | Apr 23, 2025 | End-to-end data observability platform |
| Eppo | May 5, 2025 | Feature flagging and experimentation platform |
| Propolis | Jan 28, 2026 | Autonomous QA testing platform |
| Adaptive ML | Jun 30, 2026 | Reinforcement Learning Operations (RLOps) platform |
Sources: Datadog announcements for Quickwit, Metaplane, Eppo, Propolis and Adaptive ML.
The filings supply the dollar totals. The 10-K reports three acquisition agreements in 2025 at an aggregate purchase price of $178.4 million, and the June 2026 10-Q reports three more in the six months to June 30, 2026 for $191.5 million, none of them material. Neither filing names the deals.
Adaptive ML signals the direction: the Q2 release says it accelerates Datadog AI Research's work on “world models and agentic LLM post-training for observability.” This likely means agents trained on the telemetry Datadog already collects.
What the headline misses
Before the Eppo deal, Upstarts Media reported Datadog planned to pay $220 million for it, according to TechCrunch. That exceeds the $178.4 million booked for all three 2025 agreements. One read on this: if Eppo is among them, as its May 2025 date suggests, either the reported price was high or part of the payout is booked as compensation, not purchase price. The filings do not say.
The Palo Alto Networks Report: What Was Reported, and What Wasn't
On August 26, 2026, The Information reported that Palo Alto Networks CEO Nikesh Arora had explored acquiring Datadog, “citing two people with knowledge of the situation,” per MT Newswires. It is a media report based on unnamed sources, not a confirmed event. According to Investing.com's summary, “Arora approached Datadog CEO Olivier Pomel in spring 2025, pitching a hypothetical acquisition when Datadog was publicly valued at more than $40 billion, The Information reported,” and “Pomel was not receptive and no formal offer was made.”
Datadog shares rose on the report; the headline of The Information's briefing put the move at 5%. As of September 27, 2026, we found no public statement from Datadog and no confirmation from Palo Alto Networks, which “didn't immediately reply to a request for comment from MT Newswires.” Treat the account as unconfirmed.
Palo Alto later paid $3.35 billion for Chronosphere in January 2026, which Investing.com calls “a smaller rival to Datadog focused on log data and observability,” adding that Datadog's market cap had since roughly doubled to more than $80 billion, “making a deal considerably less likely.” We covered that sequence in Palo Alto's Chronosphere deal after the reported Datadog and Okta talks; Palo Alto's deals are tracked on its company page.
The structural fact that matters: each Class B share carries ten votes, and as of March 31, 2026 Pomel held 17.3% of total voting power, Lê-Quôc 15.5%, and executive officers and directors as a group 35.5%, per the 2026 proxy statement. One read on this: the founders' roughly one-third of the vote would weigh heavily on any deal.
Revenue and Key Metrics
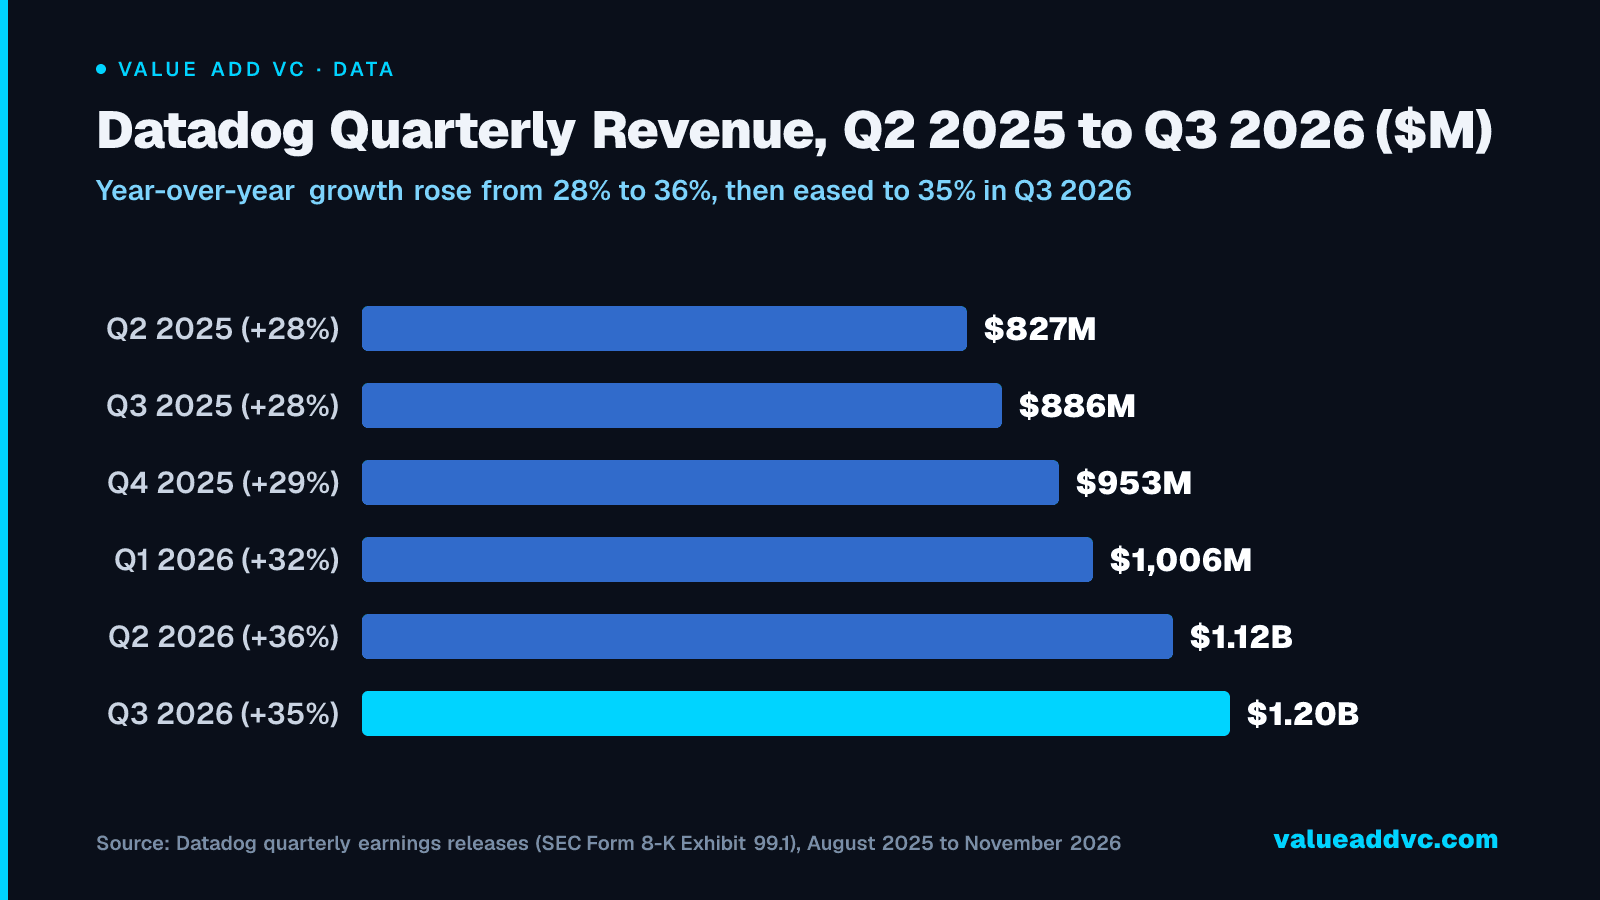
Annual revenue rose from $2,128 million in 2023 to $2,684 million in 2024 and $3,427 million in 2025, per the 10-K. Quarterly growth has accelerated three quarters running, from 28% in the September 2025 quarter to 36% in the June 2026 quarter, per the releases for Q2 2025, Q3 2025, Q4 2025, Q1 2026 and Q2 2026. Growth then eased to 35% in the September 2026 quarter, on $1,197 million of revenue, per the Q3 2026 release.
Datadog Quarterly Revenue, Q2 2025 to Q3 2026 ($M)
Year-over-year growth rose from 28% to 36%, then eased to 35% in Q3 2026
Datadog quarterly earnings releases (SEC Form 8-K Exhibit 99.1), August 2025 to November 2026
Data
| Item | Value |
|---|---|
| Q2 2025 (+28%) | $827M |
| Q3 2025 (+28%) | $886M |
| Q4 2025 (+29%) | $953M |
| Q1 2026 (+32%) | $1,006M |
| Q2 2026 (+36%) | $1.12B |
| Q3 2026 (+35%) | $1.20B |
| Metric | Q2 2025 | Q2 2026 |
|---|---|---|
| Revenue | $827M (+28%) | $1.12B (+36%) |
| GAAP operating margin | (4)% | 0% |
| Non-GAAP operating margin | 20% | 23% |
| Free cash flow | $165M | $279M |
| $100K+ ARR customers | ~3,850 | ~4,720 |
| Total customers | ~31,400 | ~33,400 |
| Net retention (TTM) | About 120% | Low-120%s |
Quarters ended June 30. Sources: Datadog Q2 2025 and Q2 2026 releases; customer totals and net retention from the Q2 2026 10-Q.
Then the customer problem. The 10-Q discloses that the AI-native cohort, “which cohort includes our largest customer,” contributed high single digit percentage points to June-quarter growth, and that “beginning in the third quarter of 2026, we saw our largest customer reduce their usage.” Datadog does not name the customer. Benzinga reported it is “widely believed by Wall Street analysts to be OpenAI” and that the stock “closed 19.03% lower at $229.29 per share on Thursday,” the day of the August 6 report.
Profit depends on the lens. GAAP operating income was $5 million against a 23% non-GAAP margin, mainly because stock-based compensation was $220.3 million, about 19.6% of revenue by our math. Gross margin slipped to 79% from 80% as third-party cloud infrastructure hosting and software costs rose $64.1 million, the 10-Q says. Still, 36% growth plus a 25% free-cash-flow margin scores 61 on the Rule of 40, on our math.
Competitive Landscape
The 10-K names Cisco, New Relic and Dynatrace in APM; Cisco and Elastic in logs; IBM, Microsoft and SolarWinds in on-premise monitoring; and AWS, Azure and Google Cloud's native tools, plus open-source and home-grown software. Dynatrace is the cleanest comparison: its fiscal quarter also ended June 30, 2026.
Datadog vs Dynatrace, Quarter Ended June 30, 2026
Datadog Q2 2026 earnings release (Aug 6, 2026); Dynatrace Q1 fiscal 2027 earnings release (Aug 5, 2026)
Data
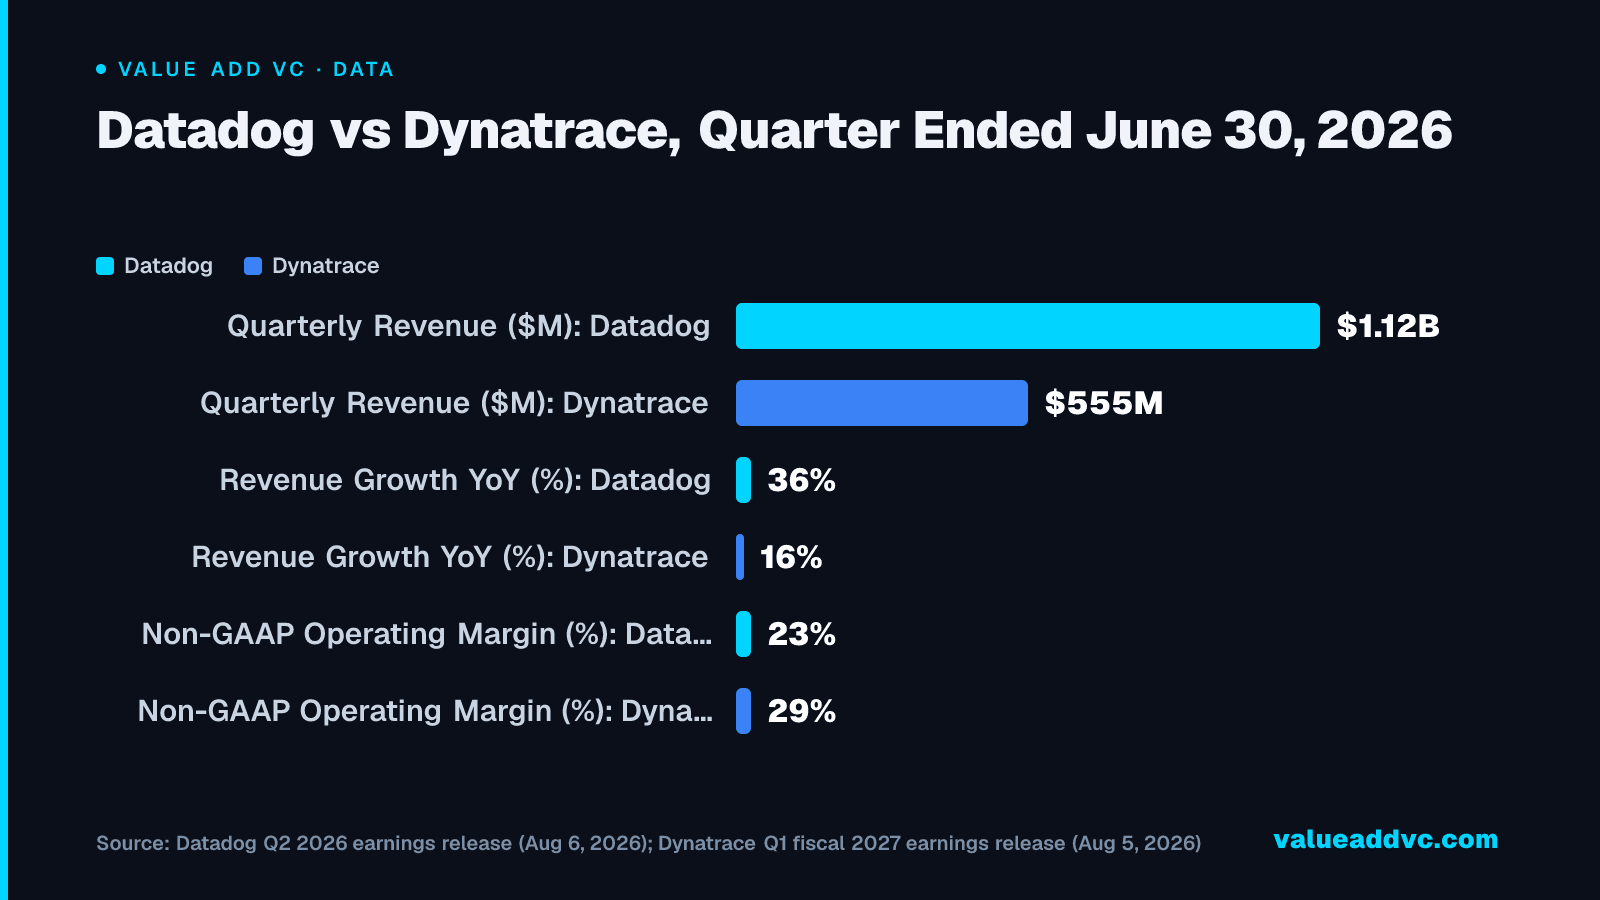
Datadog is about twice Dynatrace's size and growing more than twice as fast; Dynatrace runs the higher margin.
Dynatrace grew revenue 16% (15% in constant currency), per its August 5, 2026 release. Venture money is coming too: Groundcover raised a $100 million Series C led by One Peak, reported by SiliconANGLE on July 29, 2026, which cited CTech for a $500 million valuation (see its company page). Chronosphere, another venture-backed challenger, now belongs to Palo Alto Networks.
Leadership Team
Olivier Pomel, Co-Founder and CEO
CEO and director since June 2010. He was vice president of technology at Wireless Generation from 2002 until News Corp acquired it in 2010, per the 2026 proxy, and holds an M.S. in computer science from Ecole Centrale Paris.
Alexis Lê-Quôc, Co-Founder and CTO
CTO and director since June 2010; previously at Wireless Generation (March 2004 to December 2010), IBM Research and France Télécom.
David Obstler, CFO
CFO since November 2018, previously CFO at TravelClick, OpenLink Financial, MSCI and Risk Metrics Group. Other executives include COO Adam Blitzer, Chief Product Officer Yanbing Li and Chief Revenue Officer Sean Walters.
Stockholders approved moving Datadog's incorporation from Delaware to Nevada in April 2026, per a Form 8-K. About 44% of full-time staff were outside the United States at the end of 2025, and 34% of those were in France.
Bull Case / Bear Case
The Bull Case
- +About 70% of the June-quarter revenue increase came from existing customers, per the 10-Q filing.
- +Customers with $100K+ ARR made up 91% of ARR at June 30, 2026, up from 89% a year earlier.
- +About 9% of customers used ten or more products at the end of 2025, up from 5%.
- +2025 free cash flow was several times that year's aggregate acquisition purchase price, on our math.
The Bear Case
- –Concentration: the 10-Q discloses a usage cut by the largest customer, part of an AI-native cohort that "rapidly increased" usage.
- –The third-quarter guide implies a sharp step down from 36% growth (see the outlook below).
- –Remaining performance obligations were $3.47 billion at June 30, 2026 versus $3.46 billion six months earlier, per the 10-Q filing.
- –Cloud providers bundle their own monitoring, and venture-backed challengers keep raising.
Outlook: What the 2026 Guidance Says
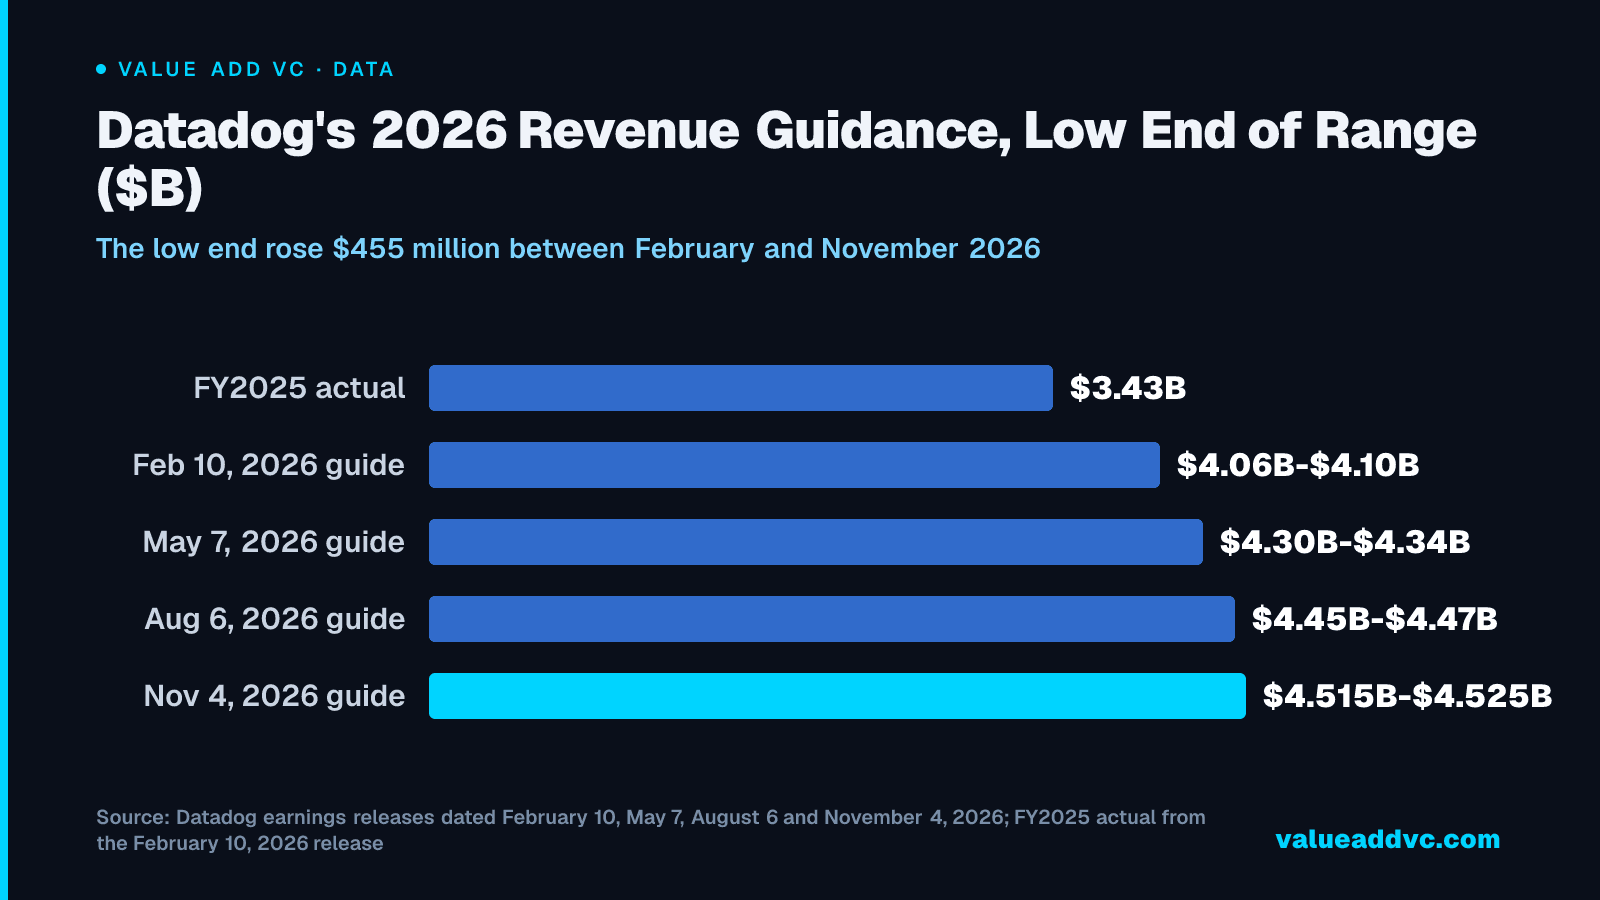
Datadog has been public since 2019, so its test is guidance, not an IPO. It raised its 2026 revenue range from $4.06 billion to $4.10 billion in February, to $4.30 billion to $4.34 billion in May, to $4.45 billion to $4.47 billion in August, and to $4.515 billion to $4.525 billion on November 4, per the February, May, August and November releases: about 32% growth over 2025 on our math.
Datadog's 2026 Revenue Guidance, Low End of Range ($B)
The low end rose $455 million between February and November 2026
Datadog earnings releases dated February 10, May 7, August 6 and November 4, 2026; FY2025 actual from the February 10, 2026 release
Data
| Item | Value |
|---|---|
| FY2025 actual | $3.43B |
| Feb 10, 2026 guide | $4.06B-$4.10B |
| May 7, 2026 guide | $4.30B-$4.34B |
| Aug 6, 2026 guide | $4.45B-$4.47B |
| Nov 4, 2026 guide | $4.515B-$4.525B |
Third-quarter guidance of $1.135 billion to $1.145 billion implied roughly 28% to 29% growth over the $886 million of Q3 2025; Datadog instead delivered $1,197 million, up 35%. The deceleration the 10-Q warned about (“may cause a deceleration in revenue growth”) now shows up in the fourth-quarter guide instead: $1.19 billion to $1.20 billion, roughly flat with Q3 and about 25% to 26% above the $953 million of Q4 2025, on our math. On the call, management said renewal extensions with some large customers and large AI customers at better pricing are “a headwind in the short term to revenue,” per 24/7 Wall St. The stock closed down 14.4% at $188.72 on November 4, from $220.52, per Yahoo Finance. Watch whether that customer stabilizes, whether net retention holds, and whether remaining performance obligations grow again.
The Bottom Line
Datadog pairs more than $4 billion of expected 2026 revenue with growth that sped up into mid-2026 and real free cash flow, and its product pace and small-bore M&A keep widening what each customer can buy. The near-term risk is concentration more than competition: the AI-native customers that helped push growth higher include the account Datadog says is now using less. The Palo Alto Networks story adds a takeover narrative, but it is an unconfirmed report about a 2025 conversation that, by the reporting's own account, went nowhere. Follow the company on its Datadog company page.
Figures are from Datadog's SEC filings and earnings releases unless attributed to a named outlet, as of November 4, 2026; customer totals, net retention and remaining performance obligations are from the June 2026 10-Q until the September 10-Q is filed. Calculations marked “our math” are Value Add VC's. Reports about Palo Alto Networks and the identity of Datadog's largest customer are unconfirmed by the companies.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗