
Tiger Global's PIP 16 venture fund was up 33% in 2025, per its December 2025 investor letter, on marks in OpenAI and Waymo — and as of September 2026, the firm has already launched a follow-on fund, PIP 17, targeting roughly $2.2B. That's the short answer to where Chase Coleman's firm sits in venture today. The longer answer is more interesting.
Four years ago Tiger Global was the most aggressive venture investor on earth, leading 212 private funding rounds in a single year. Then 2022 happened: a 56% flagship loss, a third of its private book marked down, and a fundraising machine that suddenly stalled. What came next isn't a victory lap — it's a smaller, slower, far more deliberate comeback built around AI and the secondary market, and as of September 2026 the firm is already raising the sequel.
Updated November 4, 2026: OpenAI's new round was reported cut to about $20 billion at $1.25 trillion on October 30-31, so the $1.4 trillion figure tied to Tiger's $5 billion paper gain is now dated. Updated October 30, 2026: new reporting on Tiger Global's OpenAI paper gain, two new late-October checks (Fort Robotics and Easol), and a clarification that we have not verified PIP 17's first close. See "What changed on October 30, 2026" below.
What changed on October 30, 2026: a $5B OpenAI paper gain and two new checks
Tiger Global's headline numbers on this page are unchanged: the 56% flagship loss in 2022, the shrink from PIP 15's $12.7B to a $2.2B fund, and PIP 16's 33% gain in 2025. What is new is the size of the prize attached to the comeback and evidence that the firm is still writing checks.
| Date | What changed | Source |
|---|---|---|
| Oct 8-9, 2026 | Bloomberg reports Tiger stands to make a $5 billion paper profit on its early OpenAI bet; OpenAI is in talks to raise $30 billion at a $1.4 trillion valuation. Tiger invested $150 million in 2021 before ChatGPT launched. | The Daily Upside |
| Oct 30-31, 2026 | OpenAI's new round is reported cut to about $20 billion at a $1.25 trillion valuation, from $30 billion at $1.4 trillion, with $11 billion secured, per the Financial Times and the Wall Street Journal. The cut lowers the mark that Bloomberg's $5 billion Tiger estimate was based on. | TechCrunch |
| Oct 28, 2026 | Fort Robotics: Tiger leads an approximately $10 million financing with Mark Cuban Companies and commits another $10 million to the PIPE tied to the Newbury Street II Acquisition Corp. combination; total committed capital to date exceeds $50 million. Tiger led Fort's 2022 Series B. | Robotics & Automation News |
| Oct 29, 2026 | Easol raises a £22.5 million Series A extension: £15 million of equity from Y Combinator, Tiger Global, Foundation Capital, FMZ Ventures, Notion Capital and Eight Roads plus a £7.5 million Viola Credit debt facility; total funding £45 million. | Soapbox |
How much could Tiger Global make on OpenAI?
About $5 billion on paper, according to Bloomberg. The Daily Upside's October 9 write-up says Tiger Global "stands to snag a $5 billion paper profit from its early bet on OpenAI, which is in talks to raise $30 billion at a $1.4 trillion valuation, Bloomberg reported Thursday," and that the firm "invested $150 million in Sam Altman's company back in 2021 before ChatGPT launched and has added to the investment over the years." We have not opened Bloomberg's own report, so treat the $5 billion as Bloomberg's estimate as relayed by The Daily Upside. It is also dated: the $1.4 trillion figure was OpenAI's target as of October 8-9, and on October 31 TechCrunch reported that the target had been cut to about $20 billion at $1.25 trillion, with $11 billion secured. Tiger's ownership stake and cost basis are not given in the article, so we do not derive a multiple. See how that valuation compares with other frontier labs on our AI valuations dashboard.
Why does the $5B gain matter after 2022?
The same article recalls that Tiger became "one of the 'biggest losers' of hedge funds in 2022 when rates reversed, hemorrhaging $18 billion for the year." Set side by side, a $5 billion unrealized gain on one position is the clearest sign yet of how concentrated the recovery is. It is also exactly the paper-versus-cash distinction this page flagged in the DPI discussion below: a gain on an illiquid stake becomes a distribution only if Tiger sells or the shares become tradable.
Is Tiger Global still making new investments?
Yes, based on two disclosed rounds in the last week of October 2026. On October 28, Fort Robotics said Tiger Global is leading an approximately $10 million financing, with participation from Mark Cuban Companies, and has committed an additional $10 million to the PIPE expected to close with Fort's proposed business combination with Newbury Street II Acquisition Corp. Together with earlier commitments, Fort says total committed capital to date in connection with the combination exceeds $50 million, and that Tiger has been a Fort investor since 2022, when it led the Series B. On October 29, UK commerce platform Easol (festivals, wellness retreats, sports and location-based venues) announced a £22.5 million Series A extension that includes Tiger Global among its equity investors. Both are small next to the $12.7B PIP 15 era, but they show a check-writing pattern beyond the AI marks that dominate the headlines.
What is not confirmed?
We have not added newer return, IRR or assets-under-management figures for Tiger's funds because we could not open a primary or clearly attributable source for them, and the page's roughly $50B AUM figure remains an estimate rather than a Tiger disclosure. We will add updated numbers when we can open a source for them.
Tiger Global Venture 2026: What the Firm Is Actually Doing
In 2026, Tiger Global is still investing out of its $2.2B PIP 16 fund — a fraction of the $12.7B PIP 15 it raised in 2022 — while concentrating on AI infrastructure, application-layer leaders, and discounted secondaries. After the 56% flagship loss in 2022, the firm slowed from 212 rounds led in 2021 to just nine new private investments in 2025, prioritizing ownership concentration and pricing discipline over speed, according to CNBC's reporting on the firm's newest fund.
The headline isn't that Tiger left venture. It's that the version of Tiger that defined 2021 — fast term sheets, light diligence, top-of-market prices — is gone. The 2026 firm manages an estimated $50B across strategies, down from a roughly $95B peak, and it is deploying that capital into a market that finally rewards discipline. You can see the broader recovery in our VC Performance dashboard, where crossover funds' marks are only now climbing back toward 2021 levels, and in Value Add's Tiger Global intelligence profile.
How Tiger Global's Venture Strategy Changed Since 2021
The simplest way to understand the comeback is to look at the firm year by year. The arc runs from peak aggression, through a near-fatal drawdown, to a recovery built on a much smaller base.
| Year | Est. new private deals | Flagship net return | Fund / event |
|---|---|---|---|
| 2021 | 212 led | −7% | Peak pace; deploying PIP 14, most active VC globally |
| 2022 | ~120 | −56% | PIP 15 closes at $12.7B; ~33% private markdowns |
| 2023 | ~50 | +28.5% | Pace cut 80%+; begins raising PIP 16 |
| 2024 | ~40 | ~+24% | PIP 16 closes near $2.2B vs ~$6B target |
| 2025 | 9 | PIP 16 +33% YTD* | PIP 17 announced Dec. 2025 at a $2.2B target |
| 2026 | Selective | n/a YTD | PIP 17 first close targeted ~March 18, 2026 (close not verified); Fort Robotics and Easol checks in late Oct |
2021-2024 figures are estimates blended from PitchBook, CB Insights, The Information, and Tiger Global investor-letter reporting; the 2021-2024 return column refers to the long/short hedge fund, not the PIP vehicles. *The 2025 PIP 16 return is the fund-level figure Tiger disclosed to LPs in its December 2025 investor letter, not the flagship hedge fund return — see CNBC. The 212 led-rounds figure for 2021 and the 9 new investments in 2025 are as reported in year-end deal tallies covered by TechCrunch.
The Fall: Why 2022 Nearly Broke the Model
Tiger Global's 2021 strategy was a momentum machine. Term sheets in days, valuations 20–30% above market, and a willingness to pre-empt rounds nobody else had seen. It worked spectacularly while rates were near zero and growth multiples expanded. When the Fed lifted rates from roughly 0% to over 5% in 18 months, the whole edifice inverted.
−56%
Flagship hedge fund return in 2022 — among the worst of any large fund that cycle
~33%
Markdown to the private portfolio over 2022 as growth multiples compressed
212 → 9
Rounds led in 2021 vs. new private investments made in all of 2025
$95B → ~$50B
Approximate firm-wide AUM from 2021 peak to 2026 estimate
The damage wasn't only in the numbers. Tiger's reputation as the buyer-of-last-resort at any price meant it owned a disproportionate share of the most overpriced rounds of the cycle — the 2021 unicorns now trading at steep discounts, many of which we tracked in our 2021 unicorn class analysis. Senior dealmaker Scott Shleifer, the architect of the private strategy, stepped back to a senior-advisor role, and the firm spent 2022–2023 rebuilding trust with its LPs.
Tiger Global's Venture Portfolio in 2026: AI, Secondaries, and Discipline
The 2026 comeback rests on three pillars, and all of them are narrower than the 2021 playbook. Tiger is no longer trying to own a piece of everything — it's trying to own more of the few things it believes will define the next decade.
The secondary pivot is the most telling. In 2021, Tiger drove primary prices up; in 2026, it's a buyer in a secondary market that hit record volume — a dynamic we break down in our VC secondaries market analysis. The firm that once set the top of the market is now hunting its bottom.
Tiger Global vs. the Crossover Field in 2026
Tiger isn't the only crossover investor that retrenched. Comparing the big growth-stage players shows a whole category that got smaller and more disciplined — but Tiger's swing was the most violent in both directions.
| Firm | 2021 posture | 2026 posture | Latest growth/private fund |
|---|---|---|---|
| Tiger Global | ~340 deals, top-of-market | Selective, AI + secondaries | $2.2B PIP 16 (2024); $2.2B PIP 17 (launched Dec. 2025) |
| Coatue | Heavy late-stage growth | AI-focused, more concentrated | Multi-billion growth + AI funds |
| Insight Partners | Aggressive software buyer | Slower, software + AI | ~$10B Fund XIII (2024) |
| SoftBank Vision Fund | Mega-checks, Vision Fund 2 | Selective, AI infra (incl. OpenAI) | No new mega-fund; balance-sheet bets |
| a16z | Multi-strategy expansion | Mega-funds, AI-led | ~$15B raise (2025) |
| Thrive Capital | Concentrated growth | Concentrated, AI-led | ~$5B+ recent vintages |
Figures are 2026 estimates blended from PitchBook, Crunchbase, The Information, and firm announcements. Fund sizes are most-recent reported flagship growth/private vehicles and may include multiple strategies; postures are editorial characterizations, not firm statements.
PIP 17: Tiger Global's Next Fund, Announced December 2025
The comeback story didn't stop at PIP 16. On December 8, 2025, CNBC reported that Tiger Global had begun raising PIP 17, a follow-on venture fund initially floated at $2-3B and later set at a roughly $2.2B target — deliberately similar in size and construction to PIP 16, according to TechCrunch's coverage of the launch. That December 2025 reporting pointed to a first close around March 18, 2026, with Chase Coleman and firm insiders positioned as some of its largest LPs. We have not verified that a first close happened or what the final size was, so $2.2B should be read as a target.
Tiger Global PIP Fund Sizes by Vintage
PIP 17 holds at PIP 16's smaller size instead of rebuilding toward the $12.7B PIP 15 peak
PitchBook, CNBC, TechCrunch, 2025-2026 fund disclosures
Data
| Item | Value |
|---|---|
| PIP 15 (2022) | $12.7B |
| PIP 16 (2023-24) | $2.2B |
| PIP 17 (2025-26) | $2.2B |
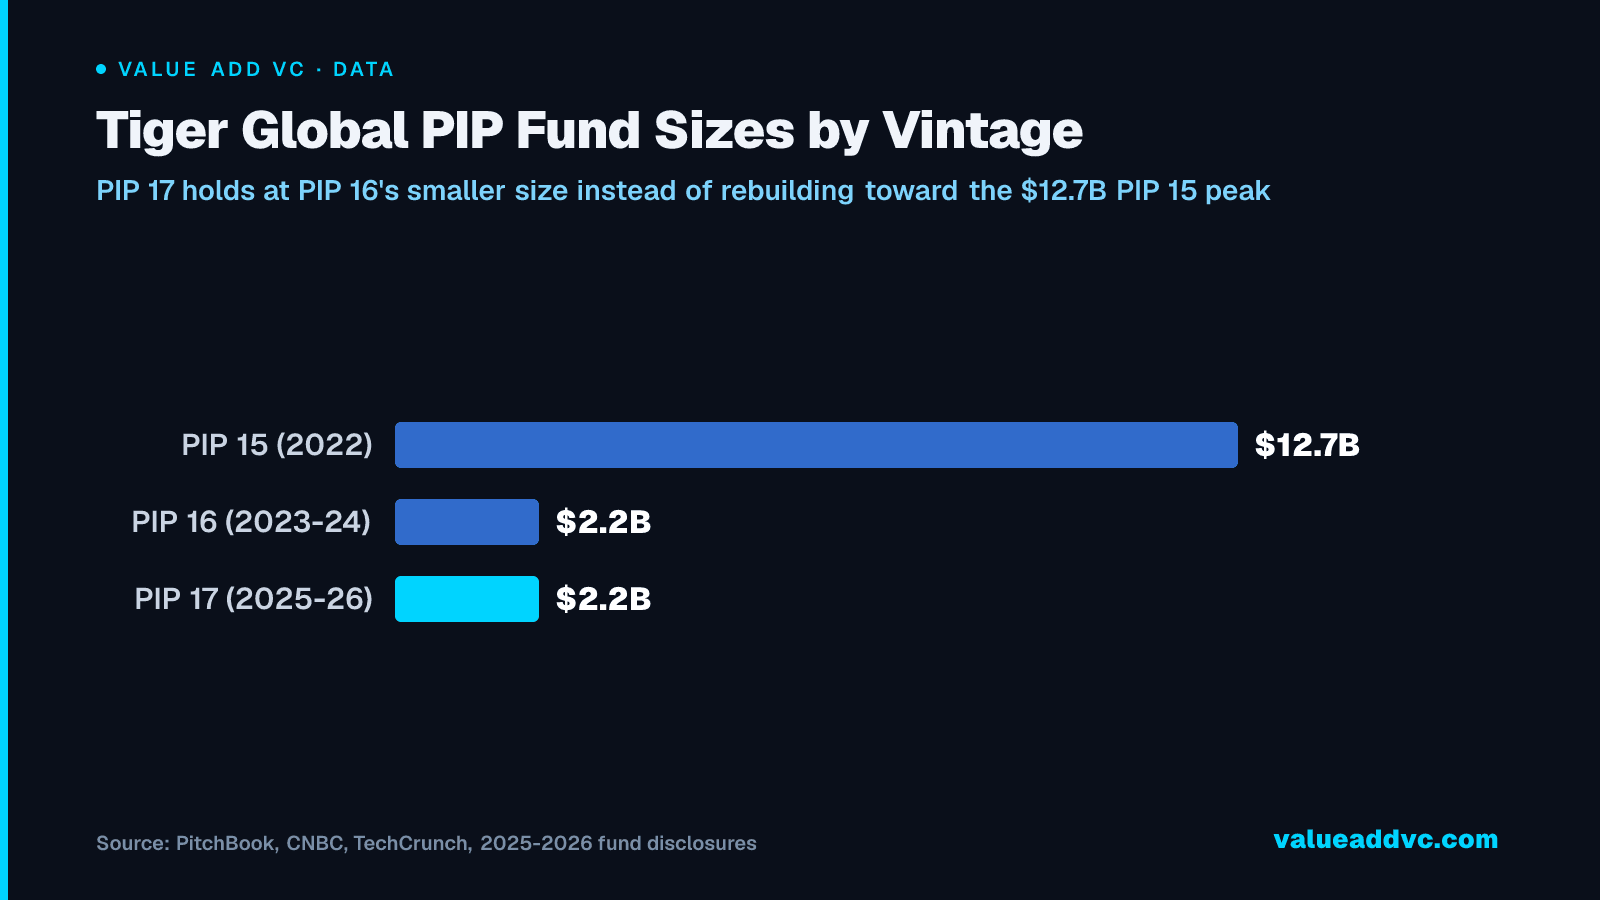
What's notable is what PIP 17 is not: it isn't a bounce-back toward mega-fund size, even with AI valuations running hot again. About two-thirds of PIP 16's invested capital over the past three years went into AI names — Waymo, OpenAI, Temporal, and Cerebras among them — and PIP 17 is expected to follow the same concentrated playbook rather than widen back out. PIP 17 also entered into an uncommitted revolving credit agreement with JPMorgan Chase Bank on March 25, 2026, according to regulatory filings reported by Deadline Disclosures — the kind of subscription-line facility more common at hedge funds and buyout shops than at a first-deployment venture fund, and itself a sign of how differently this fund is being financed.
The nine-deals-a-year pace isn't frozen, either — Tiger Global's disclosed check into business-productivity software company Archive landed on September 2, 2026, according to deal-tracking data compiled by Tracxn, and two more disclosed rounds followed in late October (Fort Robotics and Easol, below). That pattern matters more than any single check: Tiger is still writing new checks alongside managing the OpenAI and Waymo marks that are driving PIP 16's return, not sitting entirely on the sidelines while PIP 17 closes.
What the headline misses
A 33% year-to-date mark is a paper gain on illiquid stakes, not cash back to LPs — and it isn't uncontested. Securities litigation firm Miller Shah LLP has said it is investigating PIP 15 and PIP 16 over reported losses on behalf of investors, a signal that some LPs still dispute how the drawdown years were valued and disclosed. Until PIP 16 actually distributes capital — through an IPO, a sale, or the new credit line — the 33% figure describes Tiger's own marks on OpenAI and Waymo, not money in hand.
What Tiger Global's 2026 Comeback Means for Founders and LPs
For Founders
- ✓ Fewer, larger checks — but real diligence and tougher terms
- ✓ Pre-emptive, sky-high rounds are mostly over
- ✓ AI and clear-path-to-liquidity companies get the attention
- ✓ Expect ownership targets, not just speed of close
For LPs
- ✕ A $2.2B fund vs. $12.7B means far less deployment capacity
- ✕ 2021-vintage marks still recovering from ~33% cuts
- ✕ DPI, not paper TVPI, is the test of the comeback
- ✕ Manager selection matters more than brand in 2026
For LPs the real question is liquidity. Tiger's 2021 funds generated enormous paper gains that evaporated; the only number that matters now is cash back. That's why DPI — distributions to paid-in — has replaced TVPI as the metric LPs watch, a shift we cover in why DPI is the only metric that matters. A smaller, disciplined Tiger that actually returns capital is worth more to LPs than the $95B version that never did.
Subscription-line facilities like PIP 17's new JPMorgan agreement are typically used by private funds to smooth capital calls or bridge short-term liquidity, not to generate a distribution on their own — so it doesn't resolve the DPI question by itself. Whether Tiger can convert its OpenAI and Waymo marks into actual cash for LPs still depends on those companies eventually going public or trading hands, a timeline worth watching alongside the Miller Shah inquiry as PIP 16 and PIP 17 both mature through 2026.
The 2021 Tiger Global is not coming back.
A $2.2B fund, an 80% slower pace, and a secondary-market buyer's discipline — the comeback is real, but it's a different firm.
Track crossover and growth-fund performance on the VC Performance Dashboard and new billion-dollar companies on the Unicorns tracker at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗