
Palantir generated $1.935 billion in revenue in Q2 2026, up 93% year-over-year, with U.S. commercial revenue growing 149% to $764 million on the back of its AI Platform (AIP). Behind those numbers is a two-decade-old government contractor that quietly became one of the fastest-growing, highest-margin software companies on the planet.
Palantir spent its first 15 years as a company most people associated almost entirely with classified government work — the Army, the CIA, immigration enforcement. In 2026, its market cap is about $447 billion (late September 2026), it trades at roughly 160 times trailing earnings, and its commercial business has nearly closed the gap with government: $945 million versus $990 million in Q2 2026. Here's exactly how the money moves, and why investors are paying such an extreme premium for it.
Figures from Palantir's Q2 2026 earnings release (August 3, 2026) and Q2 2026 Form 10-Q; market cap from The Motley Fool (September 29, 2026); trailing P/E from IG, citing Yahoo Finance (October 1, 2026).
How Does Palantir Make Money?
Palantir makes money selling three software platforms — Gotham (government and defense intelligence), Foundry (commercial data integration), and the Artificial Intelligence Platform, or AIP, layered across both — through multi-year subscription and licensing contracts. In Q2 2026, that combination produced $1.935 billion in total revenue, up 93% year-over-year and 19% sequentially, split almost evenly between government agencies ($990 million) and private enterprises ($945 million).
What makes Palantir unusual is that it sells essentially the same underlying data-ontology technology to both buyers. The Army uses it to fuse battlefield sensor feeds; an airline or bank uses the same core platform, rebranded as Foundry, to fuse supply-chain or fraud data. AIP, launched in 2023, is the layer that lets both sets of customers plug large language models into that existing data infrastructure — and it's the single biggest reason commercial revenue more than doubled in the past year.
What Changed in Palantir's Q2 2026 Results?
Palantir reported Q2 2026 on August 3, 2026, and raised its full-year outlook again. U.S. revenue grew 115% to $1.573 billion, split between U.S. commercial ($764 million, up 149%) and U.S. government ($809 million, up 90%). The company closed $3.373 billion of total contract value, up 49%, including a record $2.132 billion of U.S. commercial contract value, and it booked GAAP net income of $1.062 billion. CEO Alex Karp framed the quarter around sovereignty: "Demand for AI sovereignty has now been unleashed," he said in the earnings release.
Full-year 2026 revenue guidance now sits at $8.150 to $8.158 billion, about 82% growth, with U.S. commercial revenue guided above $3.424 billion (at least 134% growth), adjusted operating income of $4.889 to $4.897 billion, and adjusted free cash flow of $4.5 to $4.7 billion. For Q3 2026, Palantir guided revenue of $2.160 to $2.164 billion; IG expects those results around early November.
What Are Gotham, Foundry, and AIP?
Gotham is Palantir's oldest product, built for intelligence and defense agencies to fuse classified data sources — satellite imagery, signals intercepts, logistics feeds — into a single operational picture. Foundry is the commercial mirror of that same underlying "ontology" architecture, sold to airlines, banks, manufacturers, and hospitals to unify messy internal data (supply chains, claims, sensor readouts) that would otherwise sit in disconnected systems.
AIP, launched in April 2023, doesn't replace Gotham or Foundry — it sits on top of both, letting customers plug large language models directly into data that's already been structured and permissioned inside the platform. That's the practical reason AIP adoption shows up as commercial and government revenue growth rather than as its own line item: it's sold as an upgrade to existing Gotham and Foundry deployments, not a standalone product, which is also why Palantir doesn't break out AIP revenue separately in its filings.
How Much Does Palantir's Government Business Actually Generate?
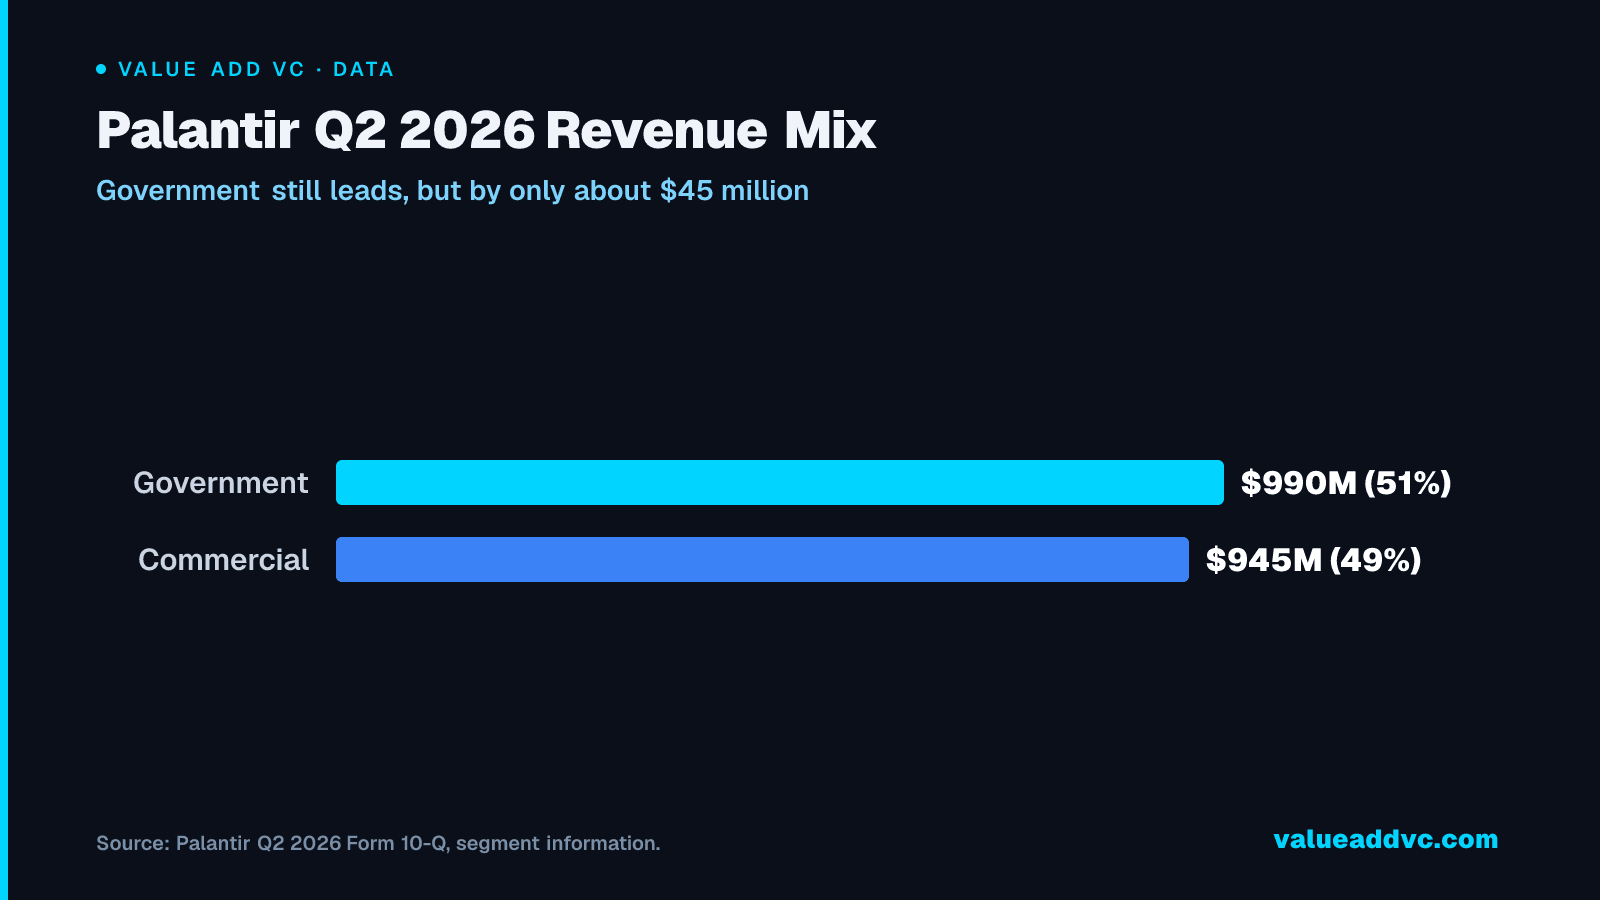
Government revenue reached $990 million in Q2 2026, up 79% year-over-year, and U.S. government revenue alone grew 90% to $809 million. Government remains Palantir's largest customer category in absolute dollars, but commercial revenue is now within about $45 million of it. Palantir does not guide government revenue separately; its raised 2026 outlook covers total revenue and U.S. commercial revenue only.
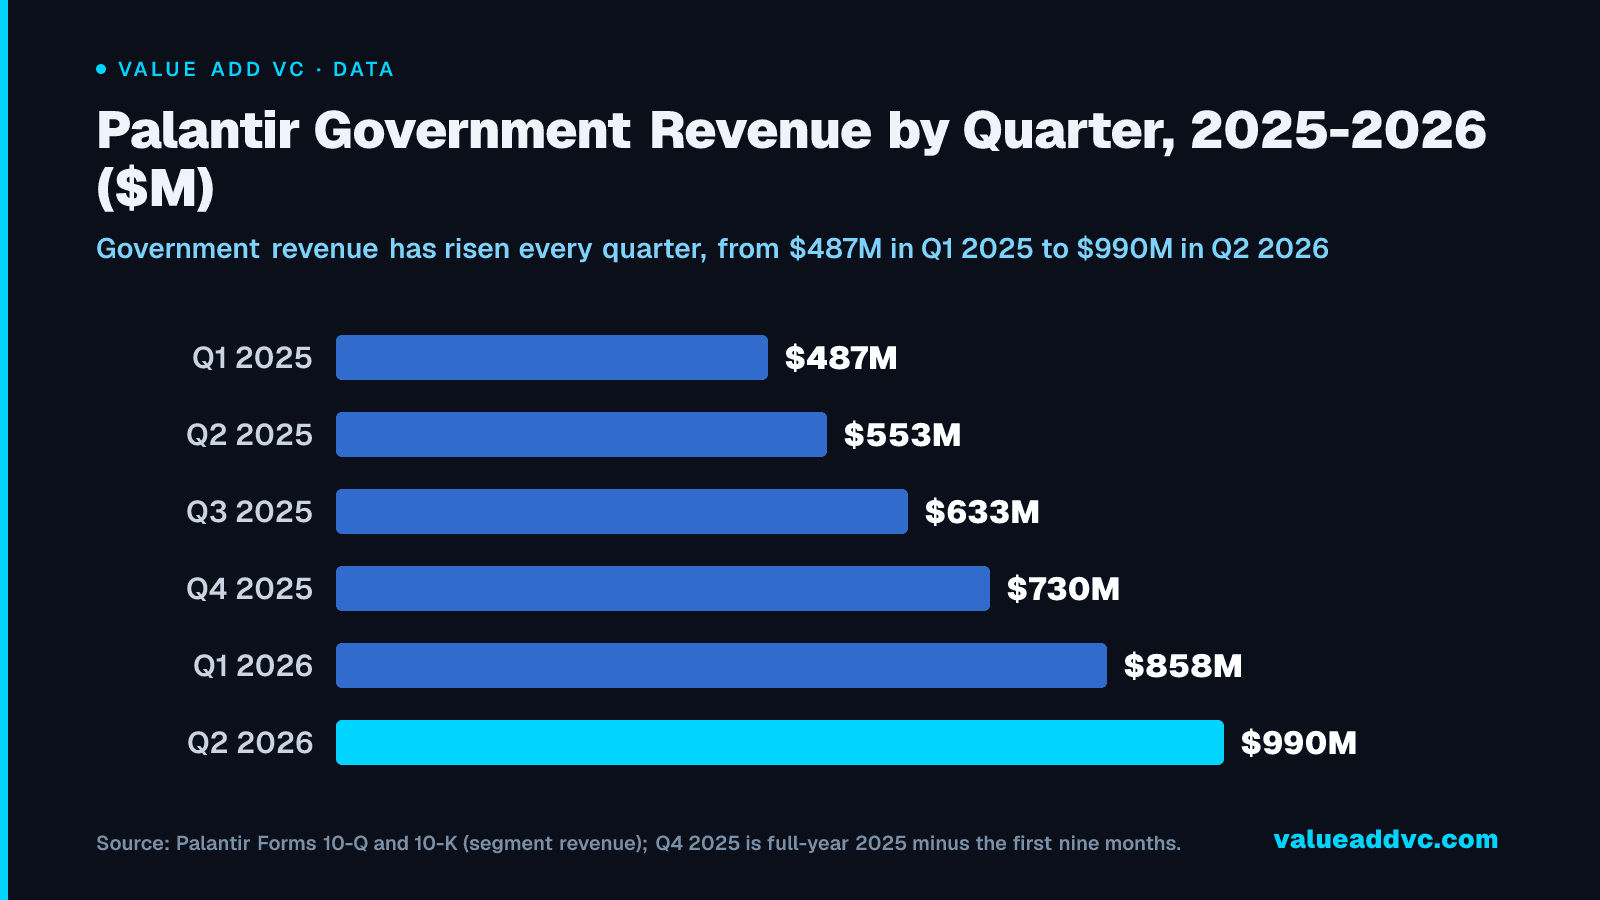
Palantir Government Revenue by Quarter, 2025-2026 ($M)
Government revenue has risen every quarter, from $487M in Q1 2025 to $990M in Q2 2026
Palantir Forms 10-Q and 10-K (segment revenue); Q4 2025 is full-year 2025 minus the first nine months.
Data
| Item | Value |
|---|---|
| Q1 2025 | $487M |
| Q2 2025 | $553M |
| Q3 2025 | $633M |
| Q4 2025 | $730M |
| Q1 2026 | $858M |
| Q2 2026 | $990M |
How Is Palantir's AIP Commercial Business Growing?
U.S. Commercial revenue — the segment most directly attributable to AIP adoption — hit $764 million in Q2 2026, up 149% year-over-year (from $595 million and 133% growth in Q1), and Palantir raised its full-year 2026 guidance for that segment to more than $3.424 billion, implying at least 134% growth. Total commercial revenue (U.S. plus international) reached $945 million in the quarter, up 110%, against $990 million from government.
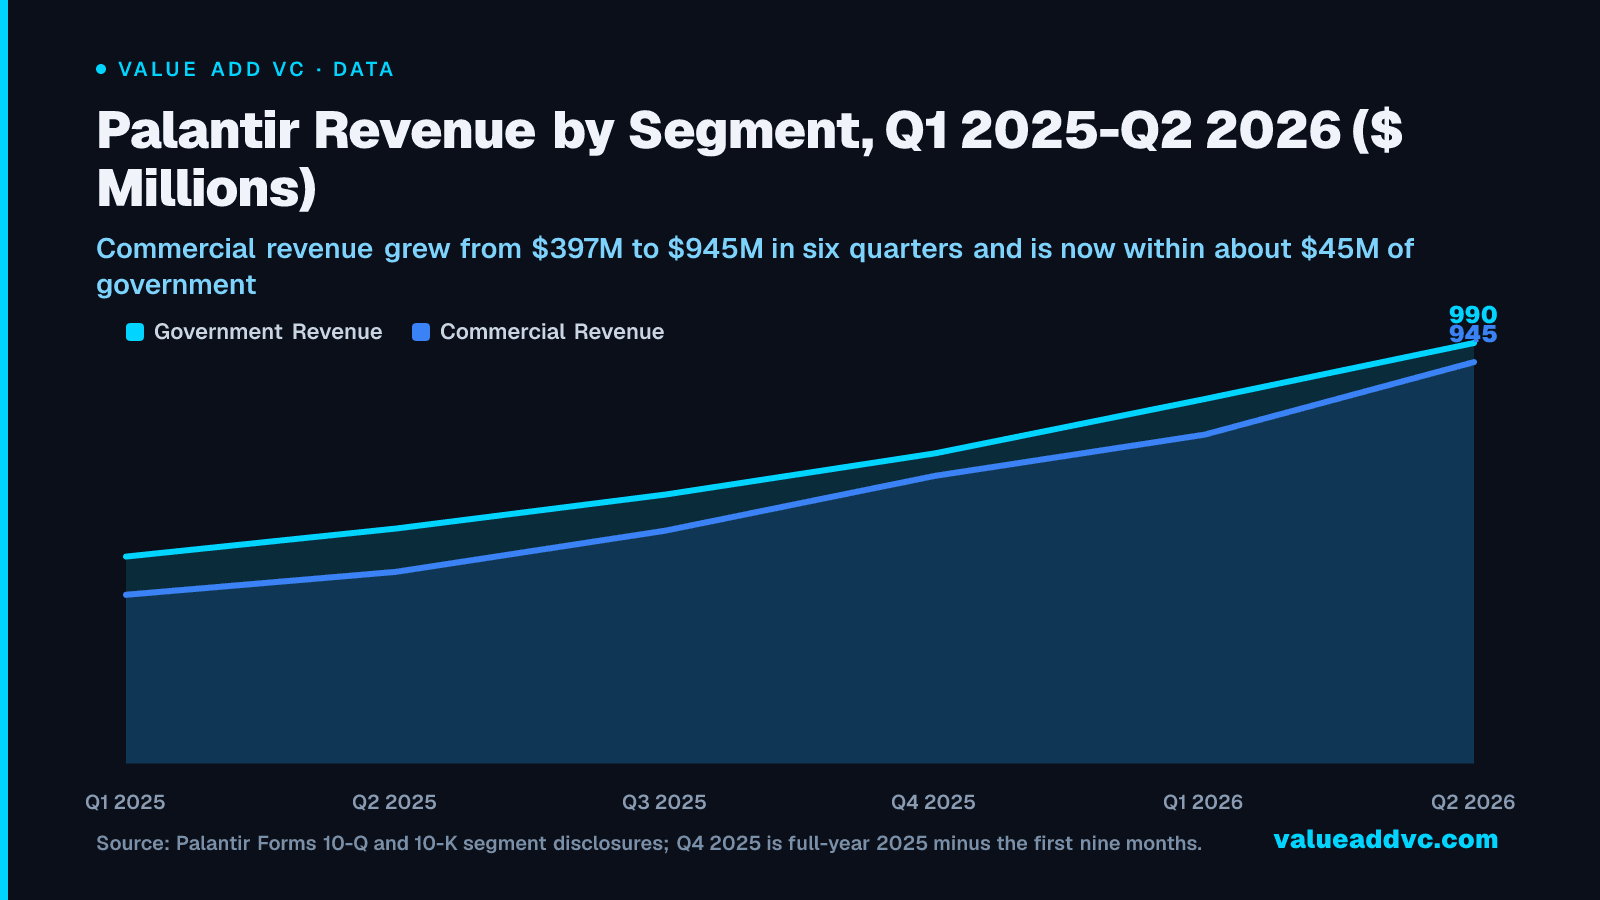
Palantir Revenue by Segment, Q1 2025-Q2 2026 ($ Millions)
Commercial revenue grew from $397M to $945M in six quarters and is now within about $45M of government
Palantir Forms 10-Q and 10-K segment disclosures; Q4 2025 is full-year 2025 minus the first nine months.
Data
| Item | Government Revenue | Commercial Revenue |
|---|---|---|
| Q1 2025 | 487 | 397 |
| Q2 2025 | 553 | 451 |
| Q3 2025 | 633 | 548 |
| Q4 2025 | 730 | 677 |
| Q1 2026 | 858 | 774 |
| Q2 2026 | 990 | 945 |
Commercial's share of total revenue rose from 45% in Q1 2025 to 49% in Q2 2026. That's a meaningful re-rating for a company that spent its first decade known almost exclusively as a defense and intelligence contractor. We track how this kind of enterprise AI adoption compares across sectors on the AI Valuations Dashboard.
Government vs. Commercial: Palantir's Revenue Mix
| Period | Government Revenue | Commercial Revenue | Total Revenue | YoY Growth | Commercial % of Total |
|---|---|---|---|---|---|
| Q1 2024 | $335M | $299M | $634M | 21% | 47% |
| Q1 2025 | $487M | $397M | $884M | 39% | 45% |
| Q1 2026 | $858M | $774M | $1.633B | 85% | 47% |
| Q2 2026 | $990M | $945M | $1.935B | 93% | 49% |
| FY2025 (Actual) | $2.402B | $2.073B | $4.475B | 56% | 46% |
| FY2026 (Guidance) | Not guided | Not guided | $8.150-8.158B | ~82% | — |
Figures from Palantir's Forms 10-Q and 10-K and its Q2 2026 earnings release (reported August 3, 2026). Palantir guides total and U.S. commercial revenue only, not the government/commercial split. Shares are rounded.
Palantir Q2 2026 Revenue Mix
Government still leads, but by only about $45 million
Palantir Q2 2026 Form 10-Q, segment information.
Data
| Item | Value |
|---|---|
| Government | $990M (51%) |
| Commercial | $945M (49%) |
What Is Palantir's Rule of 40 Score, and Why Does It Matter?
The Rule of 40 adds a software company's revenue growth rate to its profit margin — a score above 40% is generally considered healthy, since it means a company is either growing fast, profitable, or both. Palantir's Rule of 40 score hit 155% in Q2 2026, combining 93% revenue growth with a 62% adjusted operating margin, up from 145% in Q1 2026 and 127% in Q4 2025.
A score that high, sustained over multiple quarters, is genuinely rare for a company now guiding to more than $8 billion in annual revenue — most software companies see growth decelerate sharply as they scale past a few billion dollars. Whether Palantir can hold anywhere near 155% as its revenue base keeps growing is the central question hanging over its valuation.
How Does Palantir Compare to Anduril, Snowflake, and Other Data/Defense Companies?
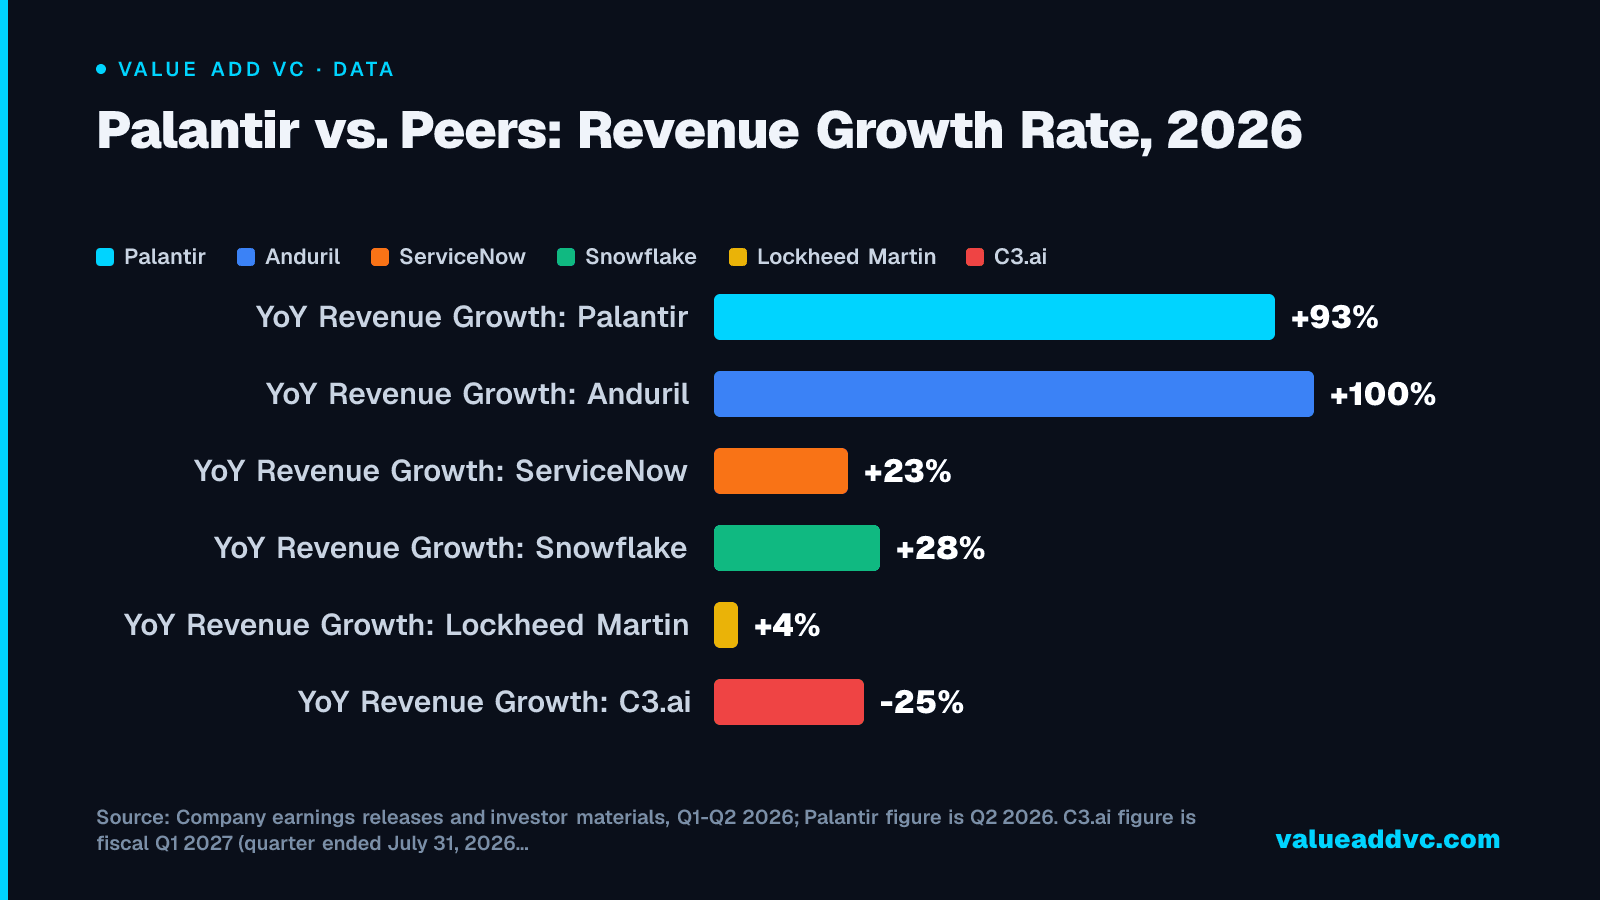
Palantir's growth rate and margins put it in a different league than most of its software peers, and its valuation multiple reflects that. Snowflake guided FY2026 product revenue to $4.45 billion, up about 28%, with a 9% non-GAAP operating margin target — solid, but nowhere near Palantir's combination of growth and profitability. C3.ai, by contrast, is shrinking: revenue fell 25% year-over-year to $52.4 million in its most recent quarter (fiscal Q1 2027, ended July 31, 2026), after a 52.5% drop to $51.6 million in fiscal Q4 2026 (ended April 30, 2026), and full fiscal-2026 revenue fell 36% to $250.3 million, per C3.ai's September 2, 2026 and June 3, 2026 earnings releases. Anduril, the closest defense-tech comparable, is privately held at a $61 billion valuation on roughly $2.2 billion of 2025 revenue — a fraction of Palantir's multiple, though Anduril sells hardware and munitions, not pure software. A smaller public-safety-focused comparable, Peregrine Technologies, was last valued at $6.8 billion in June 2026 on a platform that unifies police and emergency-management data for local and state agencies — a narrower slice of the government-data market than Palantir's Gotham.
Palantir vs. Peers: Revenue Growth Rate, 2026
Company earnings releases and investor materials, Q1-Q2 2026; Palantir figure is Q2 2026. C3.ai figure is fiscal Q1 2027 (quarter ended July 31, 2026) vs. the year-earlier quarter, per its September 2, 2026 earnings release. Anduril figure is 2025 full-year revenue growth (privately held, does not report quarterly).
Data
| Company | 2026 Revenue (Est./Guide) | YoY Growth | Valuation | Forward P/S | Public / Private |
|---|---|---|---|---|---|
| Palantir | $8.15-8.16B | ~82% | ~$447B | ~55x | Public (PLTR) |
| Anduril | N/A (private) | ~100% | $61B | N/A | Private |
| Snowflake | $4.45B | 28% | ~$70B | ~13x | Public (SNOW) |
| ServiceNow | ~$13.5B | 23% | ~$200B | ~11x | Public (NOW) |
| Lockheed Martin | ~$74B | 4% | ~$115B | 1.6x | Public (LMT) |
| C3.ai | $210-240M (FY to Apr. 2027, guide) | -25% (fiscal Q1 2027) | ~$1.7B | ~7x | Public (AI) |
Palantir row: 2026 guidance from its Q2 2026 earnings release, market cap as of September 29, 2026 (The Motley Fool), forward P/S is our arithmetic (market cap divided by the midpoint of 2026 revenue guidance). C3.ai row: fiscal 2027 revenue guidance (year ending April 30, 2027) and fiscal Q1 2027 growth from its September 2, 2026 earnings release; market cap is our arithmetic (160.8 million Class A and B shares outstanding on August 31, 2026, per its fiscal Q1 2027 Form 10-Q, times the $10.34 closing price on September 29, 2026), and forward P/S divides that by the guidance midpoint. Other rows blended from company earnings releases, S&P Global, TradingKey, and Augment Market as of Q2 2026. Anduril and other private company figures are estimates from press disclosures, not audited financials.
Palantir wins that comparison on the metric investors actually reward: the combination of scale, growth, and profitability. No peer on this list matches its Rule of 40 score, which is exactly why the market has assigned Palantir a forward P/S multiple several times Snowflake's and many times Lockheed Martin's. We track how these premiums compare across the broader AI sector on the SaaS Valuations Dashboard.
Is Palantir Overvalued?
Palantir trades at a trailing P/E of roughly 160x, per IG and The Motley Fool, and about 55 times its 2026 revenue guidance — extreme by traditional software standards, where a 4-8x P/S ratio is typical. The Motley Fool noted in late September 2026 that Palantir's roughly $447 billion market cap was a bit over Oracle's. Bulls point to the 155% Rule of 40 score and accelerating U.S. commercial growth as justification; bears note that even a modest deceleration in growth, paired with a multiple compression toward historical software norms, could cut the stock price by half or more without any change in the underlying business.
The most useful lens isn't whether Palantir "deserves" a premium in the abstract — every high-growth, high-margin software company trades at a premium — it's whether 93% growth and a 62% adjusted operating margin can survive the transition from an $8 billion revenue base to far larger ones. Government contracts are sticky and multi-year, often running three to five years with renewal options built in; AIP commercial deals are newer, shorter-tenured, and less proven over a full economic downturn, which is exactly the scenario that would test whether enterprises keep expanding AI software budgets or cut them first.
There's also a concentration risk worth flagging: a meaningful share of Palantir's fastest growth is concentrated in U.S. Commercial, a segment that didn't exist in its current form five years ago and that management itself has guided at 134%+ growth for 2026 — a rate that, by definition, cannot compound indefinitely off an ever-larger base. Investors underwriting the current multiple are effectively betting that AIP adoption is still in its early innings across both government and enterprise customers, not a one-time bump from a single product cycle.
Palantir spent 15 years known almost entirely as a government contractor.
In Q2 2026, its commercial business came within $45 million of its government business.
The Bottom Line: How Does Palantir Actually Make Money?
Palantir makes money selling Gotham, Foundry, and AIP — data-integration and AI software sold on multi-year contracts to governments and enterprises alike — and in Q2 2026 that generated $1.935 billion in revenue, up 93% year-over-year, with a 62% adjusted operating margin. Government revenue is still larger in absolute dollars ($990 million versus $945 million), but commercial revenue, powered largely by AIP adoption, is growing faster and has nearly closed the gap.
That combination of growth and profitability pushed Palantir's Rule of 40 score to 155% and its market cap to about $447 billion — a premium no defense-tech or enterprise-software peer on this list comes close to matching. Whether that premium holds depends entirely on whether Palantir can keep compounding at anywhere near its current pace as its revenue base roughly doubles again.
Track AI and defense-tech company revenue, valuations, and funding on the AI Valuations Dashboard and Defense Tech Tracker at Value Add VC. Reach out at t@nyvp.com or @Trace_Cohen.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗