
Anthropic makes money by selling Claude by the token — 79% of the revenue in a business that booked $17.0 billion in Q3 2026 alone is consumption-based, paid per token, rather than subscription. That mix is the thing to understand about this business. Its Adjusted Operating Income stayed positive in Q3, but its GAAP operating line swung back to a loss.
Most people know Anthropic as "the AI safety company" or "the maker of Claude." Far fewer can tell you how it actually generates revenue. The structure matters because it's a different mix from OpenAI — and it explains why Anthropic keeps winning the developer and enterprise market even when it's second in consumer mindshare.
Updated Nov 2, 2026 with Anthropic's amended S-1 (Q3 2026 results). Q3 revenue was $17.0 billion, up 1,127% year over year; the company posted a $567 million GAAP operating loss, after Q2's $974 million operating income, while Adjusted Operating Income rose to $2.5 billion from $2.2 billion, though the margin fell to 15% from 19%. Both the price range and Run-Rate Revenue were blank in that amendment; Amendment No. 2, filed November 10, 2026, sets a $70.00 to $78.00 price range and states Run-Rate Revenue of approximately $81 billion as of October 31, 2026.
Anthropic's S-1 is now public on SEC EDGAR, filed October 26, 2026 and amended November 2 and November 10, 2026, confirming figures that had previously only circulated from draft prospectus leaks and investor-meeting reports. Full coverage of the filing is in our Anthropic S-1 breakdown.
Anthropic Revenue and Net Loss: Key Numbers
| Period | Revenue | Net income/loss | Source |
|---|---|---|---|
| H1 2025 (six months ended June 30, 2025) | $1.163B | Net loss of $12.969B | SEC EDGAR, Anthropic S-1 (filed Oct. 26, 2026) |
| FY2025 | $4.585B | Net loss of $42.0B; operating loss of $8.06B | SEC EDGAR, Anthropic S-1 (filed Oct. 26, 2026) |
| H1 2026 (six months ended June 30, 2026) | $16.286B | Net loss of $80.7B, incl. a $72.4B non-cash fair-value charge; operating loss $693M | SEC EDGAR, Anthropic S-1 (filed Oct. 26, 2026) |
| Q3 2026 (three months ended Sept. 30, 2026) | $17.0B (+1,127% YoY) | GAAP operating loss $567M (vs Q2's $974M operating income); Adjusted Operating Income $2.5B (15% margin); net loss $23.3B | SEC EDGAR, Anthropic's amended S-1 (filed Nov. 2, 2026) |
| 9 months ended Sept. 30, 2026 | $33.2B (+1,206% YoY) | Operating loss $1.3B; net loss $104.0B, incl. $94.3B non-cash fair-value charge | SEC EDGAR, Anthropic's amended S-1 (filed Nov. 2, 2026) |
FY2025 and H1 figures come from Anthropic's public S-1 (H1 statements are unaudited interim statements); Q3 and nine-month figures come from the amended S-1 (Nov. 2, 2026).
Figures from Anthropic's S-1/A No. 2 (Nov. 10, 2026), the amended S-1 (Nov. 2, 2026), and Fortune's Aug. 15, 2026 report on preliminary Q2 2026 results.
Anthropic's Business Model and How It Makes Money
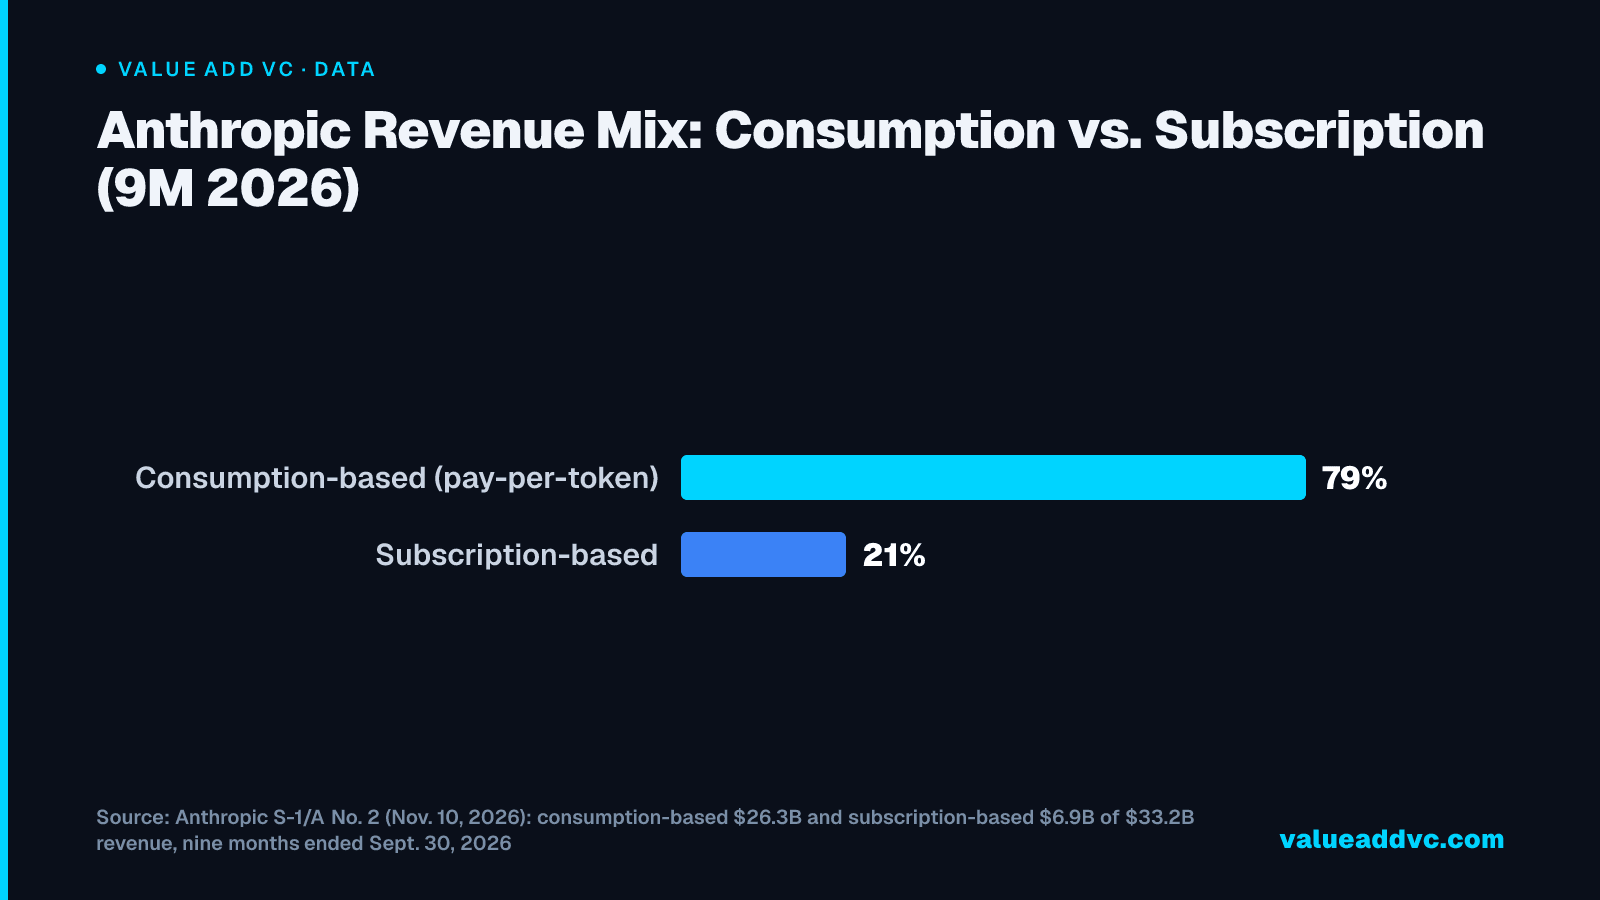
Anthropic's business model is selling metered access to its Claude large language models. Companies and developers pay per million tokens of input and output, and, per its S-1/A, customers pay either per token ("pay-for-intelligence"), by subscription, or both, across its platform and applications such as Claude Code and Claude Cowork. Consumption-based revenue was 79% of revenue for the nine months ended September 30, 2026 and subscription-based revenue 21%. Anthropic booked $17.0 billion of revenue in Q3 2026, up 1,127% year over year, per Anthropic's amended S-1 (filed Nov. 2, 2026). That is a quarterly figure; the approximately $81B of Run-Rate Revenue that Amendment No. 2 states as of October 31 and the $47B reported in Anthropic's Series H announcement in late May are annualized run rates, not comparable.
The single most important fact about this model is its mix. OpenAI is a consumer company that also sells an API — roughly 60% of its annualized revenue came from consumers as 2026 began, though CFO Sarah Friar told investors in August 2026, per CNBC, that "those lines have now crossed." Anthropic sells mostly by consumption: about 44% of its revenue for the nine months ended September 30, 2026 came from sales through cloud-provider marketplaces, per the S-1/A. Its run rate topped $30 billion in April 2026, per Anthropic, and reached approximately $81 billion by October 31.
Anthropic Revenue Mix: Consumption vs. Subscription (9M 2026)
Consumption-based, pay-per-token revenue was 79% of Anthropic's nine-month 2026 revenue; subscriptions were 21%. The filing does not break revenue out by product.
Anthropic S-1/A No. 2 (Nov. 10, 2026): consumption-based $26.3B and subscription-based $6.9B of $33.2B revenue, nine months ended Sept. 30, 2026
Data
| Item | Value |
|---|---|
| Consumption-based (pay-per-token) | 79% |
| Subscription-based | 21% |
The Revenue Lines
Each channel monetizes the same underlying asset, Claude inference, but the buyer and contract shape differ. The S-1/A does not break revenue out by channel, so the last column shows only what the filing says.
| Revenue Line | Who Pays | Pricing Model | What the S-1/A says |
|---|---|---|---|
| Claude API | Developers & startups | Per million tokens (in/out) | Consumption-based: 79% of 9M 2026 revenue (all channels) |
| Enterprise contracts | Large companies | Committed-spend + volume discounts | Annual or multi-year minimum-spend contracts "result primarily in consumption-based revenue" |
| Claude Code | Engineering teams | Pay-for-intelligence, subscription, or both | Not broken out |
| Consumer (Pro/Max/Ultra) | Individuals | Subscription plans | Subscription-based: 21% of 9M 2026 revenue (all plans) |
| Cloud marketplaces (AWS, Google Cloud, Azure) | Cloud customers | Platform bills end customers and remits net of fees | About 44% of 9M 2026 revenue sold through CSP marketplaces |
Source: Anthropic S-1/A No. 2, nine months ended September 30, 2026. Anthropic does not publish a product-level revenue breakdown.
The API: The Engine of Anthropic's Revenue
The Claude API is the foundation. Developers call models like Claude Opus, Sonnet, and Haiku (see how they stack up in our ranking of the best AI models in 2026) and pay per token. As of late September 2026, Anthropic's list pricing runs from $10 per million input tokens and $50 per million output tokens for the top-end Claude Fable 5.1, to $4/$20 for Claude Opus 5.5 (launched September 22 at a lower price than Opus 5's $5/$25, with an $8/$40 Fast Mode), $2/$10 for Sonnet 5, and $1/$5 for Haiku 4.5. The 5x output-vs-input premium matters: generation is the expensive part, and coding workloads generate enormous output volume. Batch processing cuts costs roughly 50% and prompt caching cuts cached-input costs by about 90% — levers large customers use heavily, which compresses realized revenue per token even as volume climbs.
This tiered structure is itself a monetization strategy. A customer might use Haiku for cheap classification, Sonnet for the bulk of an agentic workflow, and Opus or Fable only for the hardest reasoning steps. Anthropic captures value across the entire price-performance curve instead of forcing one model on every job. Prompt caching and batch processing add further discounts that lock in high-volume customers.
Crucially, a large slice of revenue flows through cloud partners: about 44% of nine-month 2026 revenue came from sales through cloud-provider marketplaces, per the S-1/A. Amazon (which invested $5.0 billion in the Series H, per the S-1/A) resells Claude through AWS Bedrock, Google through Google Cloud, and Microsoft through Azure, where Anthropic's newest models launch alongside AWS and Google Cloud. These channels let Anthropic reach enterprise buyers who already have cloud commitments.
Enterprise and Claude Code: Where the Margin Lives
Enterprise contracts are the second pillar and the highest-quality revenue. Instead of metered pay-as-you-go, large customers sign committed-spend agreements — a company might commit to $5M, $20M, or far more per year in exchange for volume pricing, dedicated capacity, and security guarantees. This converts lumpy API usage into predictable, contracted revenue that investors value far more highly.
Claude Code deserves its own line because it became one of the fastest-growing products in the company's history. Launched as a terminal-native coding agent in 2025, it reached $1 billion in run-rate revenue in November 2025 and over $2.5 billion by February 2026, per Anthropic. The S-1/A does not break out Claude Code revenue and we have not found a later figure from Anthropic, so we do not estimate one. In the filing, Anthropic calls Claude Code the clearest manifestation of what it terms Virtual Collaborators, and says it is the product it believes has most concretely defined what autonomous work at the frontier looks like.
The filing offers one data point on why coding-heavy users matter: in the three months ended September 30, 2026, Claude Enterprise users who did not use Claude Code spent less than $75 per month on average, while the top 5% of Claude Enterprise users who used Claude Code spent approximately 20 times that amount (per the S-1/A).
Anthropic Revenue Growth: The Run-Rate Curve
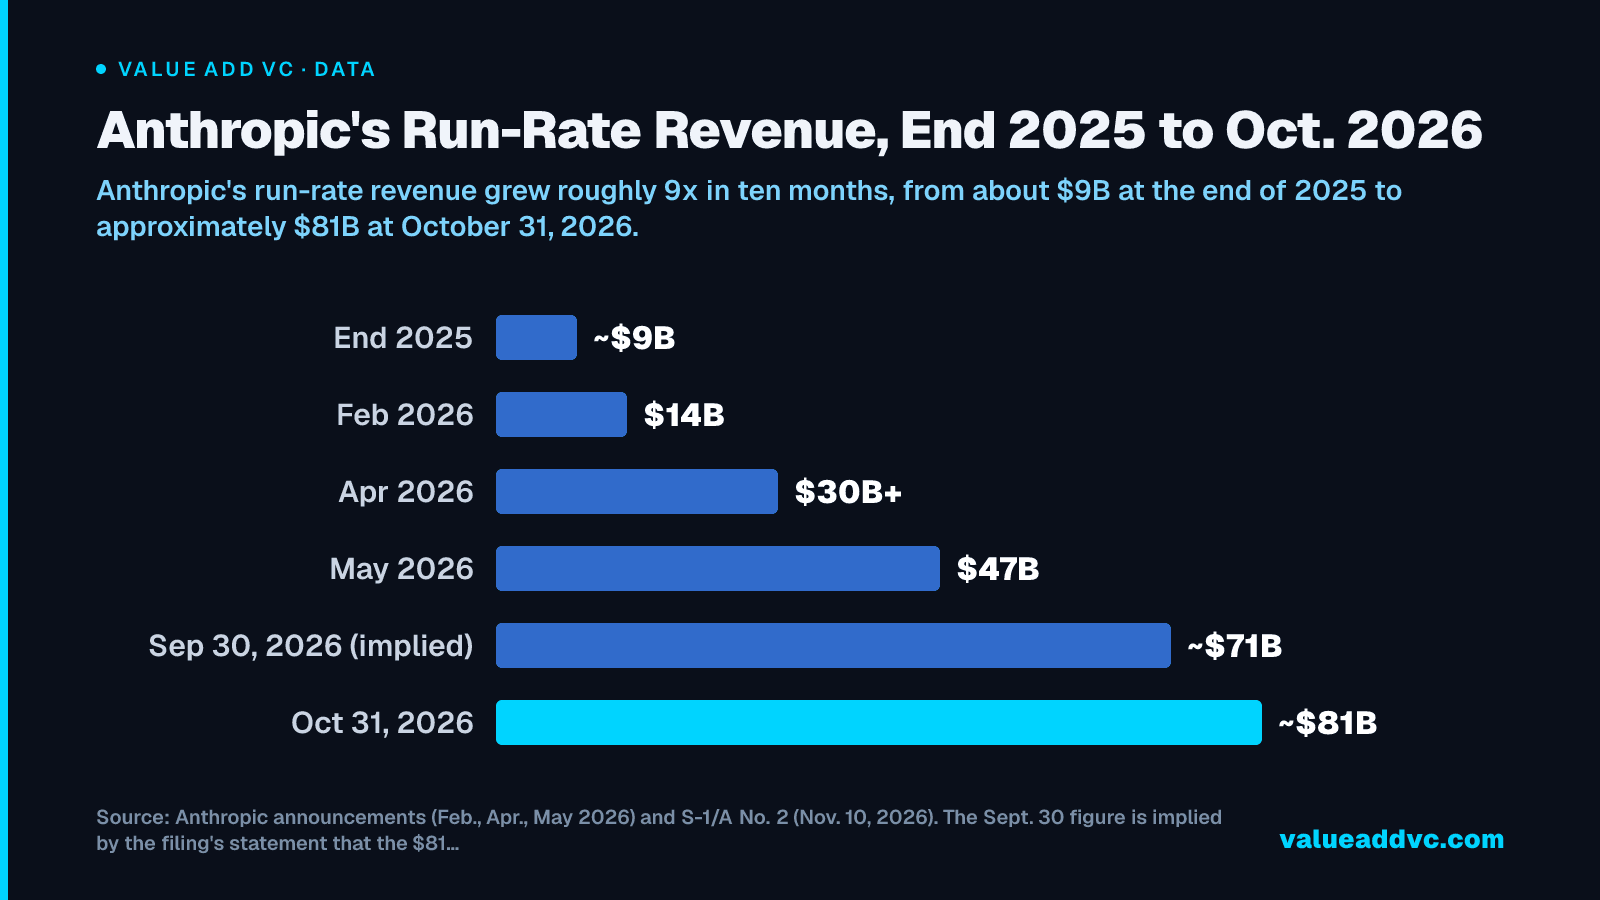
Anthropic's revenue trajectory is one of the steepest in software history. Per its S-1, revenue was $41 million in 2023, $386 million in 2024 and $4.585 billion in 2025. Run-rate revenue was approximately $9 billion at the end of 2025, per Anthropic, and $65 billion in July 2026, according to The New York Times, as reported by Gulf News. In September the New York Times reported a pace projected to top $100B by year-end, and early backers projected more than $110B, per Yahoo Finance. Updated Nov 2, 2026: per Anthropic's amended S-1, Q3 2026 revenue was $17.0 billion, up 1,127% year over year, after more than doubling from Q1 to Q2. Nine-month 2026 revenue reached $33.2 billion, up 1,206% year over year.
| Period | Annualized Run-Rate | Source |
|---|---|---|
| End 2025 | ~$9B | Anthropic (Apr. 6, 2026 announcement) |
| Feb 2026 | $14B | Anthropic Series G announcement (Feb. 12) |
| Apr 2026 | $30B+ | Anthropic (Apr. 6, 2026 announcement) |
| May 2026 | $47B | Anthropic Series H announcement (May 28) |
| Jul 2026 | $65B | NYT, as reported by Gulf News |
| Sep 30, 2026 | ~$71B (implied) | S-1/A No. 2: $81B at Oct. 31 was up $10B from Sep. 30 |
| Oct 31, 2026 | ~$81B | S-1/A No. 2 (Nov. 10, 2026); $17.0B booked in Q3 (amended S-1) |
Figures are annualized run-rates, not full-year recognized revenue. The S-1/A defines Run-Rate Revenue as trailing 28-day consumption-based fees multiplied by 13 plus monthly subscription fees multiplied by 12; earlier figures are company announcements and may use other methods.
Anthropic's Run-Rate Revenue, End 2025 to Oct. 2026
Anthropic's run-rate revenue grew roughly 9x in ten months, from about $9B at the end of 2025 to approximately $81B at October 31, 2026.
Anthropic announcements (Feb., Apr., May 2026) and S-1/A No. 2 (Nov. 10, 2026). The Sept. 30 figure is implied by the filing's statement that the $81B at Oct. 31 was up $10B.
Data
| Item | Value |
|---|---|
| End 2025 | ~$9B |
| Feb 2026 | $14B |
| Apr 2026 | $30B+ |
| May 2026 | $47B |
| Sep 30, 2026 (implied) | ~$71B |
| Oct 31, 2026 | ~$81B |
Is the AI Safety Company Actually Making Money?
Anthropic reported $974 million of GAAP operating income in Q2 2026 — its first quarter in the black on that basis — on revenue of more than $11.5 billion, more than double Q1's $4.73 billion, per its amended S-1 (filed Nov. 2, 2026). That didn't hold: Q3 2026 swung to a $567 million GAAP operating loss on $17.0 billion of revenue (+1,127% YoY), driven mainly by $5.0 billion of compute under short-term commitments and $2.0 billion of non-cash charges tied to Anthropic's donation-matching program. Adjusted Operating Income, which strips those items out, stayed positive in both quarters: $2.2 billion (19% margin) in Q2 and $2.5 billion (15% margin) in Q3. See our full breakdown of Anthropic's burn rate and path to breakeven for the cumulative picture. The nine-month 2026 GAAP net loss was $104.0 billion, driven by $94.3 billion of non-cash fair-value charges on convertible notes, on $33.2 billion of revenue. Those adjusted profits don't erase years of losses — full-year 2025 alone produced a $42.0 billion net loss — and compute commitments keep growing: Anthropic had entered into purchase commitments and leases with an aggregate committed spend of approximately $900.9 billion as of and subsequent to September 30, 2026, per Amendment No. 2.
The quarter also came as Anthropic's compute bill was stepping up: it agreed in May to pay SpaceX's xAI $1.25 billion a month for data-center capacity through May 2029, per TechCrunch, and more deals have followed, including a roughly $45 billion, six-year compute agreement with Nscale reported by TechCrunch in August. The WSJ reported in May that the company may not remain profitable for the full year due to planned spending increases for computing and model training. The FT reported in September that gross margins exceed 80% before revenue-sharing payments to partners such as Amazon and before training costs; each new model generation requires a fresh, larger training run before it earns a dollar, so the company is structurally spending ahead of revenue between profitable quarters.
To fund the gap between training and revenue, Anthropic has raised tens of billions in equity — the latest a $65B Series H announced May 28, 2026 at a $965B post-money valuation, per the company's announcement. Anthropic's IPO prospectus, whose financials TechCrunch reported on September 28, 2026, citing Reuters, showed full-year 2025 revenue of nearly $4.6 billion (a twelvefold increase) against an operating loss of more than $8 billion on nearly $13 billion of total operating expenses, with Q2 2026 revenue of $11.5 billion confirming the preliminary figure Fortune reported in August. TechCrunch reported the company could list above $2 trillion, and that it plans to spend $518 billion on cloud, computing and infrastructure in the coming years, per Reuters. Amendment No. 2 then set a price range of $70.00 to $78.00 for 825,000,000 Class A shares, with estimated net proceeds of about $84.6 billion at the midpoint including the concurrent private placement; the filing states no IPO valuation. The listing timeline has moved around in press reports (October, then November), and the prospectus itself doesn't fix an exact trading date. Updated October 2026: after Q3 growth slowed, some current and prospective investors are discussing a valuation of about $1.5 trillion rather than the roughly $2 trillion previously expected for the November share sale, Reuters reported in mid-October (via The Globe and Mail). Meanwhile revenue is concentrated at the top: no single customer was more than 10% of revenue for the nine months ended September 30, 2026, but the top five customers represented approximately 25%, per the S-1/A. The customer base keeps moving up-market: Anthropic had more than 1,900 customers with $1 million or more of TTM revenue as of September 30, 2026, per the filing.
What's Working
- ✓ Adjusted Operating Income positive in Q2 and Q3 2026 — $2.5B at a 15% margin in Q3 (amended S-1)
- ✓ 79% of nine-month 2026 revenue is consumption-based (S-1/A)
- ✓ Claude Code passed $2.5B run-rate by Feb 2026 (Anthropic)
- ✓ Cloud distribution via AWS, Google & Microsoft
What's Hard
- ✕ WSJ (May): may not stay profitable for full-year 2026
- ✕ $80.7B net loss in H1 2026 (incl. $72B non-cash charge), after $42B in 2025
- ✕ Training costs reset every model generation
- ✕ Price competition compressing token economics
What the profit headline misses
Two profitable quarters would be real progress, but that is not the same claim as "Anthropic is now profitable." On the filed numbers, Adjusted Operating Income was $2.2B in Q2 and $2.5B in Q3, while GAAP operating income was $974M in Q2 and a $567M loss in Q3. Adjusted operating income strips out certain costs, and the WSJ reported in May that the company may not remain profitable for the full year due to planned spending increases for computing and model training. The more useful signal now is the GAAP line in the filings, and whether Q4 2026 holds up as those compute commitments ramp.
Anthropic vs OpenAI: Two Opposite Business Models
The cleanest way to understand Anthropic's model is to put it next to OpenAI's. Both sell intelligence, but the revenue mix and go-to-market are mirror images.
| Attribute | Anthropic | OpenAI |
|---|---|---|
| Revenue run-rate | ~$81B (Oct. 31, 2026, S-1/A No. 2) | Almost $50B (Sept. 2026, per Reuters; first reported by the FT) |
| Q2 2026 quarterly revenue | $11.555B (S-1) | N/A (annual-only disclosures) |
| 2026 operating profit | Adjusted Operating Income $2.2B (19%) in Q2 and $2.5B (15%) in Q3; GAAP op. income +$974M in Q2, −$567M in Q3 (S-1/A) | Reported internal projection of a ~$14B 2026 loss (unconfirmed) |
| Primary revenue source | Consumption-based (79% of 9M 2026 revenue, S-1/A) | Consumer ~60% entering 2026; enterprise overtook consumer by Aug 2026 (CFO Friar, per CNBC) |
| Core buyer | Developers & enterprises | Consumers & prosumers |
| Standout product | Claude Code | ChatGPT |
| Key cloud backers | Amazon + Google (also sold via Microsoft Azure) | Microsoft |
Neither model is obviously better, but they carry different risks. OpenAI's consumer revenue is higher-margin and brand-defensible but exposed to churn and subscription fatigue. Anthropic's enterprise-and-API revenue is lower-glamour but stickier — once Claude is wired into a company's production systems, switching costs are real. For tracking how these valuations and multiples evolve, our AI Valuations dashboard follows the leading model companies side by side.
What the Model Tells Founders and Investors
Anthropic's structure is the clearest case study in the AI economy for a simple thesis: in foundation models, distribution through other people's software beats owning the end user. By making Claude the best model for agentic coding and embedding it everywhere through APIs and cloud marketplaces, Anthropic went from $41 million of revenue in 2023 to $17.0 billion in a single quarter (Q3 2026) without owning a consumer franchise — keeping Adjusted Operating Income positive for two straight quarters even as the GAAP operating line swung back to a loss in Q3. The full trajectory is in our breakdown of how Anthropic's revenue run rate has climbed.
The open question is whether token economics hold. As frontier models commoditize and competitors push prices down, the value migrates to whoever has the stickiest workflows and the most committed enterprise spend. Anthropic is betting that coding and enterprise lock-in are durable enough to outrun the price war. Given that 79% of its nine-month revenue is already consumption-based, it's a more defensible bet than the "AI safety company" framing would suggest. For how enterprise spend splits across the labs, see our breakdown of Anthropic's share of enterprise LLM spend.
The "safety company" framing buries the real story.
Anthropic sells intelligence by the token: 79% of its nine-month 2026 revenue is consumption-based, and it booked $17.0B in Q3 2026 alone.
More Anthropic Coverage
- Is Anthropic Profitable? — burn rate, cumulative losses, and the breakeven math.
- Anthropic Revenue Run Rate — how it passed OpenAI and kept climbing.
- Anthropic's Share of Enterprise LLM Spend: how enterprise model spend splits between Anthropic and OpenAI.
- $2T Anthropic IPO — what investors expect from the listing, with a prospectus now public and the timing still unsettled between reported October and November targets.
Track AI company valuations and revenue multiples on the AI Valuations Dashboard at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗