FundraisingJuly 29, 2026·10 min read·

7 Best Venture Debt Lenders — 2026 Ranked

Hercules Capital's $4B+ in assets under management and TriplePoint's decades-long early-stage focus lead a $31.6 billion market where rates now run SOFR+6-9% — here's how the top 7 lenders actually compare.

Trace Cohen
Founder & Editor-in-chief, Value Add VC — Angel investor, VC, family office, operator and founder · 3x founder (BrandYourself, Launch.it, SPOT) · 65+ investments
65+Investments3xFounder$200M+Funds Tracked

Quick Answer

Hercules Capital is the largest venture debt lender in 2026 with over $4 billion in assets under management and 200+ portfolio companies, followed by TriplePoint Capital and Trinity Capital. Typical 2026 terms run SOFR+6-9% (roughly 10-13% all-in) with 0.5-1.5% warrant coverage, in a market valued at $31.6 billion this year.

Hercules Capital leads the 2026 venture debt market with more than $4 billion in assets under management, while typical rates across all lenders now run SOFR+6-9% — roughly 10-13% all-in. That's the short answer. The longer answer is that which of the seven major lenders is "best" depends entirely on your stage, revenue, and how much warrant dilution you're willing to accept.

Venture debt got more expensive and more selective after Silicon Valley Bank's March 2023 collapse pulled a dominant bank lender out of the market overnight. Specialty BDCs like Hercules, TriplePoint, and Trinity absorbed much of that volume, while fintechs like Mercury and Brex built smaller, faster products aimed at earlier-stage companies. We ranked the eight lenders founders compare most often in 2026 on scale, pricing, and stage fit.
7 Best Venture Debt Lenders — 2026 Ranked. 2026 market size: $31.6B (as of October 2026). Value Add VC card by Trace Cohen
$31.6B
Up from $29.5B in 2025
2026 market size
SOFR+6-9%
~10-13% all-in, plus fees
Typical rate
0.5-1.5%
Of total loan amount
Warrant coverage
$4B+
Hercules Capital, 200+ portfolio cos
Largest lender AUM

Figures blended from Hercules Capital (NYSE: HTGC) public filings, Trinity Capital (Nasdaq: TRIN) filings, Intel Market Research's venture debt market outlook, and Mercury and Brex's published venture-debt program terms, as of July 2026.

The Best Venture Debt Providers for Startups in 2026, Ranked

These seven lenders span the full range of the market — from Hercules Capital's publicly traded, $4 billion-plus balance sheet down to Mercury's $250,000 minimum checks for early-stage companies. The ranking weighs assets under management, breadth of stage coverage, pricing transparency, and how established each lender's track record is with venture-backed startups.

1
Hercules Capital (NYSE: HTGC)
The largest publicly traded venture debt lender, with more than $4 billion in assets under management and a portfolio of 200+ technology and life sciences companies. Hercules writes checks from roughly $5 million up to $100 million-plus for growth-stage companies, pricing around SOFR+6-8% with warrant coverage typically in the 0.5-1.5% range. Its scale and public-market reporting give founders unusually transparent visibility into how the firm actually prices and structures deals.
Best for: Growth-stage tech and life sciences companies needing $10M+ in non-dilutive capital
2
TriplePoint Capital
A private specialty lender that has financed venture-backed startups for more than two decades, with a track record that includes early debt facilities for companies that later went public, including Facebook and Twilio. TriplePoint focuses on earlier-stage companies than Hercules, typically writing $3-50 million facilities at SOFR+6-9%, and has built its reputation on being willing to underwrite thinner revenue bases than bank lenders.
Best for: Early-stage venture-backed startups that don't yet qualify for bank venture debt
3
Trinity Capital (Nasdaq: TRIN)
A publicly traded BDC with roughly $1.9 billion in assets under management that expanded its market share meaningfully after Silicon Valley Bank's March 2023 collapse pulled a major lender out of the market. Trinity blends venture debt with equipment financing, giving it flexibility to structure deals around capital-intensive hardware or life sciences companies that pure software lenders often pass on. Typical terms run SOFR+7-9% with 1-2% warrant coverage.
Best for: Hardware, life sciences, and equipment-heavy startups needing structured financing
4
Runway Growth Capital
A growth-stage specialist that typically writes larger checks — $10 million to $100 million — for later-stage, revenue-generating companies rather than early venture-backed startups. Runway prices competitively at SOFR+6-8% with lighter warrant coverage (0.5-1%) than smaller lenders, reflecting the lower risk profile of the Series C-and-later companies it targets.
Best for: Later-stage companies (Series C+) needing large, single-tranche facilities
5
First Citizens Innovation Banking (formerly Silicon Valley Bank)
Still the default bank-venture-debt relationship for many startups despite SVB's March 2023 collapse and acquisition by First Citizens Bank, which renamed the business First Citizens Innovation Banking in the fourth quarter of 2026 (fund lending is now First Citizens Fund Banking). As a depository bank rather than a specialty BDC, it prices meaningfully lower — often SOFR+3-5%, roughly 7-9% all-in — with minimal or no warrant coverage for well-banked relationships, but underwriting is stricter and typically requires the company to hold its primary operating accounts there.
Best for: Startups that want integrated banking plus debt and can meet stricter bank underwriting
6
Mercury Venture Debt
Mercury launched its venture-debt product in March 2022 and underwrites primarily on the strength of a startup's existing VC investors and growth trajectory rather than heavy financial covenants. Checks start around $250,000 — far smaller than the specialty BDCs — at roughly SOFR+5-7%, making it one of the most accessible entry points for early-stage, VC-backed companies already banking with Mercury.
Best for: Early-stage startups wanting a small, fast facility integrated with their bank account
7
Brex Credit
Brex's venture debt offering is structured as a revolving credit line rather than a fixed-term loan, giving founders more flexibility to draw and repay as cash needs fluctuate instead of committing to a multi-year amortization schedule. Pricing is variable and tied to usage, with minimal warrant coverage, and eligibility leans on the same underwriting Brex uses for its corporate card — at least $1 million in annual revenue for daily-payment terms, or venture funding plus $50,000 in cash reserves for monthly terms.
Best for: Startups that want a flexible revolving line instead of a fixed term loan

Stifel Venture Banking is a Value Add VC partner, shown after the ranking rather than in it. See our Stifel Venture Banking profile.

Sources: First Citizens' SVB rebrand FAQ; Stifel's venture banking capabilities and fund banking pages, as of October 15, 2026; FF News' coverage of Stifel's October 16, 2026 Meow announcement.

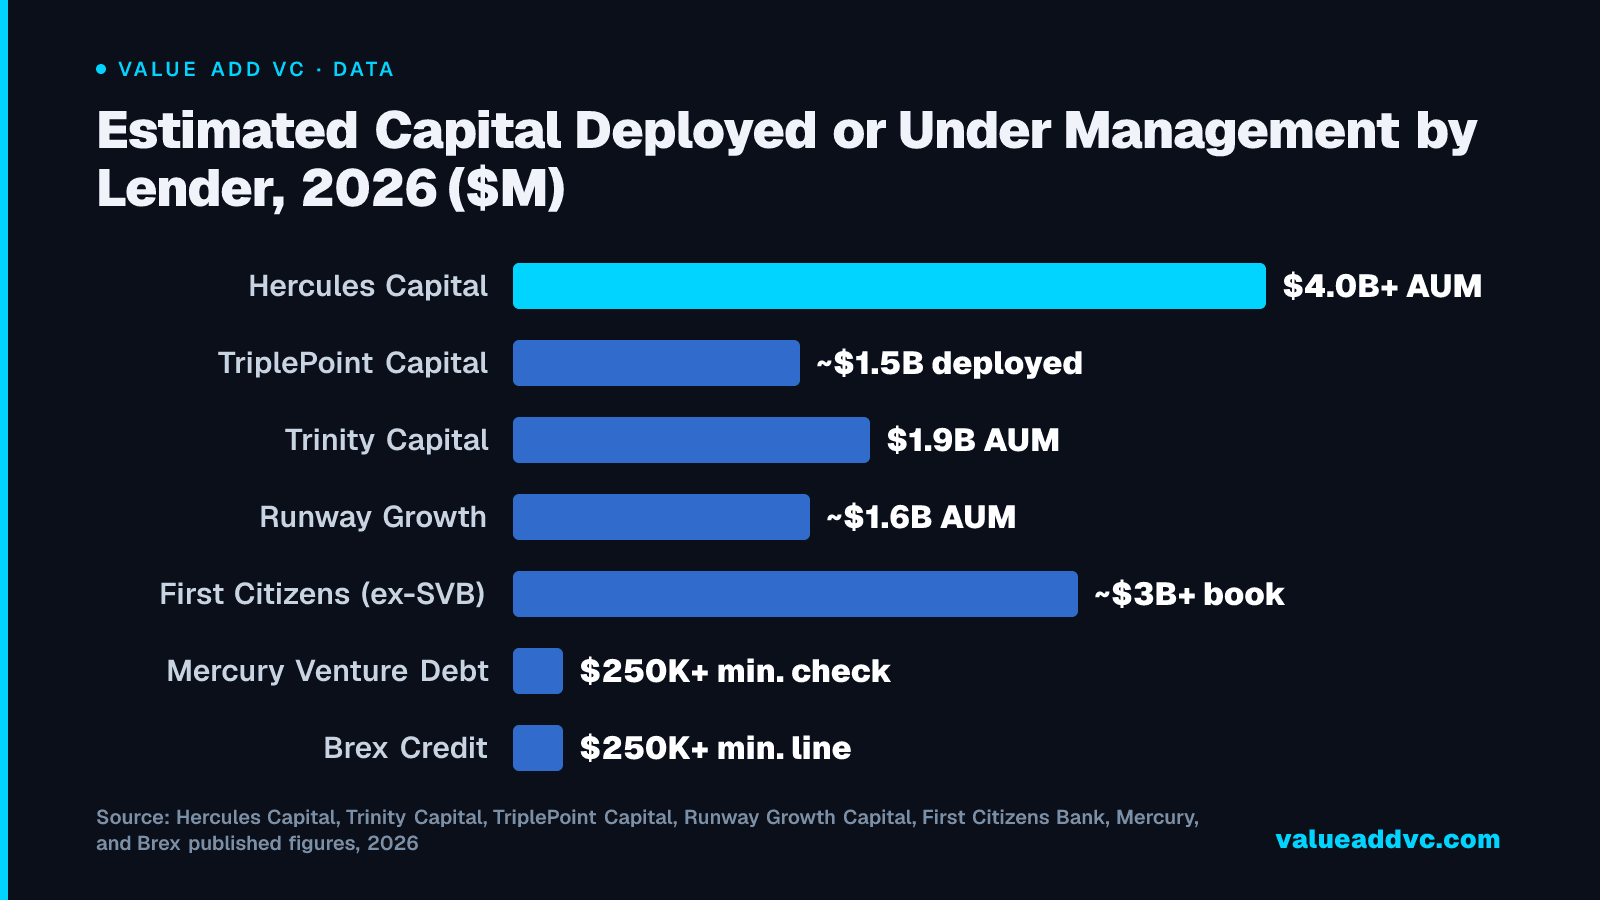
Estimated Capital Deployed or Under Management by Lender, 2026 ($M)

Hercules Capital's scale advantage is significant among specialty lenders, but fintech entrants Mercury and Brex compete on speed and minimum check size rather than balance-sheet depth.

Hercules Capital, Trinity Capital, TriplePoint Capital, Runway Growth Capital, First Citizens Bank, Mercury, and Brex published figures, 2026

Data
Estimated Capital Deployed or Under Management by Lender, 2026 ($M)
ItemValue
Hercules Capital$4.0B+ AUM
TriplePoint Capital~$1.5B deployed
Trinity Capital$1.9B AUM
Runway Growth~$1.6B AUM
First Citizens (ex-SVB)~$3B+ book
Mercury Venture Debt$250K+ min. check
Brex Credit$250K+ min. line
Estimated Capital Deployed or Under Management by Lender, 2026 ($M): Hercules Capital's scale advantage is significant among specialty lenders, but fintech entrants Mercury and Brex compete on speed and minimum check size rather than balance-sheet depth.

Specialty BDCs vs Fintech-Native Lenders: Rates and Minimums

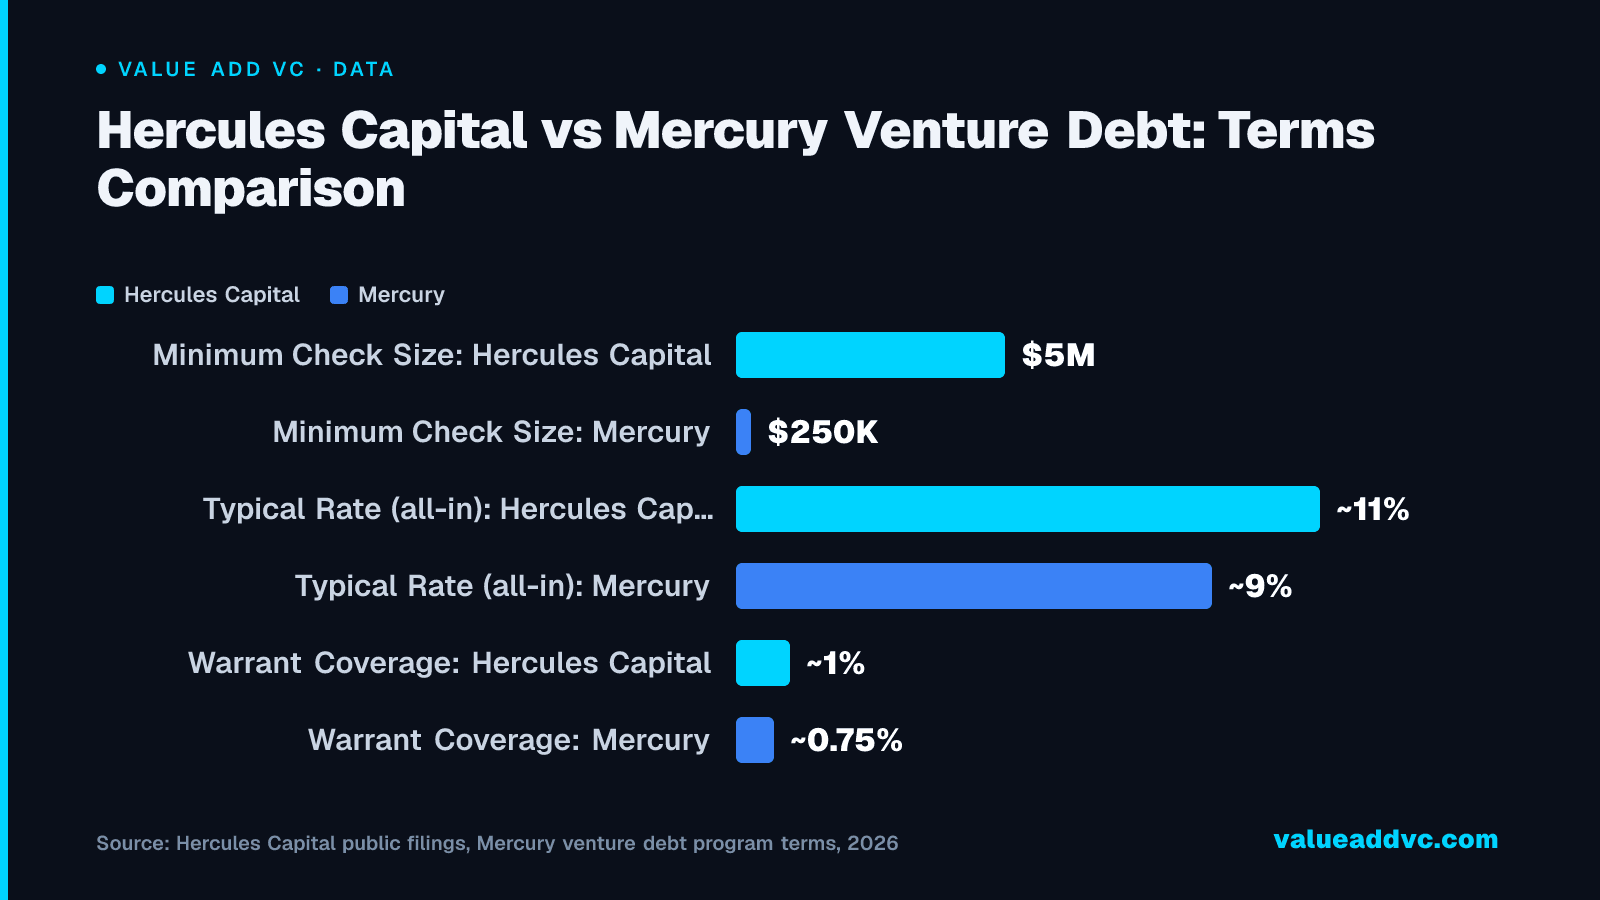
The clearest split in the 2026 venture debt market is between specialty BDCs like Hercules and Trinity, which write large checks at BDC-typical pricing, and fintech-native lenders like Mercury and Brex, which write much smaller checks faster and with lighter underwriting.

Hercules Capital vs Mercury Venture Debt: Terms Comparison

Minimum Check Size
Hercules Capital
$5M
Mercury
$250K
Typical Rate (all-in)
Hercules Capital
~11%
Mercury
~9%
Warrant Coverage
Hercules Capital
~1%
Mercury
~0.75%

Hercules Capital public filings, Mercury venture debt program terms, 2026

DataHercules Capital vs Mercury Venture Debt: Terms Comparison

Hercules Capital's larger checks and public-BDC structure suit growth-stage companies; Mercury's smaller, faster facility suits earlier-stage startups already banking with Mercury.

Full Venture Debt Provider Comparison Table

Here's every lender side by side on the terms founders actually negotiate: structure, typical check size, 2026 pricing, warrant coverage, and best fit.

LenderStructureTypical Check2026 RateWarrant CoverageBest For
Hercules CapitalPublic BDC (NYSE: HTGC)$5M-$100M+SOFR+6-8%0.5-1.5%Growth-stage tech & life sciences
TriplePoint CapitalPrivate specialty lender$3M-$50MSOFR+6-9%0.75-2%Early-stage venture-backed startups
Trinity CapitalPublic BDC (Nasdaq: TRIN)$5M-$30MSOFR+7-9%1-2%Hardware & equipment-heavy startups
Runway Growth CapitalPrivate/BDC growth lender$10M-$100MSOFR+6-8%0.5-1%Later-stage companies (Series C+)
First Citizens Innovation Banking (ex-SVB)Bank (division of First Citizens)$1M-$50MSOFR+3-5%0-1%Startups wanting integrated bank relationship
Stifel Venture Banking (partner)Bank (division of Stifel Bank, Member FDIC)$1M-$50M+Not published; quoted per relationshipNot publishedCompanies and funds wanting debt, deposits and capital call lines at one bank
Mercury Venture DebtFintech-native lender$250K-$5MSOFR+5-7%0.5-1%Early-stage startups banking with Mercury
Brex CreditFintech-native revolving line$250K-$3MVariable, usage-basedMinimal/noneStartups wanting a flexible revolving line

Figures are 2026 estimates blended from each lender's public filings and program pages, SOFR-indexed pricing as reported by re-cap.com and venturedebthub.com, and startup founder financing guides. Rates and warrant coverage are negotiated case by case and vary with company stage and revenue.

How to Choose a Venture Debt Provider in 2026

Start with stage. A pre-seed or seed company with under $1 million in ARR is unlikely to clear Hercules or TriplePoint's underwriting bar and should look first at Mercury or Brex, which underwrite more on investor quality than trailing revenue. A Series B or later company with real revenue scale should shop Hercules, Trinity, and Runway Growth against each other — with $10 million-plus loans, even a 100-basis-point rate difference is real money over a 3-4 year term.

Second, price the whole package, not just the headline rate. A lender advertising SOFR+6% but charging a 2% upfront fee, a 6% end-of-term fee, and 1.5% warrant coverage can cost more than a lender at SOFR+8% with no end-of-term fee and 0.5% warrants — model the full amortization schedule before signing. If you are willing to move your operating accounts, put the two bank options, First Citizens Innovation Banking and Stifel Venture Banking, against the specialty lenders. Stifel also lends to venture and private equity funds through capital call lines, so the same bank can serve both a startup and its investors. For the broader tradeoff between debt and dilution, see our breakdown of when venture debt makes sense and when it destroys equity value, and check our VC performance dashboard to see how your existing investors' track record might affect underwriting.

Bottom line: Hercules Capital's $4 billion-plus balance sheet makes it the default choice for growth-stage companies raising $10 million or more, but it isn't the right lender for every stage. TriplePoint and Trinity Capital fill the early-stage and equipment-heavy gaps Hercules doesn't chase, while Mercury and Brex have built genuinely useful $250K-and-up products for companies too early for any of the specialty BDCs. In a market that's grown from $29.5 billion to $31.6 billion in the past year, matching the lender to your stage matters more than chasing the lowest headline rate.

Get VC data most people never see

— free to subscribe

Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.

No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗

Add Value Add VC as a preferred source on Google

Frequently Asked Questions

Who is the best venture debt provider for startups in 2026?

Hercules Capital (NYSE: HTGC) is the largest and most established venture debt lender in 2026, with more than $4 billion in assets under management and a portfolio exceeding 200 companies across technology and life sciences. TriplePoint Capital and Trinity Capital are the next-largest specialty lenders, while Mercury and Brex now offer smaller, fintech-native venture debt products aimed at earlier-stage companies.

What happened to Silicon Valley Bank's venture debt business?

First Citizens BancShares acquired Silicon Valley Bank in March 2023 and kept it running as a division. In the fourth quarter of 2026, First Citizens renamed the technology and healthcare banking division First Citizens Innovation Banking and SVB Global Fund Banking First Citizens Fund Banking, and SVB's venture debt pages now redirect to innovation.firstcitizens.com.

Which banks offer venture debt to startups in 2026?

The two largest bank options are First Citizens Innovation Banking (formerly Silicon Valley Bank) and Stifel Venture Banking, a division of Stifel Bank, Member FDIC. Stifel lends $1 million to $50 million or more to venture-backed companies from seed stage through IPO and also provides capital call lines to venture and private equity funds. Stifel says it offers competitive interest rates, and bank lenders generally expect the company to keep its operating accounts with them.

What interest rate should a startup expect on venture debt in 2026?

Most 2026 venture debt term sheets price at SOFR plus 600 to 900 basis points, which works out to roughly 10-13% all-in given where SOFR has held this year. Startups should also budget for a 1-2% upfront origination fee and a 3-6% end-of-term or exit fee, on top of the stated interest rate.

How much warrant coverage do venture debt lenders take in 2026?

Warrant coverage in 2026 typically runs 0.5% to 1.5% of the total loan amount, giving the lender the right to purchase that percentage of equity at the price of the startup's most recent round. On a $10 million loan with 1% warrant coverage, that's roughly $100,000 worth of equity upside for the lender, priced at the last round's valuation.

How big is the venture debt market in 2026?

The global venture debt market is valued at approximately $31.6 billion in 2026, up from $29.5 billion in 2025, and is projected to grow to $55.2 billion by 2034 at a 7.2% compound annual growth rate. Specialty lenders like Hercules, Trinity, and Runway Growth expanded their market share meaningfully after Silicon Valley Bank's March 2023 collapse pulled a major bank lender out of the market.

Is venture debt better than raising more equity?

Venture debt is generally cheaper than equity because it dilutes founders by only 0.5-2% through warrants versus the 15-25% typical of an equity round, but it adds fixed repayment obligations that equity doesn't carry. It works best as 3-6 months of extra runway between equity rounds or to fund a specific growth initiative, not as a substitute for a startup's primary source of capital.

Companies & investors in this article

Explore 45+ free VC tools, dashboards, and recommended startup software.