
Updated Oct 4, 2026
Re-checked every figure below as of October 4, 2026. Carta's Q2 2026 VC Startup Fundraising Benchmarks report (published July 10, 2026) remains the latest available — Carta had not yet published a Q3 2026 edition as of this update, so the sector table and the $191M blended pre-money figure are unchanged. XDOF's reported $1.2B Series B talks with 8VC also remain unclosed as of October 4, 2026 — no outlet has reported a signed term sheet or close. Sharpened this post's title and description to target "Series B valuation multiple" directly, since that is now one of this page's highest-impression search queries.
The average Series B funding amount — $28M as of data through Q1 2026 — is a useful anchor, but that single number will get you killed in a fundraise if you anchor to it wrong.
The range runs from $15M in commoditized vertical SaaS to $75M+ for AI-native infrastructure companies with triple-digit ARR growth. Where you land depends on sector, retention, growth rate, and whether your story fits the current market narrative. I have watched founders come in asking for $30M Series B when the data for their sector says $20M is the ceiling — and wonder why the process stalled.
Here is what the latest data — through Q1 2026 — actually shows, broken down by sector and what it means for how you should position your raise. For the post-money side of this same data set, see our breakdown of where Series B post-money valuations have landed for founders in 2025.
Average Series B Funding Amount in 2026: Data by Sector
Series B data varies significantly by vertical. Below are the median round sizes, post-money valuations, and ARR multiples by sector based on PitchBook, Carta, and NFX data through Q1 2026.
| Sector | Median Round | Post-Money Valuation | ARR Multiple |
|---|---|---|---|
| AI Infrastructure / Foundation | $45–75M | $200–400M | 25–40x |
| AI SaaS (Vertical) | $25–40M | $130–200M | 18–28x |
| Fintech / Payments | $25–35M | $120–180M | 12–20x |
| Enterprise SaaS | $18–28M | $100–150M | 12–18x |
| Cybersecurity | $25–40M | $140–200M | 15–22x |
| Health Tech / Digital Health | $20–35M | $100–160M | 10–16x |
| Defense / Dual-Use Tech | $30–60M | $150–300M | N/A (contract-based) |
| Developer Tools / Infra | $20–35M | $110–175M | 15–25x |
Sources: PitchBook Q1 2026, Carta State of Private Markets, NFX Financing Benchmarks. Ranges reflect 25th–75th percentile.
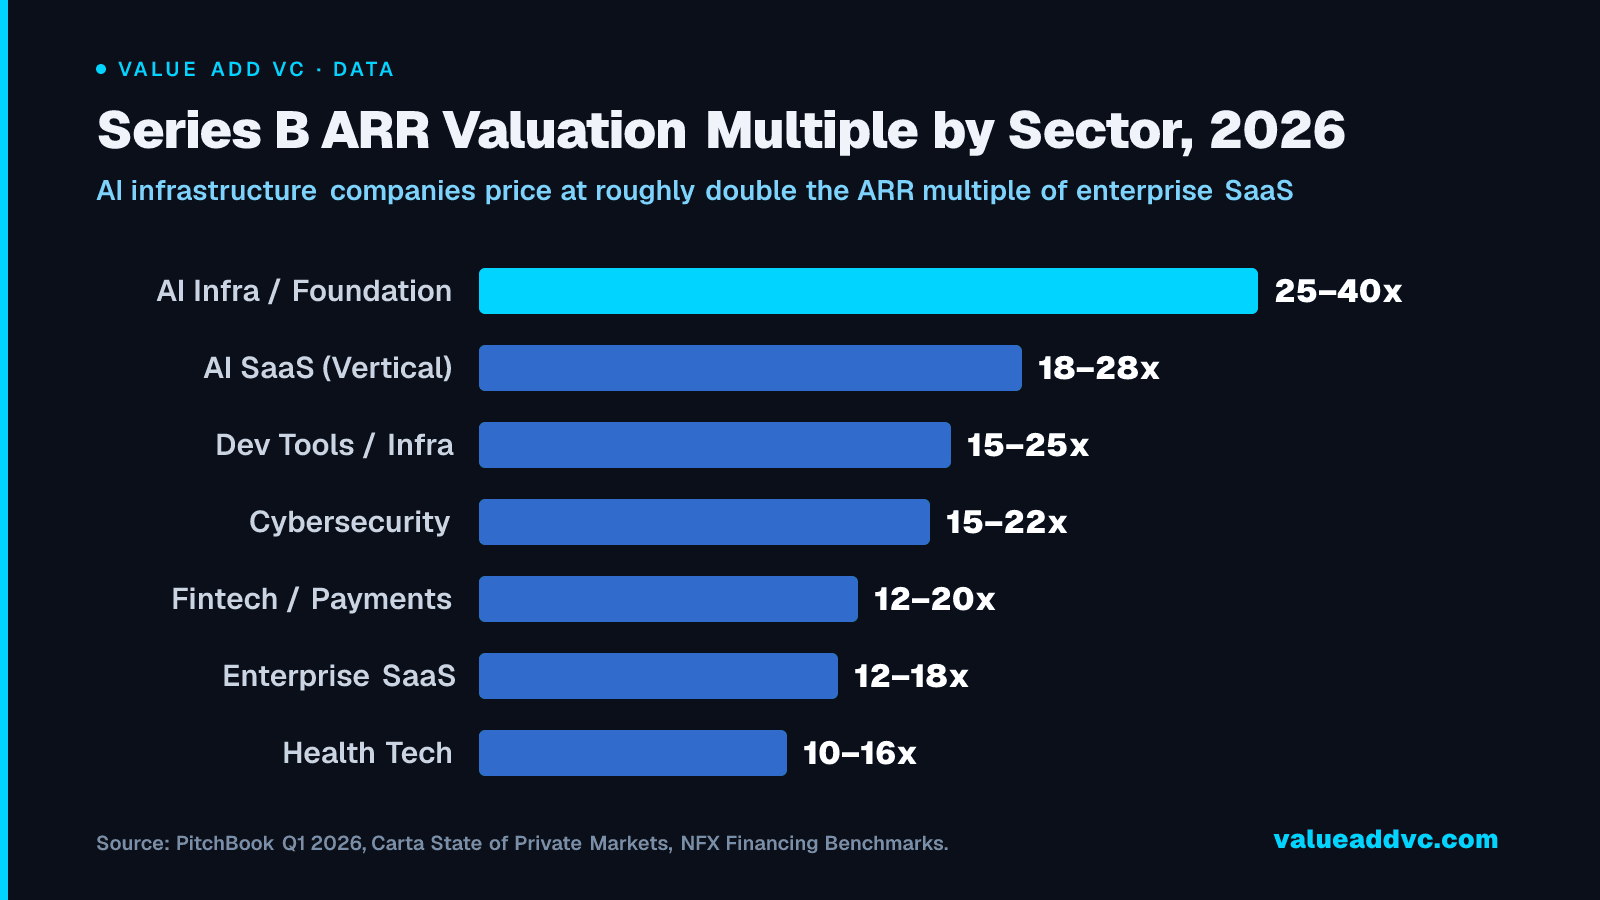
Series B ARR Valuation Multiple by Sector, 2026
AI infrastructure companies price at roughly double the ARR multiple of enterprise SaaS
PitchBook Q1 2026, Carta State of Private Markets, NFX Financing Benchmarks.
Data
| Item | Value |
|---|---|
| AI Infra / Foundation | 25–40x |
| AI SaaS (Vertical) | 18–28x |
| Dev Tools / Infra | 15–25x |
| Cybersecurity | 15–22x |
| Fintech / Payments | 12–20x |
| Enterprise SaaS | 12–18x |
| Health Tech | 10–16x |
Update, Q2 2026: Series B Pricing Moved Again
The Q1 2026 data above is already dated. In its Q2 2026 VC Startup Fundraising Benchmarks report, published July 10, 2026, Carta put the median Series B post-money valuation for software companies at $191M on rounds raised in the trailing six months — well above the $118.9M median primary pre-money valuation Carta had recorded just two quarters earlier, in its Q3 2025 State of Private Markets report, though setting a post-money figure against a pre-money one overstates the jump.
The Q2 2026 PitchBook-NVCA Venture Monitor attributes most of that move to concentration, not a broad re-rating: AI accounted for 86% of all U.S. venture dollars in the first half of 2026, and deals of $100M or more captured 87.5% of the $412.7B deployed in H1 2026. Series B primary pre-money valuations were up 17.2% versus Q1 2025, per Carta data cited in the same report. Three firms alone — Andreessen Horowitz, Thrive Capital, and Founders Fund — accounted for 48.1% of all capital raised in the period.
The practical read for founders: median Series B pricing is genuinely higher entering the back half of 2026, but a meaningful share of that increase is a handful of AI megadeals pulling the average up, not every Series B company getting repriced. If your round isn't in the AI infrastructure or AI-native SaaS categories from the table above, anchor to the Q1 2026 sector ranges rather than the blended $191M headline — per Carta's own July 2026 report, that figure skews heavily toward the software companies raising the biggest, most AI-adjacent rounds.
What Series B Investors Actually Require in 2026
The bar to raise a Series B has risen materially since the 2021 peak. Back then, you could raise a $30M B on $2M ARR with a good story and a hot sector. Today, that story needs to be backed by numbers that de-risk the next leg of growth. I have seen strong companies with $4M ARR struggle because they could not show a repeatable GTM motion — and that is the unlock investors are underwriting.
The typical Series B investor in 2026 is looking for: $3–10M ARR (sector-dependent), net revenue retention above 110%, year-over-year growth above 80%, a go-to-market motion that has worked at least two or three quarters in a row, and a clear path to $50M ARR within 24–30 months. Below those thresholds, you are either doing a bridge or negotiating hard for terms that reflect the risk.
The exception is AI infrastructure. Foundation model tooling, GPU orchestration, and agentic workflow infrastructure companies are still raising pre-revenue or near-revenue rounds at enormous valuations. Even earlier-stage security plays are catching that same tailwind — Hush Security's $30M round to govern AI agent identity landed as a Series A, not a B, but at a size and pace that would have been a Series B check three years ago. That is a narrow band — do not mistake the exception for the rule. For everything else, the metrics bar is real.
How Series B Valuations Are Calculated
Series B valuations in 2026 are set almost entirely on forward ARR multiples — specifically, your projected ARR twelve months out multiplied by a comparable public SaaS or AI company multiple, then discounted for stage risk and illiquidity. The practical shorthand: take your NTM ARR estimate, apply a 12–18x multiple for SaaS or 20–35x for AI-native, and that is your pre-money valuation range before negotiation.
Public SaaS multiples as of Q1 2026 sit around 7–9x NTM revenue for the median public software company, per our SaaS Valuations dashboard. Private companies at Series B get a growth premium — typically 1.5–2x the public comparable — because they are growing faster than anything public. That premium compresses quickly if growth slows.
Net revenue retention is the single highest-correlation lever on the multiple. Companies with 130%+ NRR can command the top of the range. Companies at 90% NRR are fighting uphill. I have seen two identical-ARR companies get $80M apart in Series B valuation because one had 140% NRR and the other had 95%. Retention is not a nice-to-have — it is the math.
A Live Series B Valuation Multiple, October 2026: The XDOF Deal
As of early October 2026, the clearest real-world read on where a Series B valuation multiple can land comes from XDOF, a robotics-data startup reportedly in talks for a Series B at a $1.2 billion valuation led by 8VC, according to TechCrunch's September 4, 2026 report. The round had not closed as of that report, so the number is a negotiating price rather than a confirmed post-money valuation. Against XDOF's annualized revenue of roughly $50 million, that works out to a revenue multiple of about 24x — just under the 25–40x band this post's sector table assigns to AI infrastructure, consistent with XDOF still being early in its revenue base. As of October 4, 2026, no outlet has reported the round as closed, so the $1.2B figure remains a reported talks price rather than a priced Series B. For the deal timeline, the investors involved, and how it stacks up against Figure AI, Skild AI, and Physical Intelligence, see our full breakdown of XDOF's Series B talks.
Treat the 24x figure as one data point, not a market average. XDOF's revenue is young — it left stealth only about three months before these talks began — and concentrated across roughly 20 customers, the kind of profile that gets priced at a premium multiple because investors are underwriting continued growth, not because a 24x multiple is typical for a $50M-revenue company outside AI infrastructure. A SaaS company with the same $50M run rate, priced at this post's 12–18x Enterprise SaaS band, would be worth $600–900M — roughly a third to half of XDOF's reported number. That gap is the sector premium in practice, not a rounding error.
5 Factors That Move Your Series B Valuation
- •Net Revenue Retention above 120% — the single highest-correlation metric to a premium valuation at Series B. Every point below 110% costs you multiple turns on the ARR multiple.
- •Growth rate trajectory — investors look at trailing 3-quarter CAGRs, not point-in-time snapshots. Deceleration from 150% to 80% growth tells a different story than consistent 90% growth.
- •Gross margin — 70%+ is table stakes for SaaS; sub-60% puts you in a different multiple bucket. AI companies burning compute costs often show 50–65% margins which require a different framing.
- •Capital efficiency — Series B investors are comparing your ARR-per-dollar-raised to cohort medians. Companies that reached $5M ARR on $8M raised are dramatically more interesting than those who needed $20M to get there.
- •Pipeline quality and GTM repeatability — the question every Series B lead is asking: can this company 3x revenue in 24 months with the capital from this round? If the GTM machine is not clearly working, the answer is no.
Series B Dilution: What Founders Give Up
The typical Series B investor takes 15–22% of the company. When you stack that on top of pre-seed (5–10%), seed (10–20%), and Series A (15–25%) dilution, the math gets uncomfortable fast. Most founders who have raised three rounds own somewhere between 30–50% of their company before any option pool refreshes or SAFE conversions.
The option pool shuffle is real at Series B. Most term sheets will require expanding the employee option pool to 10–15% on a post-money basis, and that dilution is typically carved out of the pre-money cap table — meaning it dilutes founders, not new investors. A $130M post-money B with a 12% option pool expansion effectively means founders give up more than the headline dilution number suggests.
The best protection against excessive dilution at Series B is a competitive process. A single-term-sheet situation gives investors pricing power. Two or more term sheets creates real negotiating leverage — on valuation, option pool size, pro-rata rights, and governance. Running a tight, time-boxed process with genuine competitive tension is not optional; it is how you protect your cap table.
The 2026 Funding Context: Why Series B Is Harder Than It Looks
According to PitchBook data, the number of Series B rounds completed in 2024 was down approximately 35% from the 2021 peak. Capital is concentrating in the top quartile of deals — the companies with the best metrics get multiple term sheets quickly; everyone else waits. The Series A to Series B conversion rate is roughly 30–40% industry-wide, meaning most companies that raise a Series A never make it to a Series B.
The implication: if you are planning a Series B raise in 2026 or 2027, start building LP relationships with growth equity firms 12–18 months before you need capital. The firms writing $25–50M checks at Series B have seen hundreds of companies. The ones they move fast on are the ones they have tracked for a year, seen execute consistently, and already trust. Cold inbound at Series B is a much harder path than most founders expect. You can track how funding rounds are evolving in real time on the Benchmarking Dashboard.
The average Series B is $28M — but the median company that should raise a Series B is not average. Know your sector benchmarks, nail your NRR, and run a process. Everything else is negotiable.
Track startup funding benchmarks in real time on the Benchmarking Dashboard at Value Add VC. Originally published in the Trace Cohen newsletter.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗