
Updated Nov 2, 2026: Added Amazon's Q3 2026 results — AWS revenue hit $46.0B (+39% YoY, its fastest growth in nearly five years), the AWS backlog rose to $578B, and quarterly capex jumped to $77.3B — while full-year 2026 capex guidance held at $220B.
Amazon raised its 2026 capital expenditure guidance to roughly $220 billion on its July 30, 2026 earnings call — up 76% from about $125 billion in 2025 and up again from the $200 billion guidance it had set earlier in the year — with nearly all of it going into AWS data centers, power capacity, and AI chips. Underneath that number, AWS is running two AI infrastructure strategies at once: buying more Nvidia GPUs than almost anyone else on the planet, while simultaneously building its own chip to make that dependence smaller.
I track hyperscaler capex closely because it's the clearest leading indicator of where AI demand actually is, not where the hype says it should be. Amazon's Q3 2026 numbers extended the same signal: full-year capex guidance held at $220 billion, AWS's fastest revenue growth in nearly five years, and a backlog that keeps compounding faster than the company can build data centers to fill it. Here's what the numbers actually show.
Figures are from Amazon's Q3 2026 earnings release (filed with the SEC October 29, 2026) and its Q3 2026 10-Q (filed October 30, 2026), which disclosed AWS's $578B in unrecognized long-term contract commitments.
How Much Is Amazon Spending on AWS AI Investment in 2026?
Amazon's AWS AI investment is now on track to hit roughly $220 billion in total 2026 capital expenditures — up from about $125 billion in 2025, a 76% year-over-year increase — after management raised guidance for the second time this year on its July 30, 2026 earnings call. Amazon spent $54.2 billion on capex in the second quarter of 2026 alone, up from $32.1 billion in the same quarter of 2025, and CEO Andy Jassy told analysts that "even at that amount, we will still not have enough capacity to meet all the demand we have in 2026," adding he expects the same supply-demand imbalance to persist into 2027.
The spending is split across three buckets: data center construction and the power infrastructure to run it, networking and Nitro-based virtualization hardware, and compute silicon — both Nvidia GPUs and Amazon's own Trainium and Graviton chips. Amazon has said it plans to deploy more than 1 million Nvidia GPUs starting in 2026, even as it pushes its own silicon harder, which tells you AWS sees the AI compute market as large enough to need both strategies running in parallel rather than one replacing the other. Amazon also flagged rising memory prices as one reason the 2026 capex number moved higher than its original guidance.
Amazon vs. Microsoft, Google, and Meta: 2026 AI Capex Compared
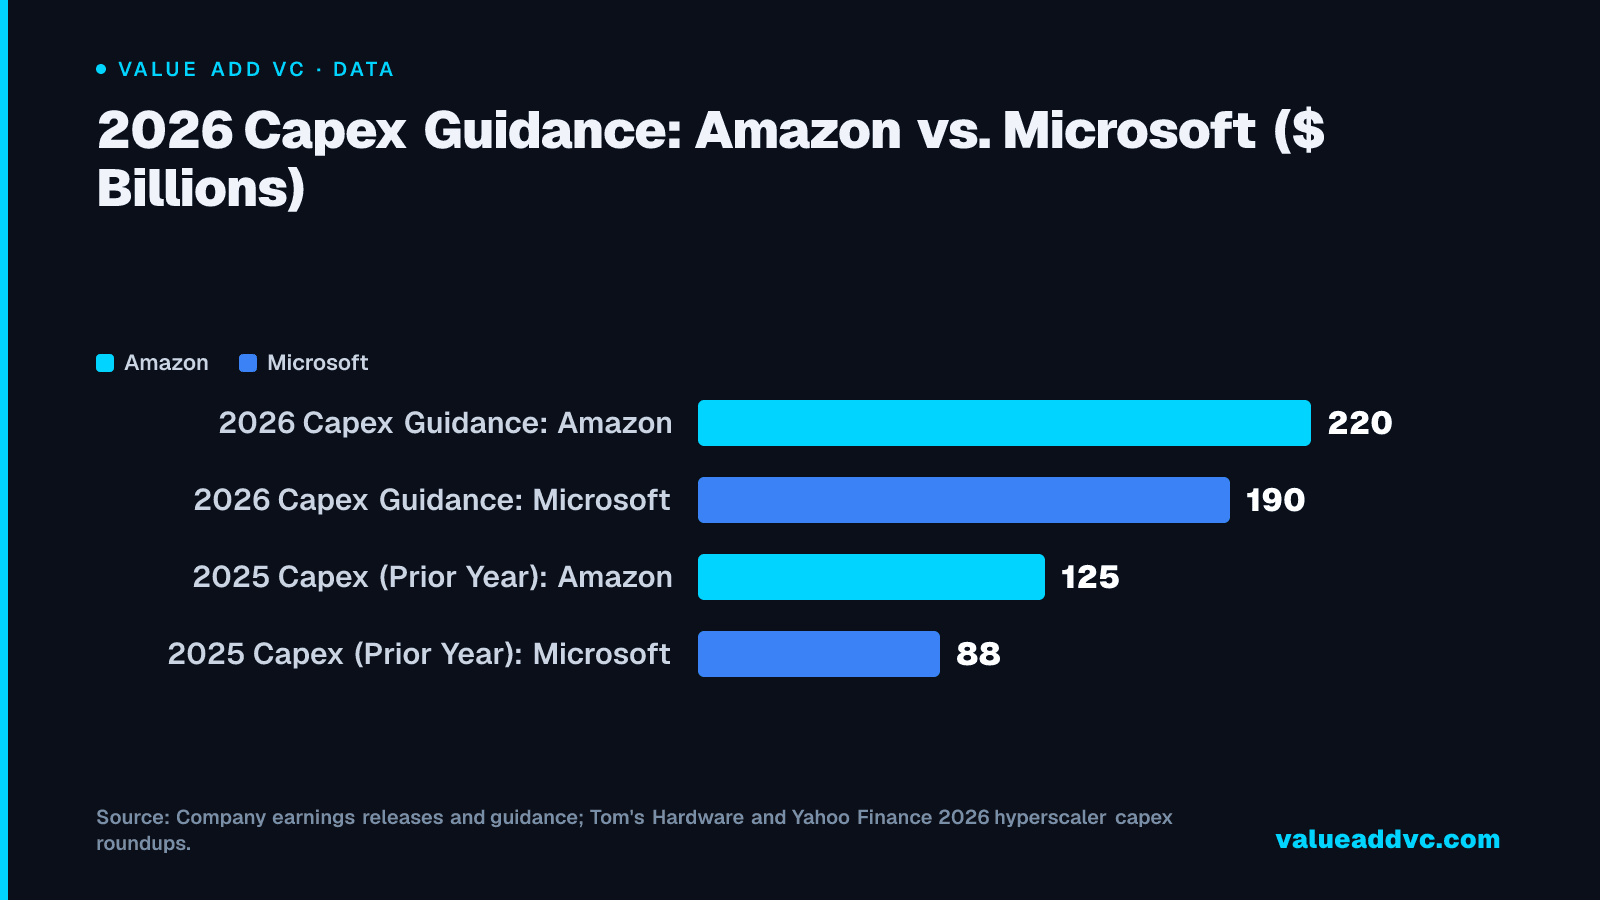
Amazon's raised $220 billion capex plan is now the largest of the four major hyperscalers in 2026, ahead of Microsoft's roughly $190 billion, Google's $175-185 billion guidance, and Meta's $125-145 billion range. Combined, the four companies are now pacing toward roughly $740 billion in 2026 capex — up from about $410 billion in 2025 — almost entirely to build out AI training and inference capacity, with Amazon's guidance raise the single biggest driver of that increase since Q1.
2026 Capex Guidance: Amazon vs. Microsoft ($ Billions)
Company earnings releases and guidance; Tom's Hardware and Yahoo Finance 2026 hyperscaler capex roundups.
Data
| Company | 2026 Capex Guidance | 2025 Capex | YoY Change | Primary AI Chip Strategy |
|---|---|---|---|---|
| Amazon | $220B | $125B | +76% | Nvidia GPUs + Trainium |
| Microsoft | $190B | $88B | +116% | Nvidia GPUs + Maia |
| Google / Alphabet | $175-185B | $91B | ~+96% | Nvidia GPUs + TPUs |
| Meta | $125-145B | $72B | ~+88% | Nvidia GPUs + MTIA |
| AWS Revenue Run Rate | $184B (Q3 2026) | ~$132B (Q3 2025) | +39% | — |
| AWS AI + Custom Chip Run Rate | $25B+ each | n/a (new segment) | triple-digit % | — |
| Nvidia Data Center Revenue | $75.2B (Q1 FY27) | $39.1B (Q1 FY26) | +92% | — |
Figures are 2025-2026 estimates blended from company 10-K/8-K/10-Q filings, Tom's Hardware, Yahoo Finance, CNBC, and Nvidia's Q1 FY2027 earnings release. 2025 capex figures are full-year actuals; Amazon's capex guidance and AWS revenue run-rate figures reflect its Q3 2026 earnings release and 10-Q (filed Oct. 29-30, 2026), while Microsoft, Google, and Meta capex guidance is as of their Q1-Q2 2026 reporting and may have since been updated in their own Q3 2026 earnings.
Trainium: Amazon's Bet on Reducing Nvidia Dependence
The core of Amazon's AWS AI investment strategy is Trainium, its custom AI training and inference chip. AWS says Trainium delivers roughly 30% better cost-performance than comparable Nvidia GPU instances at close to half the sticker cost, and demand has outrun supply — Trainium3, which launched in late 2025, has been running near full capacity ever since. Amazon's custom-silicon business, which also includes the Graviton CPU line, had climbed to an estimated $25 billion-plus annualized revenue run rate by Q2 2026 — up from about $20 billion in Q1 — growing at a triple-digit percentage rate year over year, alongside AWS's separately reported AI revenue, which crossed the same $25 billion run-rate threshold in the same quarter.
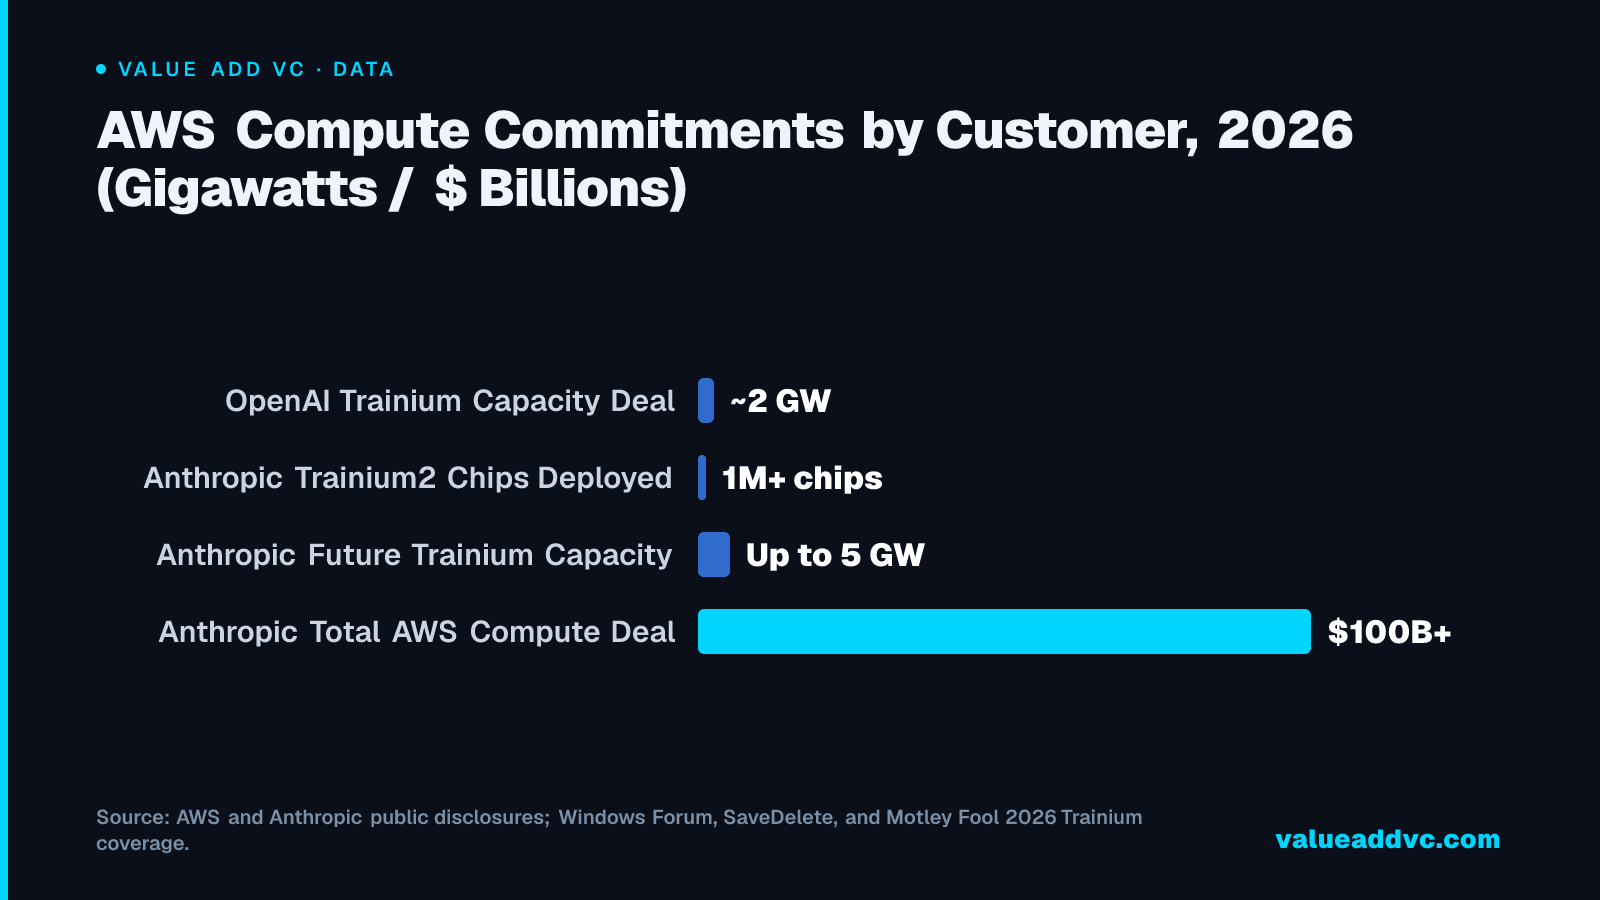
AWS Compute Commitments by Customer, 2026 (Gigawatts / $ Billions)
Anthropic's Trainium and compute commitment now exceeds $100B, while OpenAI has signed for roughly 2GW of Trainium capacity — both a validation of Amazon's chip and a hedge against Nvidia pricing power
AWS and Anthropic public disclosures; Windows Forum, SaveDelete, and Motley Fool 2026 Trainium coverage.
Data
| Item | Value |
|---|---|
| OpenAI Trainium Capacity Deal | ~2 GW |
| Anthropic Trainium2 Chips Deployed | 1M+ chips |
| Anthropic Future Trainium Capacity | Up to 5 GW |
| Anthropic Total AWS Compute Deal | $100B+ |
The most telling development came in June 2026: Amazon reportedly opened early talks to sell Trainium chips directly to third-party data center operators, breaking a decade of AWS-exclusive distribution. On the July 2026 earnings call, Jassy called external Trainium sales "highly likely" within the next few years, though as of Q2 2026 no formal program has launched. If that expands, Trainium stops being just a cost-control tool inside AWS and becomes a second revenue line competing directly with Nvidia for external AI infrastructure spend — the same move Google made with TPUs, but with AWS's much larger cloud distribution behind it. Amazon's compute relationship with Anthropic already goes beyond a customer contract: the roughly $13 billion Amazon has invested in Anthropic since 2024 (an $8 billion investment that year plus $5 billion added in 2026) was carried on Amazon's books at a combined $190.4 billion fair value as of June 30, 2026 — $97.9 billion in convertible notes and $92.5 billion in nonvoting preferred stock — after Anthropic raised $65 billion in a late-May 2026 round at a $965 billion valuation.
The Race to Power AI Workloads: Why Energy Is the Real Bottleneck
Chips get the headlines, but power is the constraint that actually caps how fast Amazon can turn $220 billion into usable AWS AI capacity. Data centers full of Trainium and Nvidia GPUs are useless without gigawatts of dedicated electricity, and every hyperscaler is now racing to lock up power the same way they used to race to lock up land. AWS has been signing long-term nuclear, natural gas, and renewable power purchase agreements specifically to secure capacity for AI data centers years in advance, because the interconnection queue for new grid power in most U.S. regions now runs longer than the time it takes to physically build a data center.
That's also why AWS's chip strategy and its power strategy are really the same strategy: Trainium's roughly 30% cost-performance advantage over comparable Nvidia GPU instances translates directly into needing less power per unit of AI throughput, and in 2026 power is scarcer than capital for every hyperscaler racing to add AI capacity. Anthropic committing to up to 5 gigawatts of future Trainium capacity is less a chip order than a multi-year power reservation, which is why these AI infrastructure deals increasingly get negotiated and announced in gigawatts rather than dollars.
Why AWS's AI Backlog Matters More Than the Capex Number
The capex figure gets the headlines, but AWS's $578 billion backlog — disclosed as "commitments not yet recognized" with a weighted-average remaining life of 6.1 years in Amazon's Q3 2026 10-Q — is the more important number for judging whether the spending is justified. That backlog grew from $364 billion at the end of Q1 2026, to $496 billion at the end of Q2, to $578 billion at the end of Q3, and represents signed customer commitments AWS hasn't yet recognized as revenue, on top of Amazon's separate, decade-long Anthropic compute deal reportedly worth over $100 billion. Put simply: AWS isn't spending $220 billion speculatively. It's spending against contracted demand it can't currently fill, which is why AWS revenue growth accelerated to 39% in Q3 2026 — the fastest pace in nearly five years — even as the company kept its capex guidance at a record level.
That combination — record capex and accelerating revenue growth at the same time — is the strongest evidence yet that hyperscaler AI spending is demand-driven rather than a speculative arms race. Skeptics have argued for two years that hyperscaler capex is outrunning real AI revenue, but AWS's Q3 2026 numbers cut against that thesis directly: if AWS were overbuilding, growth would be decelerating as new capacity came online and had to be discounted to fill it, not accelerating to its fastest pace in nearly five years while the backlog simultaneously keeps growing. I cover the broader four-company version of this story on Big Tech Earnings, where Amazon, Microsoft, Google, and Meta capex and revenue trends are tracked side by side.
What the headline misses
Amazon's reported Q2 2026 net income of $62.6 billion looked spectacular, but most of the beat wasn't from operations. Roughly $53.4 billion of that was a non-cash, non-operating mark-to-market gain from revaluing Amazon's Anthropic stake after Anthropic's $965 billion late-May funding round — an accounting gain, not cash Amazon can spend on data centers. Q3 2026 net income came back down to a more ordinary $20.7 billion, per the Q3 earnings release, confirming that the Q2 spike was mostly a one-time accounting effect rather than a new baseline. There's a second caveat worth naming: Amazon's trailing-twelve-month free cash flow was negative $46.9 billion as of September 30, 2026 — down from the roughly negative $7.6 billion reported for Q2 2026's trailing-twelve-month period — as the $77.3 billion in Q3 capex alone outpaced operating cash flow. That means the AI buildout is being funded increasingly by Amazon's balance sheet and debt rather than free cash flow — a bet that only pays off if the backlog actually converts to recognized revenue at the pace management is projecting.
What Amazon's AWS AI Investment Means for Founders and Investors
For founders building on AWS, the practical read is that compute scarcity isn't over — a $578 billion backlog against $220 billion in annual capex means AWS is still capacity-constrained in the near term, and portfolio companies with reserved GPU or Trainium capacity have a real competitive advantage over those buying on-demand. For investors, Trainium's emerging third-party sales motion is the detail to watch: if AWS starts selling chips outside its own cloud, it starts competing with Nvidia directly rather than just reducing its own Nvidia bill, which changes the long-term margin math on every AI infrastructure company priced off Nvidia's current pricing power.
I track valuations across the AI infrastructure stack on AI Valuations, and the AWS numbers this quarter are the clearest data point yet that the hyperscalers aren't slowing down capex anytime soon — Amazon, Microsoft, Google, and Meta combined are still projected to cross $1 trillion in annual capex by 2027. That trajectory matters beyond the four companies writing the checks: every dollar of hyperscaler AI capex flows through to a long tail of vendors — power utilities, networking suppliers, cooling systems, memory and storage makers, and the construction firms building the data centers themselves — which is why I increasingly evaluate infrastructure-adjacent startups against the specific hyperscaler whose capex cycle they're riding, not just against the broader AI market.
$220B in raised 2026 capex guidance, $46.0B in Q3 AWS revenue, and a $578B backlog that's still growing faster than AWS can build data centers.
Amazon's AWS AI investment isn't a bet on future demand anymore — it's a scramble to keep up with demand that already exists.
The Bottom Line
Amazon's AWS AI investment in 2026 breaks down to roughly $220 billion in total capex guidance — reaffirmed through Q3 — a 76% jump from $125 billion in 2025, funding data centers, power, and a dual chip strategy that buys over 1 million Nvidia GPUs while pushing Trainium toward a possible third-party sales business. AWS revenue grew 39% to $46.0 billion in Q3 2026, its fastest growth in nearly five years, against a $578 billion backlog that sits on top of Anthropic's $100 billion-plus compute commitment. The spending is aggressive — Q3 capex alone was $77.3 billion and trailing-twelve-month free cash flow was negative $46.9 billion — but the backlog and revenue acceleration suggest the underlying build is still tracking behind actual demand, not ahead of it.
Compare Amazon's capex and AI revenue trajectory against Microsoft, Google, and Meta on Big Tech Earnings.
Follow VC and AI market data on Value Add VC. Reach out at t@nyvp.com or @Trace_Cohen.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗