
SpaceX's S-1 is the most anticipated public filing since Google in 2004. The growth numbers don't disappoint, but the losses, the capex, and the governance structure should concern every outside shareholder.
On May 20, 2026, SpaceX filed its S-1 with the SEC. Just over three weeks later, on June 12, shares began trading after pricing at $135. The final prospectus shows 555,555,555 shares sold for about $75 billion in gross proceeds, and CNBC reported the $135 price implied a valuation of about $1.77 trillion and that the deal was set to be the biggest IPO ever. The filing gives us our first audited look at a company that has been the most sought-after private investment for over a decade. For how that filing-to-trading sprint actually works (underwriters, SEC comment letters, the roadshow, and the lockup), see our full breakdown of the IPO process.
What follows is a data-dense breakdown of everything the S-1 reveals: revenue composition, margin structure, Starlink unit economics, AI and Starship capital intensity, and the dual-class governance that gives Elon Musk near-absolute control. One thing to know up front: because SpaceX acquired xAI in February 2026 (and xAI had acquired X in March 2025), the filing restates every period to include both businesses as a third "AI" segment.
Revenue Breakdown: $18.7B in 2025
Per the S-1's segment revenue table, SpaceX grew total revenue 33% year-over-year, from $14,015M in 2024 to $18,674M in 2025. The business is now primarily a connectivity company: the Starlink-driven Connectivity segment was 61% of 2025 revenue and grew 50%, far faster than launch or AI.
| Segment | 2024 Revenue | 2025 Revenue | YoY Growth | % of Total (2025) |
|---|---|---|---|---|
| Connectivity (Starlink) | $7.6B | $11.4B | +50% | 61% |
| Space (Launch) | $3.8B | $4.1B | +8% | 22% |
| AI (xAI and X) | $2.6B | $3.2B | +22% | 17% |
| Total | $14.0B | $18.7B | +33% | 100% |
Launch Services revenue was flat ($2,576M in 2025 vs. $2,584M in 2024) even though SpaceX flew 165 Falcon 9 missions in 2025, according to the filing. The mass-to-orbit data helps explain why: of the 2,213 metric tons SpaceX launched in 2025, 1,901 were internal payloads (its own hardware, such as Starlink satellites) rather than paying customers'. The real growth engine is Starlink: Consumer revenue rose from $4,830M to $7,208M, and Enterprise & Government from $2,769M to $4,179M.
Margins & Profitability
SpaceX was not profitable in 2025. The S-1's statements of operations show a 2025 net loss of $4,937M, after net income of $791M in 2024, and an operating loss of $2,589M. Adjusted EBITDA still grew, but slower than revenue, so the margin fell. A highly profitable Starlink business and an EBITDA-positive (but operating-loss) Space segment sit alongside a loss-making AI segment.
| Metric | 2024 | 2025 |
|---|---|---|
| Revenue less Cost of Revenue (margin) | ~43% | ~49% |
| Adjusted EBITDA Margin | ~38% | ~35% |
| Adjusted EBITDA ($) | $5.35B | $6.58B |
| Income (Loss) from Operations | $466M | ($2.59B) |
| Net Income (Loss) | $791M | ($4.94B) |
The S-1 doesn't report gross margin; the first row is our calculation from reported revenue and cost of revenue ($9,451M in 2025, $7,996M in 2024). The loss is an R&D story: research and development jumped from $3,464M to $8,643M. The segment detail shows where. Connectivity earned $4,423M from operations on $7,168M of Segment Adjusted EBITDA, while the AI segment lost $6,355M from operations. The Space segment, which funded $3,004M of Starship R&D in 2025, lost $657M.
Starlink Deep Dive: The Real Business
Starlink is no longer a side project. It is the majority of SpaceX's revenue and the segment carrying the company's earnings. The S-1's key-metrics disclosures give us our first granular look at subscriber metrics and unit economics.
| Starlink Metric | Value |
|---|---|
| Subscribers (Dec 31, 2025) | 8.9M (vs. 4.4M) |
| Subscribers (Mar 31, 2026) | ~10.3M |
| Subscriber ARPU (2025) | $81/month (vs. $91) |
| Connectivity Share of SpaceX Revenue (2025) | 61% |
| Satellites in Orbit (Mar 31, 2026) | ~9,600 |
| Countries, Territories & Markets | 164 |
| Connectivity Segment Adj. EBITDA Margin (2025) | ~63% |
Subscribers doubled in 2025 while ARPU fell 11%, from $91 to $81 a month. The filing says the decline was "driven primarily by international expansion and the addition of lower priced service plans," and ARPU fell again to $66 in Q1 2026. Starlink's growth is coming from volume, not pricing. Even so, Connectivity's $7,168M of Segment Adjusted EBITDA on $11,387M of revenue works out to a ~63% margin.
Enterprise & Government revenue, which includes Starlink Mobile, grew 51% to $4,179M in 2025. The subscriber count excludes managed enterprise and government contracts in aviation, maritime, land mobility, fixed sites, and government, so the headline subscriber and ARPU metrics understate that part of Starlink.
Capex & Starship Economics
SpaceX spent $20,737M on capital expenditures in 2025, nearly double 2024's $11,163M, according to the S-1. Most of it went into AI compute, not rockets. That is the key tension in the investment case: $6,785M of 2025 operating cash flow, largely from Starlink, against capex three times that size.
| Capex by Segment | 2025 Spend | % of Total Capex |
|---|---|---|
| AI | $12.7B | 61% |
| Connectivity (Starlink) | $4.2B | 20% |
| Space (Launch) | $3.8B | 18% |
| Total Capex | $20.7B | 100% |
Starship is the biggest engineering bet disclosed in the S-1. On top of Space segment capex, SpaceX expensed $3,004M of Starship R&D in 2025. The filing says it expects Starship V3 to carry 100 metric tons, and it ties the next-generation V3 Starlink satellites, V2 satellite-to-mobile service, and orbital AI compute to Starship reaching scale.
The first risk factor in the S-1 warns that "any failure or delay in the development of Starship at scale or in achieving the required launch cadence, reusability and capabilities" could materially hurt the business. The June final prospectus says SpaceX had executed 12 Starship flight tests, but it gives no firm timeline for full reusability.
Ownership & Governance
The prospectus describes a dual-class share structure that concentrates near-absolute control with Elon Musk. It is a governance arrangement more concentrated than Meta's, Alphabet's, or most major tech companies' at IPO.
| Governance Metric | Value |
|---|---|
| Musk Voting Power (post-IPO) | ~82.4% |
| Share Structure | Dual-class (Class B = 10 votes) |
| Shares Sold in IPO | 555.6M |
| Shares Outstanding (post-IPO, Class A + B) | ~13.09B |
| IPO Price | $135/share |
| Gross Proceeds (before over-allotment) | ~$75B |
| Implied Market Value at IPO Price | ~$1.77T |
Musk's 82.4% of the vote means public shareholders have effectively no say in corporate governance. The prospectus states that he "will be able to control the outcome of matters requiring shareholder approval," that Class B holders elect a majority of the board, and that SpaceX will be a Nasdaq "controlled company" exempt from certain governance requirements. It also warns that "the interests of Mr. Musk and entities owned by or affiliated with him may differ or conflict with the interests of our other shareholders."
This is a known-risk trade: you're buying exposure to SpaceX's economics with no governance rights. The stock price will rise or fall based on execution, not shareholder activism. For investors comfortable with founder-controlled companies, this is standard. For governance-sensitive funds, it's a dealbreaker.
Valuation Context
The prospectus lists about 13.09 billion Class A and Class B shares outstanding after the offering. At $135, that is roughly $1.77 trillion, which matches CNBC's reported valuation. The $75 billion raised was only the slice sold to the public. Here is what the price implies against 2025 results:
| Valuation Multiple | At $135 IPO Price (~$1.77T) | At Aug 18 Close (~$1.89T) |
|---|---|---|
| Market Value / Revenue (2025) | ~95x | ~101x |
| Market Value / Adjusted EBITDA (2025) | ~268x | ~287x |
| Price / Earnings (2025) | n/a (net loss) | n/a (net loss) |
These multiples use market value, not enterprise value, and trailing 2025 results. By any trailing measure, the valuation is rich. The bull case rests on: (1) Starlink subscriber growth continuing at its current doubling pace, (2) enterprise and government revenue compounding, (3) AI compute and xAI's products turning their capex into revenue, and (4) Starship opening entirely new markets. Bears will point to the ~270x adjusted EBITDA multiple, the $4.9B net loss, and $20.7B of annual capex with uncertain returns.
Key Risks From the S-1
The S-1's risk factors section is long. Here are the risks that matter most to investors:
The S-1's first risk factor: any failure or delay in Starship at scale would delay V3 satellites, satellite-to-mobile, and orbital AI compute. No firm timeline to full reusability is given.
Launches depend on FAA licensing and environmental reviews. Delays in approvals or launch-site availability could slow Starship and Starlink deployment.
The AI segment lost $6,355M from operations in 2025 and took $12.7B of the year's $20.7B in capex. Returns on that spending are unproven.
Approximately one-fifth of 2025 revenue came from U.S. federal agencies. Changes in government priorities or funding could reduce demand.
Per the filing, Musk does not devote his full time to SpaceX. He is also CEO of Tesla and involved in Neuralink and The Boring Company.
82.4% voting control and controlled-company status mean few checks on executive decisions.
Update: Q2 2026 Earnings, the First Report as a Public Company
SpaceX reported its first quarterly results as a public company on August 4, 2026, in its Q2 earnings release and 10-Q. The numbers show the S-1's growth story continuing, but the stock reaction shows public investors are pricing capex risk far more aggressively than private tender-offer buyers ever did.
SpaceX Quarterly Revenue by Segment, Q2 2026
Connectivity (Starlink) remains the largest segment at $4.3B, while launch/space services grew 29% YoY to $962M.
SpaceX Q2 2026 earnings release (Form 8-K, Exhibit 99.1) and Form 10-Q, August 4, 2026.
Data
| Item | Value |
|---|---|
| Connectivity (Starlink) | $4.3B |
| Space (Launch) | $962M |
| AI (xAI and X) | $2.6B |
| Total Revenue | $7.8B |
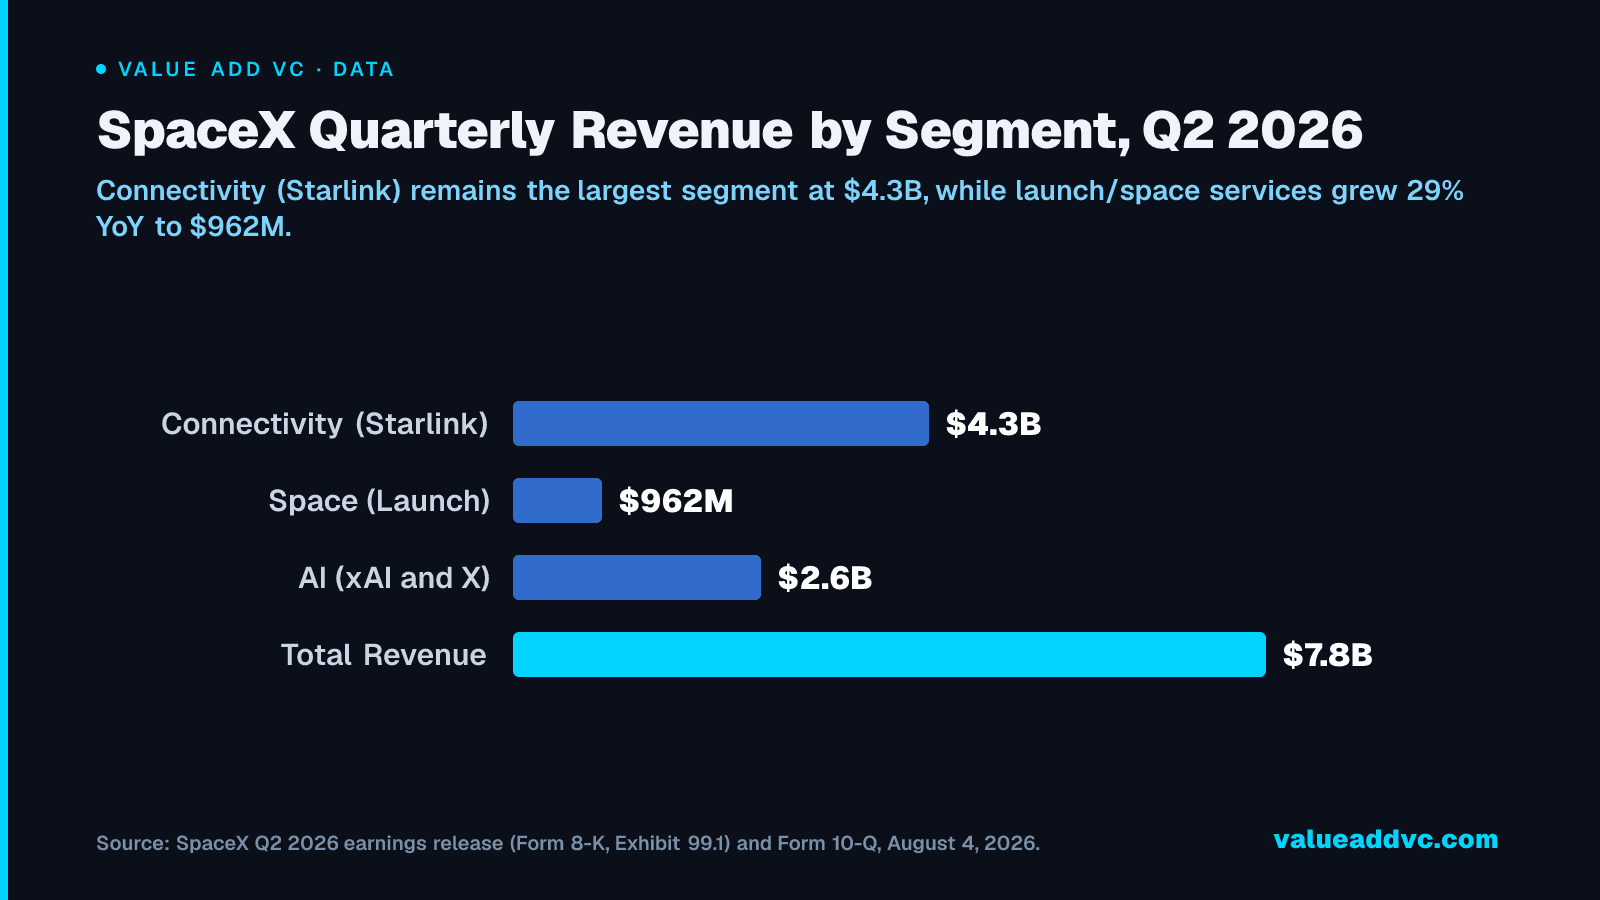
Connectivity revenue rose 66% year-over-year to $4.3 billion, but Starlink's average revenue per subscriber fell about 22%, from $85 to $66, as subscribers doubled to 12.0 million. Net loss narrowed to $541 million from $1 billion a year earlier, and adjusted EBITDA nearly tripled to $3.5 billion. In the Q2 2026 earnings call transcript, management attributes the ARPU decline to geographic expansion and says continued subscriber momentum should still drive strong revenue growth.
What spooked the market wasn't revenue. It was capex. SpaceX spent $18.4 billion in the quarter, $15.8 billion of it in the AI segment, and the stock fell roughly 8% in the days after the print despite the top-line beat, according to coverage of the release. That single quarter of spending equals nearly 90% of the $20.7 billion full-year 2025 capex disclosed in the S-1, a sign of how fast the post-IPO AI build-out is running.
On August 18, 2026, SPCX closed at $143.34 a share, per Yahoo Finance price history. Multiplied by the 13.18 billion Class A and Class B shares outstanding on the 10-Q cover (as of July 28), that puts SpaceX's market capitalization near $1.9 trillion. That is about 6% above the $135 IPO price, but 36% below the intraday all-time high of $225.64 set on June 16. Since listing, the stock has ranged from $104.83 to $225.64, a swing that says more about how the market is repricing capex risk in real time than about any change in Starlink's underlying subscriber math. For the fuller valuation-multiple picture, see our SpaceX valuation repricing timeline.
Bottom Line
SpaceX's S-1 confirms what the private market priced in for years: Starlink is a high-margin, fast-growing connectivity business, and Falcon 9 flew 165 missions in 2025. It also shows what the private market couldn't see. Consolidated with xAI and X, SpaceX grew revenue 33% in 2025, but its adjusted EBITDA margin slipped from 38% to 35% and it swung to a $4.9B net loss.
The questions are: Can AI and Starship earn a return on $20.7B of annual capex, a pace Q2 alone nearly matched? Can Starlink keep doubling subscribers as ARPU falls? And does 82.4% voting control in the hands of a founder who also runs Tesla create unacceptable governance risk?
At roughly $1.77 to $1.89 trillion, you're paying about 95 to 101 times trailing 2025 revenue. Starlink's $7.2B of 2025 Segment Adjusted EBITDA is real, but the price is mostly a bet on AI compute, Starship economics, and Musk's ability to execute across several companies at once. Track the live numbers on our SpaceX IPO Dashboard.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗