
The median public SaaS company traded at 4.8x EV/forward revenue on October 15, 2026, across the 65 companies in the BVP Nasdaq Emerging Cloud Index, up from 2.94x at the April 13 low and down from 15.95x at the February 2021 peak.
That median is the honest answer to "what does SaaS trade at." The figure most often quoted, the index's 8.6x average revenue multiple, is real but misleading: it is an average, and a few names trading at 30x to 40x drag it far above what the typical company gets. This page uses the per-company figures that Bessemer Venture Partners publishes behind the index site, cross-checked against the weekly comp set that Altimeter's Jamin Ball publishes in Clouded Judgement.
Current SaaS revenue multiples: the October 2026 answer
Current SaaS revenue multiples sit at 4.78x enterprise value to forward revenue for the median public cloud software company as of October 15, 2026, per BVP Cloud Index data. The middle half of the 65-company index trades between 3.27x (bottom quartile) and 7.56x (top quartile). Only 10 of the 65 trade at 10x or more.
A second public comp set lands in the same place. Clouded Judgement's October 9, 2026 update put the overall median EV/NTM revenue multiple at 4.3x, with the top five names at a median 37.3x and the 10-year Treasury yield at 5.2%. The two series differ in membership and timing (BVP's reading is six days later), but both put the typical public SaaS stock between 4x and 5x next-year revenue.
| Measure | Reading | As of | Source |
|---|---|---|---|
| Median EV/forward revenue (65 cos) | 4.78x | Oct 15, 2026 | BVP Cloud Index data |
| Top-quartile EV/forward revenue | 7.56x | Oct 15, 2026 | BVP Cloud Index data |
| Bottom-quartile EV/forward revenue | 3.27x | Oct 15, 2026 | BVP Cloud Index data |
| Average revenue multiple (index headline) | 8.6x | Oct 15, 2026 | cloudindex.bvp.com |
| Average revenue growth (index headline) | 20.6% | Oct 15, 2026 | cloudindex.bvp.com |
| Overall median EV/NTM revenue | 4.3x | Oct 9, 2026 | Clouded Judgement |
| Top-5 median EV/NTM revenue | 37.3x | Oct 9, 2026 | Clouded Judgement |
| Median net revenue retention | 110% | Oct 9, 2026 | Clouded Judgement |
How we counted: medians and quartiles from the per-company EV/forward revenue figures and median series published on cloudindex.bvp.com (65 constituents, fetched October 16, 2026, data through the October 15 close); Clouded Judgement figures as printed in its October 9, 2026 post.
What do the biggest public SaaS companies trade at?
The spread inside the index is enormous. Palantir traded at 40.2x forward revenue on October 15, 2026, while Sprinklr traded at 1.1x, a 36-fold gap between two companies that both sell enterprise software. Security and data infrastructure hold the top of the table; seat-based application software sits at the bottom.
| Company | EV / fwd revenue | Revenue growth | LTM FCF margin | Market cap |
|---|---|---|---|---|
| Palantir | 40.2x | 92.8% | 43.4% | $482B |
| CrowdStrike | 34.3x | 25.8% | 27.3% | $251B |
| Cloudflare | 31.3x | 35.9% | 12.3% | $113B |
| Palo Alto Networks | 19.4x | 34.5% | 30.2% | $303B |
| Datadog | 17.0x | 35.6% | 26.4% | $96B |
| Snowflake | 14.7x | 35.1% | 19.3% | $118B |
| ServiceNow | 8.3x | 24.0% | 28.7% | $154B |
| Salesforce | 4.7x | 10.8% | 33.4% | $203B |
| Workday | 4.1x | 12.8% | 26.8% | $47B |
| Adobe | 3.4x | 12.9% | 39.2% | $98B |
| HubSpot | 2.6x | 19.8% | 21.9% | $12B |
| Monday.com | 1.9x | 21.9% | 20.4% | $4.0B |
How we counted: 12 of the 65 BVP Cloud Index constituents, chosen as the six highest forward multiples plus six widely followed application names; figures as published in the company table on cloudindex.bvp.com (S&P Capital IQ data), as of October 15, 2026. Market caps rounded.
EV / Forward Revenue, Selected Public SaaS Companies (Oct 15, 2026)
Security and data infrastructure trade at 15x-40x; seat-based apps sit near 2x-5x
BVP Nasdaq Emerging Cloud Index company data (S&P Capital IQ), Oct 15, 2026
Data
| Item | Value |
|---|---|
| Palantir | 40.2x |
| CrowdStrike | 34.3x |
| Cloudflare | 31.3x |
| Palo Alto | 19.4x |
| Datadog | 17.0x |
| Snowflake | 14.7x |
| ServiceNow | 8.3x |
| Index median | 4.78x |
| Salesforce | 4.7x |
| Adobe | 3.4x |
| HubSpot | 2.6x |
| Monday.com | 1.9x |
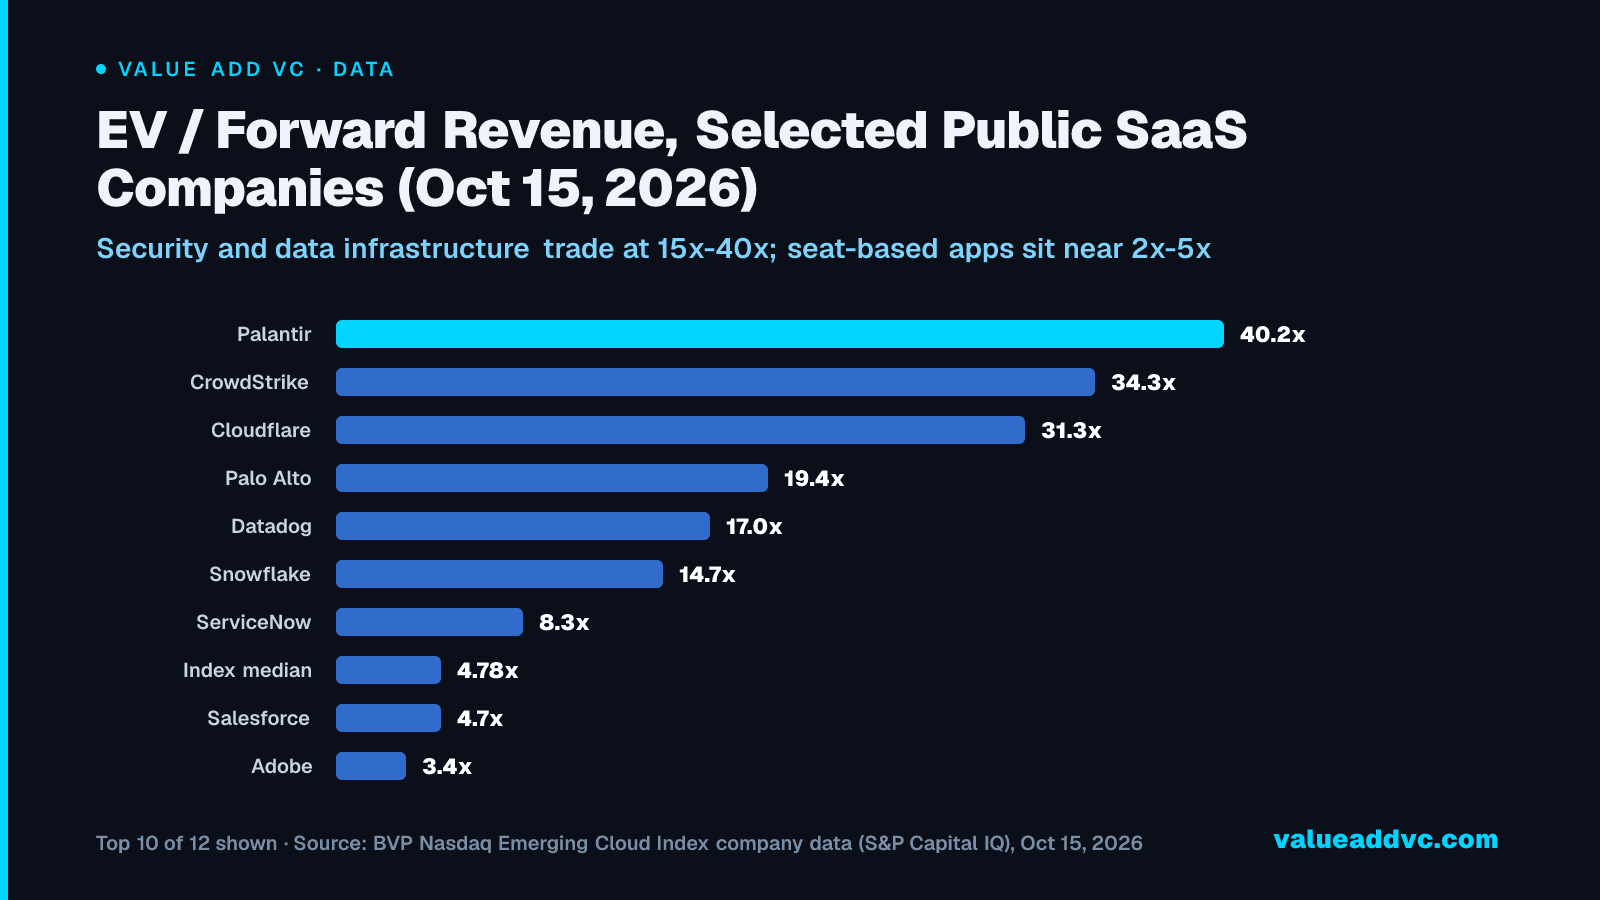
Two of the largest application franchises now trade below the median. Salesforce, at 4.7x with 10.8% growth and a 33.4% free cash flow margin, is priced like a mature cash generator; see our Salesforce valuation multiple breakdown. HubSpot, growing 19.8%, trades at 2.6x, which says more about how investors view seat-based software exposed to AI agents than about HubSpot's own growth rate (our HubSpot multiple analysis covers the earlier read).
How does revenue growth change a SaaS multiple?
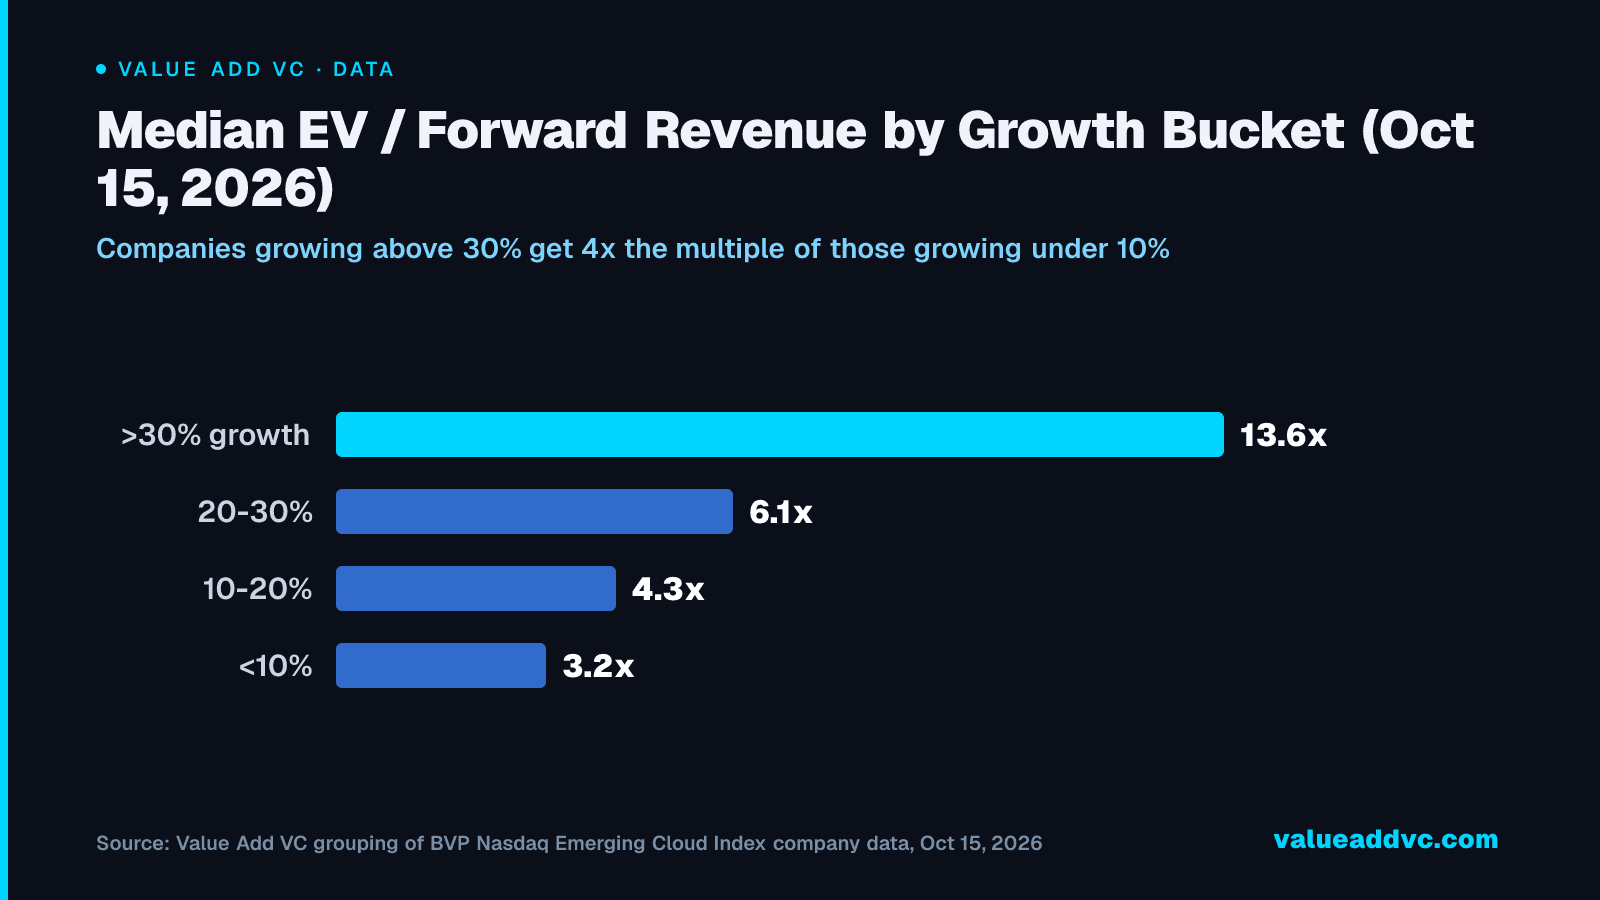
Growth is still the biggest single driver. Grouping the 65 BVP constituents by their reported revenue growth rate, the median company growing faster than 30% traded at 13.6x forward revenue on October 15, 2026, more than four times the 3.2x median for companies growing under 10%. That grouping is Value Add VC's arithmetic on BVP's published company data.
| Growth bucket | Companies | Median EV / fwd revenue | Comp set |
|---|---|---|---|
| Above 30% growth | 10 | 13.6x | BVP (Value Add VC grouping) |
| 20% to 30% growth | 18 | 6.1x | BVP (Value Add VC grouping) |
| 10% to 20% growth | 27 | 4.3x | BVP (Value Add VC grouping) |
| Below 10% growth | 10 | 3.2x | BVP (Value Add VC grouping) |
| High growth (above 22% NTM) | ~10 | 19.3x | Clouded Judgement, Oct 9 |
| Mid growth (15% to 22% NTM) | n/a | 7.0x | Clouded Judgement, Oct 9 |
| Low growth (below 15% NTM) | n/a | 3.4x | Clouded Judgement, Oct 9 |
How we counted: BVP rows group all 65 constituents by the revenue growth rate in the index's company table and take the median EV/forward revenue in each group, as of October 15, 2026; Clouded Judgement rows use its own buckets on projected NTM growth, as printed on October 9, 2026 (it sets the high-growth cutoff so about 10 companies qualify).
Median EV / Forward Revenue by Growth Bucket (Oct 15, 2026)
Companies growing above 30% get 4x the multiple of those growing under 10%
Value Add VC grouping of BVP Nasdaq Emerging Cloud Index company data, Oct 15, 2026
Data
| Item | Value |
|---|---|
| >30% growth | 13.6x |
| 20-30% | 6.1x |
| 10-20% | 4.3x |
| <10% | 3.2x |
Growth alone does not buy a premium, though. Monday.com grew 21.9% and trades at 1.9x; Klaviyo grew 26.4% and trades at 2.5x. Both sit in buckets whose medians are far higher. One read on this: investors are discounting seat-based and marketing software on the risk that AI agents shrink seat counts, regardless of current growth.
Does the Rule of 40 still drive SaaS valuation multiples?
Yes, and the gap is wider than the growth gap. The BVP data includes each company's growth plus free cash flow margin (the Rule of 40 score). The 15 companies scoring 50 or higher traded at a median 11.8x forward revenue on October 15, 2026; the 9 scoring under 30 traded at a median 2.5x, by Value Add VC's grouping.
| Rule of 40 score | Companies | Median EV / fwd revenue |
|---|---|---|
| 50 or higher | 15 | 11.8x |
| 40 to 50 | 16 | 5.0x |
| 30 to 40 | 25 | 4.3x |
| Below 30 | 9 | 2.5x |
How we counted: all 65 BVP Cloud Index constituents grouped by the growth-plus-FCF-margin score in the index's company table; median EV/forward revenue per group; as of October 15, 2026. Source: cloudindex.bvp.com.
The jump between the top two rows is the striking part: crossing from a 40-50 score to 50-plus more than doubles the median multiple, from 5.0x to 11.8x. Adobe is the exception that proves the rule is not sufficient: its score is about 52 (12.9% growth plus a 39.2% FCF margin), yet it trades at 3.4x, because the market prices its slower growth and AI disruption risk over its cash flow.
How have SaaS multiples moved since 2021?
The BVP median series runs back to August 2013. It peaked at 15.95x on February 10, 2021, ended 2021 at 10.69x, fell to 4.64x by the end of 2022, and held near 6x at the ends of 2023 and 2024. The 2026 drawdown was the deepest in the series: the median hit 2.94x on April 13, 2026, below the 4.24x trough of November 2022.
Median Public SaaS EV / Forward Revenue, Year-End 2019-2026
The 2026 low (2.94x, Apr 13) undercut the 2022 trough before a summer recovery
BVP Nasdaq Emerging Cloud Index median multiple series, cloudindex.bvp.com, fetched Oct 16, 2026
Data
| Item | Median (x) | Top quartile (x) |
|---|---|---|
| 2019 | 7.49 | 11.16 |
| 2020 | 15.62 | 22.51 |
| 2021 | 10.69 | 17.11 |
| 2022 | 4.64 | 6.98 |
| 2023 | 6.04 | 8.45 |
| 2024 | 6.01 | 8.46 |
| 2025 | 4.92 | 8.21 |
| Oct 2026 | 4.78 | 7.56 |
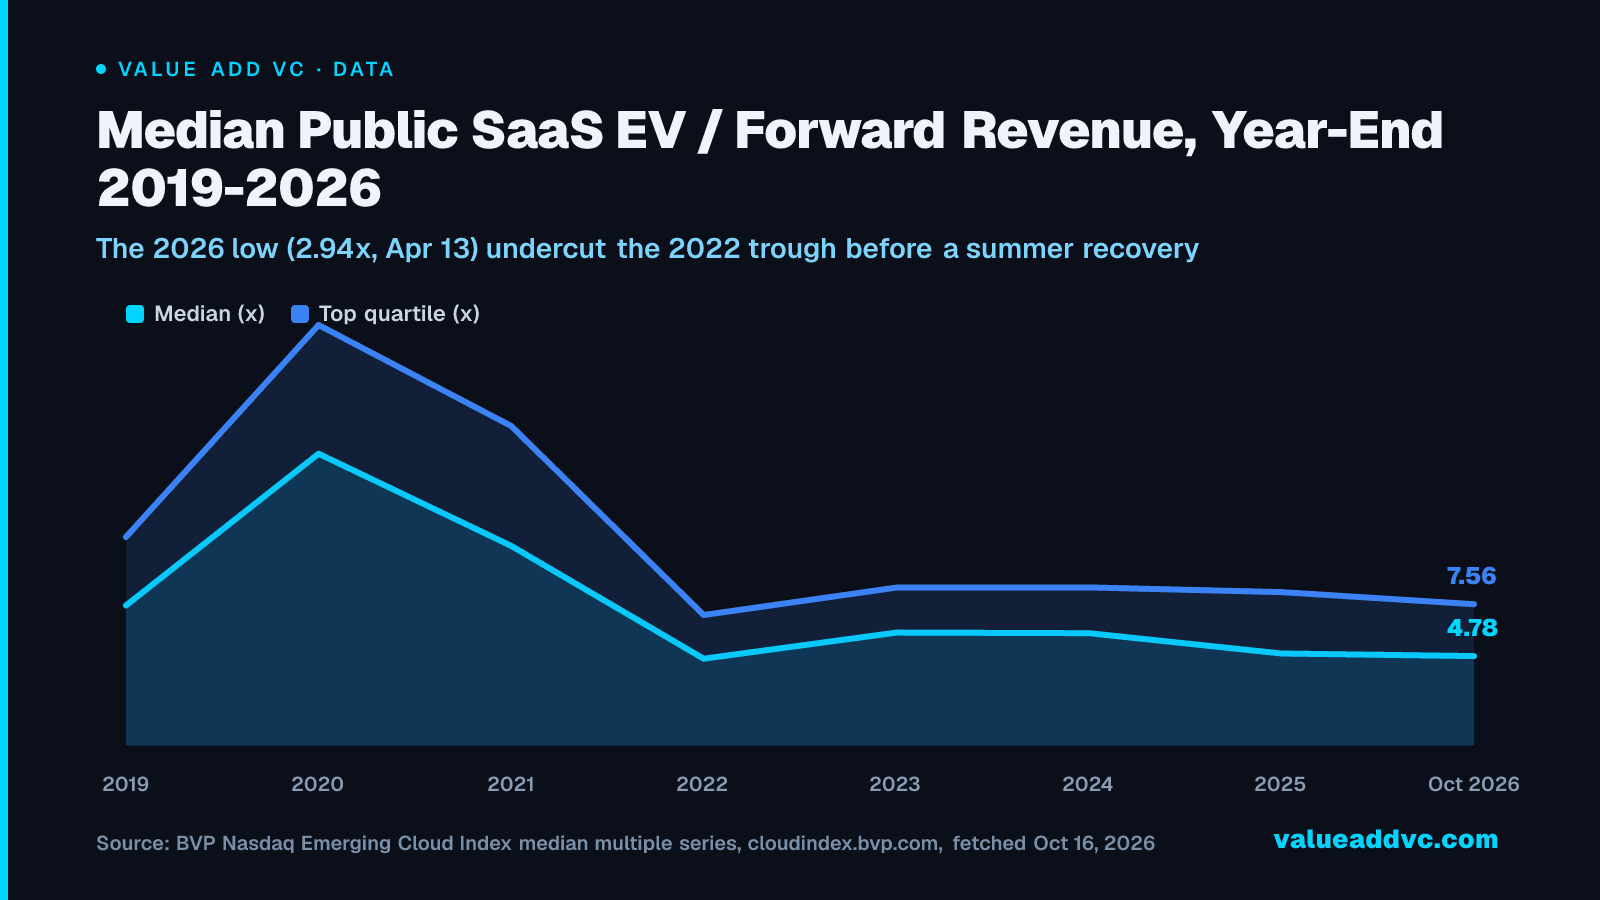
The 2026 path month by month, using the last reading of each month: 4.49x in late January, 3.09x in February, 2.95x at the end of March, 3.20x in April, 3.30x in May, 3.37x in June, 3.69x in July, 4.61x at the end of August and 4.38x at the end of September, before 4.78x on October 15. Clouded Judgement's series shows the same summer re-rating: its overall median was 3.3x in its July 24, 2026 update, with the mid-growth bucket at 4.9x, against 4.3x and 7.0x on October 9.
For the longer history and what the 2021 peak meant for private rounds, see SaaS multiples in 2026 vs 2021. The interactive SaaS valuations tool applies these ranges to a company's own ARR and growth.
What do public SaaS multiples mean for private companies?
Public multiples are the anchor for private SaaS pricing, usually with a discount for illiquidity and smaller scale. A private company growing 20% with a modest free cash flow margin is being compared, implicitly, with a public median near 4x to 6x forward revenue, not with the 8.6x index average. Our guide to how private SaaS valuations compare to public multiples covers the discount, and SaaS multiples by ARR range shows how scale moves the number.
AI-native companies are priced on a different curve. Private AI companies have raised at run-rate multiples far above anything in the public SaaS table; AI startup valuation multiples in 2026 lays out that gap company by company. The public market is paying up for the same thing: the companies at the top of the BVP table (Palantir, CrowdStrike, Cloudflare, Snowflake) are the ones investors see as beneficiaries of AI workloads.
What the headline misses
- Average versus median. The 8.6x headline on the index site is an average of 65 companies; the median is 4.78x. Quoting the average as "what SaaS trades at" overstates the typical multiple by roughly 80%, by Value Add VC's arithmetic.
- Forward multiples rest on estimates. EV/forward revenue divides by analysts' consensus revenue for the next twelve months. If those estimates fall, the multiple rises without the price moving, so a cheap-looking multiple can be a falling-estimate trap.
- Index membership changes. The BVP index adds and removes companies over time (Figma and Netskope sit in it today), so the 2021 and 2026 medians do not describe the same set of businesses. Acquired and delisted companies drop out, which flatters the survivors.
- Size concentration. Of the index's $2.7 trillion combined market cap, Palantir alone is about $482 billion. A median ignores that weighting, which is the right choice for benchmarking a typical company and the wrong one for describing where the money sits.
How to use these SaaS multiples
Start from the bucket, not the headline. A public-company comp for a business growing 15% with a 20% free cash flow margin is the 4.3x median of the 10%-20% growth bucket, not 8.6x. Then adjust for the two variables the market is paying for in October 2026: a Rule of 40 score above 50, which has carried a median 11.8x, and exposure to AI infrastructure or security demand, which sets the top of the table. Treat any comp from before the 2026 drawdown, including year-end 2025's 4.92x, as stale. For the investor behind the index, see Bessemer Venture Partners; for the comp-set author, see Altimeter Capital.
Sources: BVP Nasdaq Emerging Cloud Index headline figures, company table and median series (fetched October 16, 2026); Clouded Judgement, October 9, 2026 and July 24, 2026; methodology notes from the SaaS Capital Index. Published by Value Add VC · Editor-in-chief: Trace Cohen.
Latest from the Pulse
Get VC data most people never see
— free to subscribe
Trace's notes on venture, AI and startups, a few times a week. Join 5,000+ subscribers. No spam.
No spam, unsubscribe anytime. Sent via Substack · Privacy · or subscribe on Substack ↗